

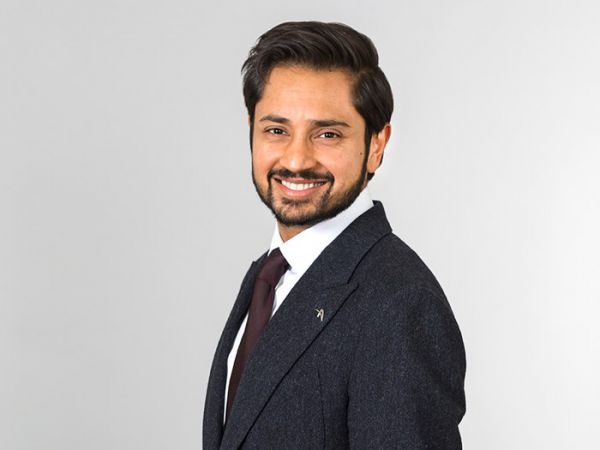
Aditya Mittal and Etienne Schneider newly elected as directors of ArcelorMittal
The Annual General Meeting and Extraordinary General Meeting (‘General Meetings’) of shareholders of ArcelorMittal (‘the Company’) held today approved all resolutions by a strong majority. 68% of the voting rights were represented at the General Meetings. In view of the Covid-19 outbreak, the Board of Directors of ArcelorMittal had decided to hold this year’s General Meetings by virtual-only format, as permitted by Luxembourg law. Arrangements were made to allow shareholders to vote electronically and by proxy voting. The results of the votes will be posted shortly on https://corporate.arcelormittal.com under ‘Investors – Equity investors – Shareholders-events – AGM – Annual General Meeting and Extraordinary General Meeting of shareholders, 13 June 2020’ where the full documentation regarding the General Meetings is available.
In particular, the shareholders:
- Approved the re-election of Mr. Lakshmi N. Mittal, Mr. Bruno Lafont, Mr. Michel Wurth and the election of Mr. Aditya Mittal and Mr. Etienne Schneider as directors of ArcelorMittal, for a term of three years each;
- Decided to increase the authorised share capital of the Company and change the Articles of Association accordingly
Source and Photo: ArcelorMittal


China’s automotive sector rebounds
China’s automotive sector continued to recover in May, starting to make up for some of the losses earlier in the year. Implied steel demand has also increased, driven partly by an increase in commercial vehicle sales, Kallanish notes.
China produced 2.187 million vehicles in May, up 18.2% year-on-year, according to the China Association of Automotive Manufacturers (CAAM). That was still some way off the peaks of over 3m units/month in the industry’s heyday in 2017, but was a rapid improvement from just 285,000 units in February during the lockdown. Over the year to date, automotive output is now 7.787m units, down 24.15 y-o-y.
Implied finished steel demand was up 21.26% at 3.83m tonnes in May, Kallanish calculates. Over the year, demand is now down just 18.61% y-o-y at 13.777mt. This is because of a resurgence in truck sales. Commercial vehicle sales were up 48% in May to 520,000 units, driven by trucks for infrastructure projects.
Italian April car output was almost zero
Italian car output tumbled again year-on-year in April after falling in Q1, says local carmakers’ association Associazione Nazionale Filiera Industria Automobilistica (Anfia) in a report monitored by Kallanish.
According to Anfia data, total automotive production in Italy fell in April by as much as -85% after another heavy fall of -64% on-year in March. Passenger car output in April “was almost zero”, Anfia says. “In April less then 400 cars were produced in Italy”, it adds. In April 2019 Italian carmakers produced 49,000 cars.
While industrial production in Italy declined by over -42% in April and by -18.7% on-year in the first 4 months of the year, total automotive output in the country fell by almost -45% on-year in January-April, Anfia comments.

Latin American April steel output falls 34% on year due to COVID-19
Latin America crude steel production in April plunged 34% on year to 3.55 million mt, induced by the coronavirus pandemic, regional steel organization Alacero said June 12.
From January to April, production decreased 14% compared to a year ago reaching 18.3 million mt, Alacero said in a statement.
According to Alacero, the decrease reflected the generalized low demand and interruption of operations in response to the effects of the slowdown.
In April, crude steel production via the BOF route decreased 22% compared with March at 3.56 million mt, an amount had not been seen since 2009.
April rolled steel production in Latin America dropped 32% on year to 2.9 million mt .
“In April, the effects of the pandemic began to spread; however, the impact has been felt mostly in Argentina and Brazil, with a decrease of 73% and 37% in rolled steel output, respectively, compared to April 2019,” Alacero said.
In a strategy to balance supply and demand, some plants across the region have shut their blast furnaces. In April and May, seven blast furnaces were closed due the pandemic representing a combined capacity of almost 7 million mt, according to Alacero.
The group said capacity utilization as of April within Latin America was at 42%, with Brazil at 43%, Mexico at 60% and Argentina at 18%.
“Latin America’s comeback will occur differently among its countries, and the region will probably be one of the last to normalize its economic activity,” said Francisco Leal, Alacero’s general manager.
Leal added the industry is a capital intensive and high fixed-cost business “that needs to work at 80% of its capacity to ensure a modern and efficient production plant, as well as retention of its human resources.”
The organization estimates that this situation will persevere until the third quarter and will be the norm for the industry in the short term.
— Priscilla Antunes
Member states support EC steel safeguards proposal: sources
Most EU member states support the steel safeguards review draft implementing act presented by the European Commission. There are 20 member states in favor, representing 92% of the EU population, an EC source told S&P Global Platts on June 12.
“The commission will consequently proceed to the formal adoption of the implementing act with a view to having it in force by July 1 at the latest. The act modifies the current safeguard measures in a number of areas concerning the management of the tariff quotas,” the source said. The safeguard committee met June 12.
“We expect the final decision to be published in the Official Journal of the EU during the week starting June 22,” said another source close to Brussels.
According to the first source, the EC draft implementing act has the same terms as the one the EC sent to the WTO on May 29.
As already reported by Platts, the EC proposal singled out hot-rolled coil and sheet, proposing a return of the country-specific quotas after a period of having a global quota in place. Those countries are Russia, Turkey, India, South Korea and Serbia. A cap of 30% share will nevertheless continue applying to the use of the residual quota in the fourth quarter to prevent crowding-out effects.
Other proposals move all country-specific quotas from annual to quarterly in order to ensure “a more stable flow of imports and minimize the risk of undue import surge during the remaining duration of the measures,” as stated in the notification document.
The EC also recommended some solutions to ensure that the smaller exporting countries, which use the global quotas, are not crowded out by those exporters enjoying country-specific quotas. In addition to keeping the unlimited access to the residual quotas in some product categories the EC proposes new restrictive regimes for certain products.
Assofermet, the Italian service center association representing one of the main European steel importing groups, said they are against the EC proposal because country-specific tariff-rate quotas (TRQ) do not reflect the actual level of imports and the residual TRQs are likely to remain largely unused.
Eurofer, the European steelmakers’ association, stated after the WTO notification was published that the EC proposal was insufficient and “unhelpful” in tackling the sharp decline in steel demand. Eurofer demanded a significant reduction in the size of the tariff-free import quota.
— Annalisa Villa, Wojtek Laskowski
Global longs export markets shrink further amid protectionism
As expected, things are getting more difficult for exporters in the global steel market. The EU opened fire with an antidumping investigation on HRC imports from Turkey, with Turkey firing back with duties on steel products from the EU. Canada started a similar investigation against imports of heavy plates from several countries, while Egypt has been working on a 10 percent duty. Accordingly, the world market is shrinking further and Russian mills are taking the lead and dominating the market. It will be a real game of survival for a while and the cost of production is the key.
Global longs consumption still very uncertain, prices move up especially in Asia
While prices are heading up (particularly in Asia), consumption in the global long steel products market seems very uncertain. Demand for physical steel is held up by the optimism in the futures market. This is somewhat worrying for the supply and demand situation in the market if the support from the futures market were to weaken. On the bright side, despite the impact of the Covid-19 pandemic the World Steel Association (worldsteel) in its recent report still foresees an increase in steel demand in China in the current year, predicting a rise of one percent from 2019 to 916.5 million mt. This helps restrict the fall in global steel demand in 2020 to an anticipated drop of 6.4 percent, whereas demand in the rest of the world excluding China is foreseen to contract by 14.2 percent compared to 2019. Meanwhile, market players are hoping that June and July will be months of stabilization before a recovery later in the year.
Brazilian steel industry faces serious demand crisis
Brazilian crude steel production continued to fall in April amid the ongoing Covid-19 pandemic. Its crude and rolled steel outputs in the given month fell by 39 percent and 36 percent, respectively, while its semis output declined by 24 percent, all year on year, according to the Brazilian Institute of Steel (IABr). Domestic steel sales in April decreased by 36 percent year on year, in line with apparent consumption of steel products which collapsed by 35 percent. Due to the adverse conditions in the international market, Brazilian steel exports fell by 17 percent year on year. These data demonstrate the seriousness of the demand crisis that the Brazilian steel industry is facing, which led it to operate with only 42.2 percent of its installed capacity in April. As a result, in the first four months of the year Brazil’s crude steel production fell by 14 percent year on year to 10 million mt. The output of finished steel products contracted by nine percent year on year to 7.1 million mt due to the decrease in apparent consumption in the period under review (down nine percent to 6.2 million mt). In the January-April period, Brazil’s steel imports contracted by 18 percent to 705,000 mt, while its steel exports fell by five percent year on year to 4.1 million mt.
Mills in EU struggle, buyers only order what they need and wait for lower prices
The construction business in the EU has been hit harder than expected by the Covid-19 crisis. New building permits in May were substantially lower than in March and April and many projects have either been put on hold or stopped. The public sector still has big infrastructure projects in the pipeline. However, since the Covid-19 crisis has kept everybody at home for almost three months, these projects have been delayed significantly. Cut-and-benders are trying to grab any order available as they start to believe the next one will be at a lower price anyhow. EU-based mills are selling hand to mouth as buyers will only order what they need and wait for prices to fall further. Italian mills are selling at almost any price to collect cash, and this has pulled the market downwards. The same goes in Poland where mills are pushing clients into placing orders by lowering their prices almost daily. At the same time, scrap prices have increased, which is a toxic combination for cut-and-benders and the mills. The biggest threat for importers is the ongoing discussions in Brussels on the reevaluation of safeguard measures. The EU is once again changing the rules in the middle of the game under pressure from EUROFER.
Demand recovers in ferrous scrap market
On the other hand, demand in the ferrous scrap market has recovered and the raw material inventories that were depleted have had to be rebuilt as the markets have been opening up after the lockdowns. Activity has been general and has taken the markets by surprise.
Stimulus packages and normalization procedures provide a boost
Stimulus packages around the world are acting as fuel. There are concerted efforts to avoid a U- or L-shaped economic rebound, with a V-shaped rebound being what the financial markets are seeking. Finally, normalization procedures have been initiated in many countries. The automotive sector is back in business in various countries, e.g., in the US, EU and Turkey.
China’s recovery a very important factor
China has acted as a powerhouse in the past month for commodities. Industrial activity in the country returned to normal in May. The quick return of Chinese companies to the market and China becoming an importer have been very positive factors.
Japanese production cut is good news for other exporting countries
Japanese mills have announced a production cut of approximately 20 million mt, which of course is not a positive development for them but does represent good news for other exporters in the global market.
Difficult to talk about the existence of a global market nowadays
We cannot really talk about the existence of a global market nowadays. There will be 100 percent self-sufficiency in Asia in the medium term and then exporters will be wandering in search of the next market. Every producer outside of China is struggling with insufficient volumes and, under such circumstances, competition can come from anywhere at any time. The mills in many countries have to follow what the Russian mills are offering in the market and then to decide whether they can compete.
Future remains very much uncertain but some signs of optimism seen
The current status of the market is clearly unstable. The markets are still assessing the damages from the Covid-19 pandemic and the future remains very much uncertain. But at least investors and industries are showing optimism.
Source: Irepas