


National Federations discussed the distribution of steel in their markets

EUROMETAL participated in a meeting with national federations this Thursday 15th of October.
Nine federations participated at the online meeting among 17 registered.
The meeting started by a presentation on Circular Steel Construction in the Netherlands followed by a round table on the situation of Steel Distribution in each country represented.

Liberty makes non-binding offer to acquire thyssenkrupp steel
Liberty Steel has made a non-binding indicative offer to acquire the steel unit of thyssenkrupp, the rapidly-expanding steel group confirms. The offer is supported by a number of financial institutions. Liberty says it wants to intensify the dialogue with thyssenkrupp and to engage in further due diligence to present a potential binding offer.
“With both transformation experience and an entrepreneurial approach, a possible combination of LIBERTY Steel and thyssenkrupp Steel would create a strong group well positioned to tackle the challenges faced by the European steel industry and accelerate the transformation to GREENSTEEL,” Liberty Steel says in a note seen by Kallanish.
“From an economic perspective, there is potential for a compelling industrial concept given that the businesses are complementary with respect to assets, product lines, customers, and geographic footprint,” the group continues.
The combination of the two steel groups would help the EU steel industry move towards the bloc’s aim to become climate neutral by 2050 as part of the European Green Deal announced last December. Liberty’s own target is to become carbon neutral by 2030.
Liberty’s discussions with thyssenkrupp have been conducted on a non-exclusive basis, and there is no certainty that the discussions will lead to any agreement or transaction.
Were the acquisition to materialise, it would continue a stunning expansion for Liberty Steel, which just over five years ago was known mainly as a trading house. It now stands to become the main steelmaking competitor in Europe to ArcelorMittal.
Interestingly, given the potential thyssenkrupp acquisition news, Liberty parent GFG Alliance has appointed Premal Desai as its new Group Chief Operating Officer effective 1 January 2021. Desai held several leadership positions at thyssenkrupp AG from 2006 to 2020, most recently as chief financial officer and executive chairman of thyssenkrupp Steel.

Non-China steel demand not to recover to 2019 level until 2022: worldsteel
Steel demand recovery following the coronavirus pandemic is expected to occur at different rates in different regions but may be drawn-out outside China, according to the World Steel Association.
China’s steel demand is expected to increase by 8% in 2020, aided by government infrastructure stimulus and a strong property market, but demand in the rest of the world is expected to decrease by 13.3%. “We don’t expect a return of steel demand to the levels of 2019 before 2022 in the rest of the world, excluding China,” Edwin Basson, worldsteel general director, told reporters Oct. 15 during the launch of the association’s October Short Range Outlook.
Developed economies are expected to register a decrease in steel demand by 14.4% this year from 2019 to 336 million mt and rise by 7.9% in 2021 to 363.5 million mt, according to worldsteel’s outlook. Steel demand in the developed economies in 2019 was 393.4 million mt.
The global financial crisis saw a major fall in developing economies but during the coronavirus pandemic declines have been seen in both developed and developing economies, with a “short, sharp effect on steel demand, with most of the impact seen in the H1 2020,” Basson noted. Overall, steel demand is forecast to fall 8%-18% this year from 2019 levels, depending on country or region, he said.
In developed economies manufacturing sectors, which were only just about to recover from the slowdown in late 2019, were pushed back again by the pandemic. Even with a strong bounce back after the economies reopened, which has closed the gap with pre-pandemic levels, double-digit contraction over the whole year still seems unavoidable, the association stated.
US sees substantial government support
In the US, recovery from the lockdown has been strong, aided by substantial government support measures. The manufacturing downturn was shorter and less acute than expected, worldsteel said. However, the US is still struggling to control the virus’s spread, and the recovery momentum might taper off in the coming months, it said. The outlook for 2021 is less optimistic, with a subdued outlook for construction and auto production. According to worldsteel, US steel demand for this year is expected to be down by 15.3%.
In the EU, where the negative economic impact of COVID-19 was softened by strong social security schemes and fiscal stimulus, expectations are for a decrease in steel demand of 15.5% this year from 2019 to 134.3 million mt of crude steel.
In the Middle East, demand is expected to fall 19.5% this year, while in India it should fall 20%, marking the deepest decline in steel demand in decades. However, a “relatively fast recovery” should take place in India next year, supported by rural consumption and government investment in infrastructure, worldsteel said.
Basson said the Short Range Outlook has taken into account a second wave of the coronavirus pandemic, roughly of the same magnitude as the first, but expects governments and economies to respond differently.
“Economic systems cannot tolerate a similar response as in the first wave with complete meltdown and shutdown… that is not tolerable in the long term: what we will most likely see is a desire by governments and societies to keep their economic systems ticking over with more regional or specified focused events, such as lockdowns in certain areas or periods,” he said. “That’s what we’ve built into the second scenario where there will be a desire to keep economic systems moving forward with construction and infrastructure.”
The construction sector remained more resilient to the COVID-19 shock as many governments focused on implementing public projects, Basson noted. Following the easing of lockdowns this continued in the advanced economies, mostly driven by infrastructure investment. The automotive sector suffered “dramatic consequences” from the pandemic, he said. In April, automotive production fell by 70% -90% in many countries. While supply-side issues dissipated relatively quickly, post-lockdown recovery has been constrained by a slow return in demand.
In China, robust domestic demand has facilitated a faster recovery, but overall from January to August 2020 China’s motor vehicle production is still 9% below the 2019 equivalent, according to worldsteel.
— Annalisa Villa, Diana Kinch

Steel demand decline in 2020 to be less than previously forecasted: worldsteel
Worldsteel has reviewed its Short Range Outlook (SRO) for 2020 and 2021 to show a much smaller demand decline than previously expected, as the sector recovers from the impact of the coronavirus pandemic, the association of world steel producers stated Oct. 15.
China’s strong recovery will mitigate the reduction in global steel demand this year while the post-lockdown recovery in steel demand in the rest of the world has been stronger than was earlier expected, but still shows a deep contraction in 2020 with only a partial recovery expected in 2021.
In 2020 worldsteel forecasts that steel demand will contract by 2.4% from last year, dropping to 1,725.1 million mt, rather than by 6.4%, as it forecasted in June. In 2021 steel demand is expected now to recover to 1,795.1 million mt, with an increase of 4.1 % over 2020, while in June the association expected an increase of 3.8% year on year.
The forecast assumes that despite the current resurgence in infections in many parts of the world, nationwide lockdowns will not be repeated. Instead, selective and targeted measures will be able to contain this second wave, the association stated.
China’s steel demand is expected to increase by 8% in 2020, aided by government infrastructure stimulus and a strong property market, but for 2021, steel demand is expected to stay flat on the expectation that the manufacturing sector’s rebound will be limited.
Overall steel demand in the developed economies is expected to fall by 14.9% in 2020 and increase by 7.9% in 2021 and to reach 2019 pre-pandemic levels only in 2022.
During the press briefing worldsteel, as by policy, did not discuss prices, but pointed out that in future steel prices will be increasingly influenced by carbon prices.
Steelmakers are targeting carbon emissions reductions across all regions, using different production routes. The use of more challenging technologies may also allow new steel products to be produced in future, worldsteel general director Edwin Basson underscored.
— Annalisa Villa

Sunningwell renews lease at Huta Czestochowa plate mill, operations continue

Sunningwell International Polska has renewed its lease of Polish heavy plate producer Huta Czestochowa and remains interested in buying the mill despite a failed previous attempt, Marek Frydrych, the Warsaw-based investment firm’s board president, said Oct 15.
The new lease, which gives Sunningwell the operational control over Huta Czestochowa, is valid between Oct.14 and June 30, 2021, Sunningwell said in a statement. It has been the leaseholder of the mill since September 2019.
“The lease renewal means “the company will continue its operations as normal and can keep taking and fulfilling orders,” Frydrych said.
The mill is waiting for its trustee in bankruptcy to call for a new tender or an auction in the next week or so. The previous sale failed to conclude earlier this month after the only bidder – Sunningwell – refused to pay Zloty 220 million ($58 million) for the mill due to legal issues, Frydrych said.
Sunningwell is continuing talks to buy the mill, he added.
Huta Czestochowa’s operations are at a level significantly under its annual capacity of 800,000 mt of plate: January-September, the mill produced 200,000 mt slabs, 164,000 mt heavy plate and 25,000 mt prefabricated steel goods.
With the renewed lease Sunningwell will keep production going at the mill. However, the target of 300,000 mt/year slab output, allowing for reaching profitability, seems unlikely to be achieved this year, Frydrych said.
— Wojtek Laskowski

Worldsteel lifts demand forecast on rapid China recovery
Worldsteel has revised up its forecast for global finished steel demand thanks mainly to China’s stunning rebound following the initial Covid-19 pandemic shock at the start of the year. Global demand is now seen falling only -2.4% on-year in 2020 to 1.725 billion tonnes.
This compares to the -6.4% decline forecast in worldsteel’s previous short-range outlook (SRO) in June. This is a difference of 71.2 million tonnes, indicating sentiment has improved significantly.
Chinese steel demand is now seen growing 8% in 2020 to 980.1mt, almost equalling its 2019 growth rate. This will be aided by government infrastructure stimulus and a strong property market.
The world excluding China, however, has seen a deep demand contraction as a result of the pandemic and is unlikely to return to pre-Covid-19 levels until at least 2022, worldsteel director general Edwin Basson said during Thursday’s virtual SRO press conference attended by Kallanish. Demand in the world excluding China is forecast to slump -13.3% in 2020 to 745mt. This compares to the -14.2% drop forecast in June.
A recovery from the pandemic remains fragile due to the second wave of infections, continued social distancing measures, elevated unemployment and weak confidence. The second wave is especially risky given the upcoming flu season in the Northern Hemisphere. “The risk is tilted toward the downside,” worldsteel says. “A W-shaped recovery cannot be ruled out and a full recovery in 2021 is unlikely.”
However, the forecast assumes that despite the current resurgence in infections in many parts of the world, nationwide lockdowns will not be repeated. Instead, selective and targeted measures will be able to contain the second wave, worldsteel observes. “What we will most likely see is the desire by governments and societies to at least keep their economic systems ticking over,” Basson commented.
Global demand in 2021 is seen rising 4.1% on-year to 1.795 billion tonnes, driven by a rebound in the world excluding China, which will be slightly more pronounced in the developing economies. This indicates the pandemic will have a short, sharp “V” effect on steel demand, with most of the downturn seen in the first half of 2020, Basson pointed out.
Chinese demand is seen flat on-year in 2021. Infrastructure and housing projects initiated in 2020 will continue to support demand next year. However, if the economy recovers fully, the government could reverse its stimulus policy to cool down the construction sector. Given the weak global economic outlook, meanwhile, the manufacturing sector’s rebound will be limited.
ArcelorMittal Spain advances low-carbon steel production project
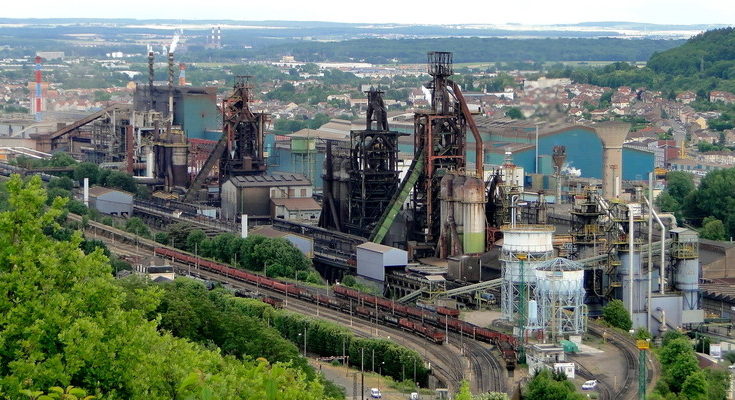
ArcelorMittal will implement the injection of coke-oven gas at blast furnace 2 at its Gijón plant in northern Spain in the next three months, Kallanish learns from the company.
“ArcelorMittal Asturias has the most advanced coke oven gas project, with an injection of grey hydrogen, recovered from gases including natural and coke oven gas,” ArcelorMittal says. “This is an efficient, cost-effective method that allows steelmakers to reduce CO2 emissions and would result in reduced coke consumption.”
The first use of hydrogen-rich coke oven gas at Gijón’s blast furnace 2 is scheduled for late December or the begging of January 2021, a company spokesperson explains.
The new method will allow for coke replacement rates of up to 78% in the pig iron manufacturing process. The co-injection project at BF2 has an annual saving potential of 40,000 tonnes of coke and CO2 emissions reduction close to 140,000t.
ArcelorMittal Europe is implementing decarbonisation projects in almost all of its flat steel production units. The steelmaker expects to supply its first 30,000t of carbon-neutral steel products to customers this year and to reach 600,000t in 2022 (see Kallanish passim).

Assofermet warns of anti-dumping stainless market distortion
Italian steel trade association Assofermet has expressed concern regarding the start of further anti-dumping proceedings on imports of stainless cold rolled products from India and Indonesia. The association believes new duties would lead to substantial market distortions.
The new scenario of production concentration in Europe is a matter of concern for all players in the value chain, Assofermet observes. The EU has already imposed anti-dumping duties on stainless hot rolled products from China, Indonesia and Taiwan, and on cold rolled imports from China and Taiwan, as well as safeguard measures. The bloc is thus escaping international competition, the association says.
“Europe will find itself completely isolated from the global market, creating a protected island where local producers will benefit from an increasingly favourable position at the expense of downstream consumers,” the association says in a note sent to Kallanish. “Should this investigation lead to the imposition of new duties, the distribution sector would be gravely impacted and the downstream manufacturing industry would lose international competitiveness.”
Further protectionist interventions would trigger unjustified price increases in the EU. This means the manufacturing sector, already damaged by the Covid-19 pandemic, would see increased raw material costs compared to international competitors.
The possibility of unfair advantages for producers would also create an unbalanced market within the European industry, since producers sell not only to distribution but also to end-users, the association warns.
New anti-dumping duties would disrupt long term partnerships and commercial relationships. This would be the case particularly with Indian suppliers who have gained market share in Europe and are now considered vital suppliers for quality and product range, Assofermet concludes.
Electric vehicles represent opportunities for steel: AISI
The rapid growth of the electric vehicle market isn’t a threat to steel – and in fact reinforces efforts already underway in the high-value advanced high-strength (AHSS) steel arena, Kallanish hears from the American Iron and Steel Institute.
“As the industry shifts toward more electric vehicles, lightweighting will remain front and center,” said AISI automotive program vice president John Catterall. “Automakers can combine the potential mass reduction enabled by AHSS with appropriate engine technologies to achieve their desired fuel-economy goals.”
Three main opportunities exist in the electric vehicle arena for steel, Catterall adds – EV battery packaging, B-pillarless designs, and overall lightweighting.
“As battery efficiencies improve the battery pack costs decrease, as does the premium an automaker is willing to pay for mass reduction. Advanced grades of steel also allow thinner gauges thus optimizing the available package pace for more batteries, resulting in greater range on a single charge,” Catterall says.
Third-generation AHSS is being used in vehicle side structures, which eliminates the need for B-pillars – or the vertical supports near the midsection of a vehicle.
“With more than 200 grades of innovative steels available to automakers today, and more in development, applying the right grade of steel for the right application allows for exceptional occupant protection, durability and crash energy management in a cost-efficient manner,” Catterall says.
Steelmaker Liberty makes bid to buy Thyssenkrupp Steel Europe
Liberty Steel Group made a non-binding offer Oct. 16 to buy Thyssenkrupp Steel Europe, Liberty confirmed in a statement sent to S&P Global Platts.
Liberty’s proposal is a non-binding indicative offer subject to certain assumptions about the business and backed by “a number of financial institutions,” according to Liberty. No financial details were disclosed.
Liberty said it would like to start negotiations to make a binding offer should the two steelmakers reach agreement.
“From an economic perspective, there is potential for a compelling industrial concept given that the businesses are complementary with respect to assets, product lines, customers, and geographic footprint,” Liberty said.
“We will now carefully look at this offer. At the same time, we will continue the discussions with other potential partners in the same way as before. Our goal is to make the steel business sustainably fit for the future. It is important for us to find the best solution,” a Thyssenkrupp spokesperson told Platts.
Thyssenkrupp’s share values surged in early trading when the news broke.
Analyst Marc Gabriel at Bankhaus Lampe told Platts that the sale of the Elevator unit late July has improved Thyssenkrupp’s overall position, which means that there would be less pressure at Thyssenkrupp to sell the steel unit, but on the other hand the company is also in the position to make concessions.
The powerful union and worker representatives at Thyssenkrupp are likely to need some convincing for a takeover by Liberty, according to sources and the head of union IG Metall, Knut Giesler opposed the news early Oct. 16 in a Reuters interview.
Thyssenkrupp has been openly saying they would be searching for a potential buyer for the steel unit following the collapse of merger talks with Tata Steel in 2019. There have been previous reports that Swedish steelmaker SSAB would be a suitable partner for a tie-up while German steelmaker Salzgitter denied any current talks, while a revival with Tata has also been under discussion, if a solution with the troubled UK Port Talbot plant could be found.
While Thyssenkrupp has repeatedly said it will not disclose who it is in discussions with, sources close to the company have said that the companies mentioned in the press reports are still not out of the question.
— Laura Varriale