


Turkish mills hopeful for Section 232 removal after US elections, others see no change

Some Turkish mills seem hopeful that US will remove Section 232 duties against Turkey following the elections, while others are not expecting much of a change in US trade policies following the presidential election, no matter the result.
The relations between Turkey and the US showed ups and downs during President Donald Trump’s presidency. Trump raised tariffs on imports of Turkish steel from 25% to 50% in August 2018 under Section 232 law, amid increased political tension between the countries over Turkey’s detention of a US religious leader. Turkey’s tariff rate on steel was later dropped back to 25% in May 2019, amid some improvement in relations between the countries.
Trump even threatened to destroy Turkey’s economy during the pastor Brunson crisis, but after the crisis was resolved, the presidents of the both countries began to call each other as friends.
However, a win by democratic presidential nominee Joe Biden could also raise tensions between Turkey and US again as long as Recep Tayyip Erdogan remains as president, as Biden previously said he will work with the opposition leaders in Turkey for a government change, which drew both the ruling and the opposition parties’ reactions in Turkey.
Independently from the election results, some Turkish steel producers seem hopeful for the removal of the Section 232 duties against the country after the elections.
“As Turkey and [the] US are strategic partners, [the] US should lift the Section 232 tariffs on Turkey after the elections, independently [of] who will win, to reach the goal of $100 billion in trade between the countries,” Veysel Yayan, general secretary of the Turkish Steel Producers’ Association, told S&P Global Platts, noting the goal previously set by Erdogan and Trump. “I am hopeful that after the elections the new president (Trump or Biden) will take a step in this regard.”
“If Biden will win, I don’t think that his previous statements about Turkish president Recep Tayyip Erdogan will be a determinant factor for the relations between the countries, as Turkey and US are strategic partners for years and good economic and political relations will be in favor of both countries,” he added. “Turkish steel is well known in US with its high quality. However, in the absence of Turkish steel, Vietnam became one of US top steel supplier. To remove Section 232 against Turkey, like some other countries, will be also beneficial for the steel consuming sectors of the US.”
Ugur Dalbeler, CEO of major Turkish steelmaker Colakoglu, who is also the vice president of Turkish Steel Exporters’ Union (CIB), however was not as optimistic.
“I am not expecting a much change in US policies after the elections,” he told Platts. “Actually, Liberals (Democrats) have a more protectionist approach than Republicans. However, due to his character Trump made some moves (Section 232) that others couldn’t temp to.”
Even under a Biden administration, the new US government may prefer to maintain these duties for a while, as countries have adopted a more protectionist attitude in recent years, due to the pandemic, he noted.
“So, independently of the election results, I am expecting this environment to continue for a while,” Dalbeler said.
The US share in Turkey’s overall steel exports was at 15% in 2016, however, this share fell to as low as 3% due to the Section 232 duty in 2019, according to Turkish Steel Exporters’ Union (CIB) data. Turkish mills were exporting 2.4 million mt of steel to the US in 2016, but this figure declined by 85% to just 350,00 mt in 2019, representing a loss of $850 million.
— Cenk Can

Fewer competition concerns on Liberty takeover of Thyssenkrupp Steel than Tata JV: Jefferies
A takeover of Thyssenkrupp Steel Europe by Liberty Group is less likely to attract as significant competition concerns from the European Commission than the attempted Tata Steel Europe/Thyssenkrupp joint venture did, according to research firm Jefferies Oct. 21.
The main reason for this is that Liberty is currently not a major supplier to the automotive industry, Jefferies said. Whereas a Tata/Thyssenkrupp steel major would have had a combined market share of 25% in Europe, a Liberty and Thyssenkrupp business together would amount to a “sub-10%” exposure, reflecting a tonnage-based exposure of “less than one-third that of Tata Steel”, Jefferies estimates.
In 2019, the EC had concerns over metallic coated and laminated steel for packaging applications and galvanized flat carbon steel for the automotive industry and eventually were terminated by Thyssenkrupp and Tata.
Jefferies highlighted that Liberty does not publicly break down plant-by-plant market exposure but estimates that Liberty’s exposure to packaging steel is less than Tata’s 12% in Europe, while Thyssenkrupp has a 15% market share.
Competition authority hurdle limited
“We believe the new, conceptual deal would create significantly lower market shares in those end markets and thus be more palatable for the EC,” the Jefferies report said.
Liberty mad a non-binding offer Oct. 15 to acquire Thyssenkrupp’s steel assets, but did not disclose any financial details and Thyssenkrupp reiterated it would hold non-exclusive talks with other potential bidders as well.
There have been previous reports that Swedish steelmaker SSAB would be a suitable partner for a tie-up, while German steelmaker Salzgitter denied any current talks. A revival of merger talks between Tata and Thyssenkrupp has also been under discussion, as a solution continues to be sought for the troubled UK Port Talbot plant, sources close to the company have said that the companies mentioned in the press reports are still not out of the question.
Semis producer HKM could benefit from takeover
Market participants told S&P Global Platts that Liberty’s bid for Thyssenkrupp was not unexpected, with the UK-based steel company having pursued several other ventures over the last few years.
Semis producer Huettenwerke Krupp Mannesmann (HKM) — jointly owned by Salzgitter, Vallourec and Thyssenkrupp — has seen its slab output falter in recent years. However, there is growing optimism among market participants that the potential sale could support the struggling mill.
“Liberty Steel buys slab and Thyssenkrupp has not [produced] slab to a satisfactory level so [the bid] is not surprising. They [Liberty] want to boost their production by supplying slabs from Germany,” a German distribution source said.
A German trader said the potential acquisition could mean a “vast improvement” in productivity for HKM, adding it could be a “win-win for both parties — if SSAB doesn’t slip in at the last moment.”
— Laura Varriale, Amanda Flint

Assofermet opposes EU safeguard extension: “End-users need to compete globally”

The EU steel safeguard, the former Ilva plant in Taranto, and the verticalization of production are some of the hot issues facing the Italian steel industry. SteelOrbis discussed these topics with Riccardo Benso and Tommaso Sandrini, respectively president of the Italian association of distributors of steel and ferrous and non-ferrous metals Assofermet and president of Assofermet’s steel section.
The Assofermet officials said they completely disagree with the views of the European Steel Association (EUROFER) and the Italian steel producers’ association Federacciai regarding the EU safeguard on steel imports, which producers would like to be extended beyond the deadline of June 30, 2021. “We hope that it will reach its termination,” Mr. Sandrini stated, adding that “it is difficult to implement it” and that “a market protection system such as a safeguard, being limited to a specific link in the supply chain, can only have a temporary validity.” Otherwise, he continued, “a series of effects is created on the downstream market, which suffers a negative impact in terms of material supply.” Added to this is the risk of reactions from trade partners who, as EU Trade Commissioner Vladis Dombrovskis warned a few days ago, could answer with strong retaliation. The producers argue that, in the absence of the current measures, there would be trade distortions that would turn out to be worse than any retaliations, but Sandrini, representing distributors, stated, “Talking about the risk of market distortions due to import flows at a time when European producers are struggling to satisfy orders is quite contradictory.” Furthermore, according to Sandrini, “defining the system of antidumping duties as ineffective is a false representation. Apart from the unique case of antidumping against Russian hot rolled coils (which affects only the Russian steelmaker Severstal), all duties have resulted in a zeroing of flows from the countries or companies involved.” The same zeroing is now desired by steel producers for hot rolled coils coming from Turkey, a country that in recent years passed from being a net importer to being a net exporter, albeit for limited volumes, and therefore is seen by EU steel producers as an enemy to be opposed. However, “we rarely talk about trade balances,” commented Assofermet president Riccardo Benso, noting that “for flat products this balance is well below five percent of cast steel in the EU-28. Therefore, the share which is considered as a disturbance is almost negligible.” He went to say, “In value, exports balance imports, which is normal. We import commodities and export products with high value added.” Those who are impacted by commercial measures are end-users, i.e., those who use steel to produce manufactured goods and “need to be able to compete in the best way in the global market,” Benso added.
Another issue that worries steel distributors is the verticalization strategy implemented in recent years by some steel producers. “It is not correct that those who benefit from a protection system for what is their core business can freely expand into the next ring of the supply chain, with prices that can even reach the limit of predatory,” said Sandrini. According to the president of Assofermet’s steel section, “We have to be consistent. If the market is left free, then it is acceptable for a supplier to expand downstream.” On the contrary, “it is not right that those who benefit from a dominant position do so.” Distributors believe that this is one of the issues that needs to be brought to the attention of the EU, since “the European Commission must find a balance in this regard.” Benso also emphasized that too often institutional forces such as IndustriAll Europe (the European trade union of industry) “do not have the data or are conditioned by only one part of the supply chain, i.e., producers, and therefore play a game exclusively in favor of EUROFER.” However, they forget that at a European level “the end-user sector has more than 3 million employees, against the 330,000 in the steel sector,” underlined Benso.
Speaking of jobs at risk, one cannot fail to address the Ilva plant issue in Italy, which obviously the distribution sector is also following with attention and concern. The president of Assofermet said he is “not very confident” about the final outcome of the negotiations underway between the government and ArcelorMittal, the company that is running the plant. “Some time ago, I viewed negatively the entry of the Italian state into this situation, while today I think it is the only option to optimize the situation,” he added. For both Benso and Sandrini, however, there is too much discussion about who will be in control of the Taranto-based plant and too little about what needs to be done to relaunch it. To date, the Assofermet leaders recalled, the site produces less than 4 million mt of steel per year and is experiencing growing difficulties in fulfilling and respecting orders.
Finally, Benso and Sandrini commented on the market trend this year. After the dramatic and complex phase of the lockdown months, an overall positive period started in June, with very good order levels in the entire distribution sector. In the summer months, explained the president of Assofermet’s steel section, “everyone recorded positive performances, even higher than in the same months last year.” This was due not only to the need to restock, but also “because there was a need to work, to process, to recover the orders that had been left behind.” This was also accompanied by a “positive situation regarding compliance with payments,” Sandrini said. Coming to today, Sandrini continued, “We live in a situation where, in the face of strong stimuli in the Asian market, and with China becoming a net importer of steel, prices have risen significantly, returning to levels that are satisfactory for steelmakers.” Recently there has been a good recovery in consumption, but some concern remains for the evolution of the Covid-19 emergency. Sandrini reiterated that there are serious difficulties in supplying the market due to the closure of import sources. According to Benso and Sandrini, the problem in the coming months “will be less about prices, and more about not being able to obtain steel products in the time and in the way necessary to satisfy the requests of end-users.” The possibility that some European plants may be restarted in the short term is not much comfort, since, Sandrini argued, “if there is no import, there will always be a shortage situation in the domestic market.”
Benso agreed that in the near future the key element, especially for the automotive sector, will be the availability of material: “Today, it is very complicated to procure auto material. There are few and very narrow channels, and little possibility of operating in a market where in the past we as distributors operated with satisfaction and where end-users were also very satisfied. It is important to allow those who produce high-tech products with steel to buy as they prefer, within the limits of “fair trade”, in order to adjust their industrial costs according to the global competition to which they are subjected.” Hence, once again, Assofermet’s appeal to abandon the idea of imposing barriers on imports to defend against supposed enemies from the outside. “The risk is that Europe manifests difficulties in quickly adapting supply to consumption,” concluded Assofermet’s president.
Turkey could become EU’s largest steel producer by year-end: Dalbeler
Highlighting that Turkey, which is currently the second largest steel producer in the EU, has caught up to Germany as of the end of September, Ugur Dalbeler, the CEO of major steel maker Colakoglu and the vice president of Turkish Steel Exporters’ Association (CIB) told local news agency Bloomberg HT that Turkey could become EU’s largest steel producer by year-end.
Steel production in Turkey exceeded last year’s performance as of the first nine months of 2020, Dalbeler said, adding that this situation is different compared with other parts of the world.
“The growth figure in China, which has a 60% share in total global steel production, reached 4.9%, while other parts of the world shrinked by 10%,” Dalbeler said adding that the 1% growth figure that Turkey reached is showing that Turkey is better compared to its rivals.
In that sentiment Turkey could become EU’s largest steel producer by year-end by surpassing Germany, Dalbeler said.
Drawing attention that shipments to South East Asian markets notably supported Turkish mills’ exports, amid China’s performance in the first quarter of the year as a result of the coronavirus pandemic, Dalbeler also said he is expecting the rise in exports to that region to continue in the coming years.
Turkish mills’ rebar exports to that region especially increased notably. According to the latest Turkish Statistical Institute (TUIK) data observed by S&P Global Platts, Singapore became one of Turkey’s main rebar export markets in the first eight months of 2020, taking 235,700 mt, while Turkish mills’ rebar exports to Hong Kong totaled 207,000 mt. Turkish mills also exported 52,500 mt of rebar to Malaysia in January-August.
Dalbeler also said Turkey’s natural gas reserve discovery is important for Turkey, as the country is meeting most of its raw materials and energy needs by imports.
Turkey recently discovered a large gas field in the Black Sea with as much as 405 billion cubic meters, as Platts has reported.
The CEO of Colakoglu however also noted that the rise in exchange rates has a negative impact on Turkish steel producers, as they are dependent on raw material imports like iron ore and scrap. Having stability in exchange rates is very important when it comes to forward planning, he said.
— Cenk Can

Italian construction performance improves
Italian construction sector output increased in August, growing by 12.9% year-on-year, according to a National Institute of Statistics (Istat) report monitored by Kallanish.
This positive result confirms the upward trend registered since May and follows the lower output seen during the Covid-19 lockdown.
From June to August construction output skyrocketed by 70.8% compared with the previous three-month period. This is due to the complete halt of activity during lockdown, Istat says. In January-August construction output also increased by 12.8% y-o-y.
Meanwhile, the country’s industrial production increased by 7.7% month-on-month in August and by 34.6% in June-August compared to the previous three months, Istat adds.

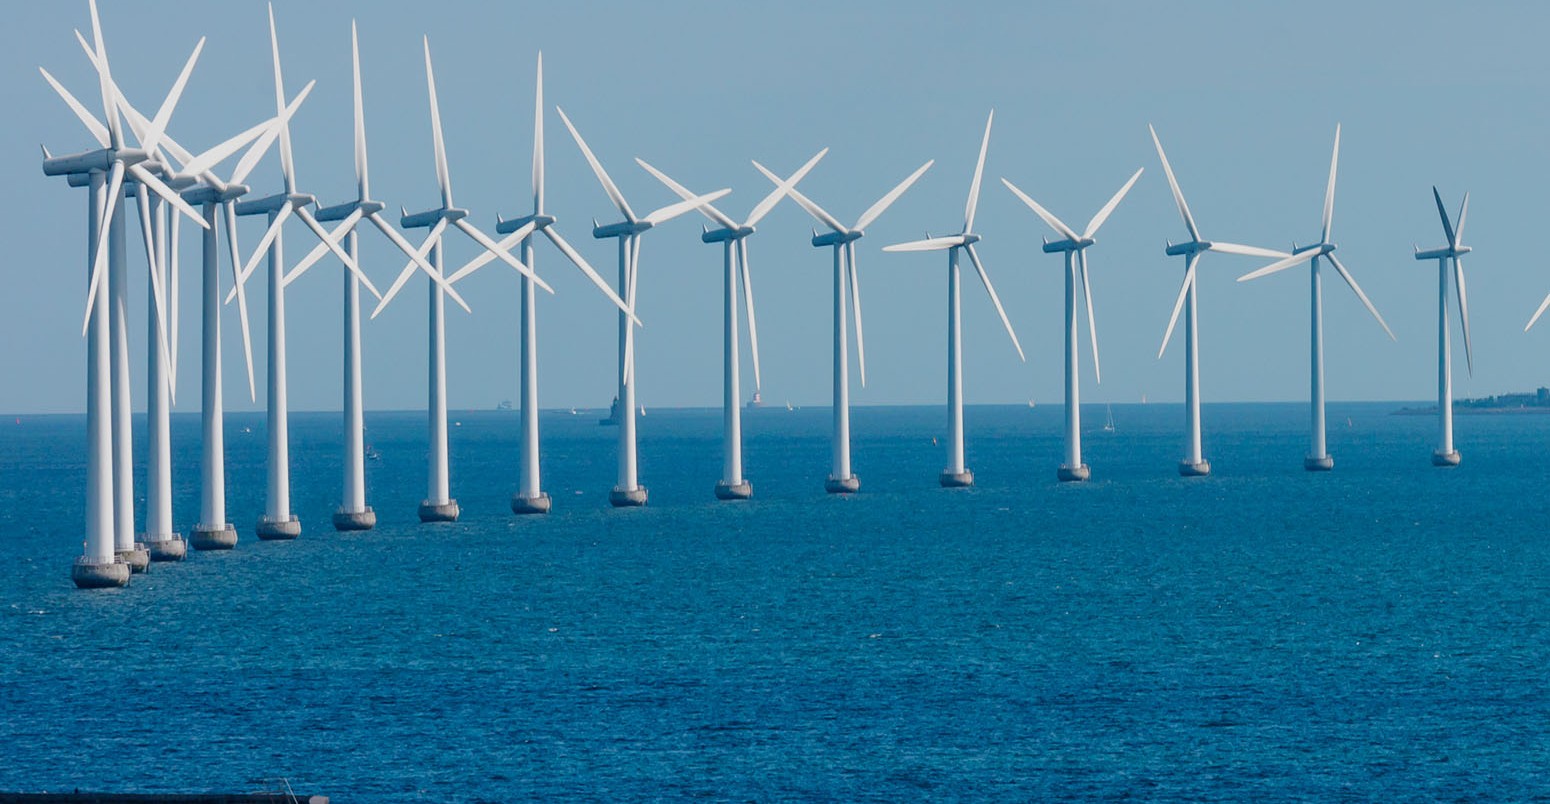
Dillinger plate supplies world’s largest offshore wind farm

Now that the final wind turbine has been installed at Hornsea One, the world’s largest offshore wind farm is about to be commissioned. Dillinger Hütte has supplied 99,000 tonnes of heavy plate for the monopile foundation structures.
Hornsea One is the first wind farm in the world with a capacity of more than 1GW, Kallanish hears from operator company Ørsted. It generates enough wind power annually to supply well over 1 million homes in the UK with green electricity.
Located 120km off the east coast of the UK, Hornsea One is further from the mainland than any other offshore wind farm completed to date. The park contains a total of 174 7MW wind turbines and covers an area of 407 km2. The towers have a height of 190 metres, with rotor blades that are 75m long, and a rotor diameter of 154m.
The thermomechanically rolled heavy plate ranges from 30-90mm in thickness.

New e-commerce platform targets excess tonnage trading
A new e-commerce venture targeting excess steel capacities that have accrued during the Covid-19 pandemic has been established in Berlin under the name of Vanilla Steel.
The company targets steel producers and processors in Europe that generate excess material and are looking to sell, it says in an announcement sent to Kallanish. It notes that “…excess material has no price tag attached by definition,” and that Vanilla Steel helps suppliers to find a fair market price through online auctions.
The firm provides the details of the winning bidders to the suppliers and the transaction is finalised directly between the supplier and buyer on the pre-agreed terms, the founders say.
“Steel suppliers are under pressure to reinvent themselves in a market full of uncertainty with low demand,” says Alexis Ducros, one of the co-founders. “Covid-19 has accelerated the need for digital sales channels for steel that reduce the cost of selling as well as the cost of inventory.”
The company was launched officially in June, had transactions from the first week onwards and now counts suppliers and buyers across 20 countries in Europe, the statement claims. It highlights that most other online shops belong either to producers or distributors, and that Vanilla Steel is positioned as the only independent digital platform for the European steel sector.
The largest previous independent e-commerce platforms for steel established in Germany, Mapudo and Netzwerk Stahl, later renamed steel.shop, both folded in spring 2019.
Eurofer welcomes investigation into Chinese wind tower imports
European steelmakers association Eurofer has welcomed the initiation this week of an investigation by the European Commission into the possible dumping of wind towers from China.
Wind towers are mainly built with steel and Eurofer believes this new investigation shows that “…steel-using sectors also need adequate trade remedies”.
In a note seen by Kallanish, the association explains that wind plate and electrical steels are among the most used steel products to produce wind towers. Imports of these products from China are already subject to anti-dumping measures. For that reason, measures on imports of downstream finished products are welcomed by the association.
“Maintaining and developing the steel-based industrial value chain in Europe is key to both the survival and sustainability of the European steel industry, but also of the sectors downstream of it,” says Axel Eggert, director general of Eurofer.
According to European rules, provisional measures on Chinese wind towers could be imposed by June next year.

Global steel groups urge the Global Forum on Steel Excess Capacity to expand efforts to address growing steel crisis
- Steel industry associations in the Americas, Europe, Asia and Africa today renewed their call for governments of steel-producing economies to intensify their work in the Global Forum on Steel Excess Capacity (GFSEC).
- The scale and persistence of excess capacity in the steel industry calls for more ambition in the transparency and policy-related work of the GFSEC
- The steel associations also call on non-participating governments to resume active participation in the GFSEC’s work.
Worldwide, October 22, 2020 – Steel industry associations in the Americas, Europe, Asia and Africa today renewed their call for governments of steel-producing economies to intensify their work in the Global Forum on Steel Excess Capacity (GFSEC).
Steel industries throughout the world expressed tremendous concern about the recent increase in steel overcapacity at a time when steel demand is severely depressed by the COVID-19 pandemic, reversing a trend of gradual decreases in overcapacity in the three years after the GFSEC was established (2016 – 2019).
The associations noted the uneven state of recovery in macro-economic conditions and steel production across the world and are particularly concerned about a risk of potential destabilisation of international steel markets.
Steel industries commend the commitments taken by the members of the steel forum to create transparency in regional market and capacity evolutions and review capacity increases based on the agreed policy principles and recommendations set out in the Berlin Ministerial report.
However, the scale and persistence of excess capacity in the steel industry calls for more ambition in the transparency and policy-related work of the GFSEC.
The steel associations specifically call on participating governments of the forum to:
- Develop stronger disciplines on industrial subsidies and other support measures that contribute to excess capacity and distort markets;
- Uphold effective trade remedies to ensure a level playing field driven by market forces and fair trade;
- Deepen the analysis of the drivers of steel capacity expansions to expose subsidised or non-market driven investments;
- Make a reliable forecast for steel demand in the markets where investments are to be made;
- Add value to the transparency work by developing open communication and information to the public; and
- Communicate to G20 Leaders on the need for expanded efforts to address the growing steel excess capacity crisis.
The steel associations also call on non-participating governments to resume active participation in the GFSEC’s work. Effectively addressing the global steel crisis is in the interest of all economies, steel producers, and steel consumers worldwide, and requires the active engagement of all G20 economies.
Contacts for more information around the world:
AISI – Lisa Harrison, lharrison@steel.org, 202.452.7115
EUROFER – Charles de Lusignan, charles@eurofer.eu, 0032 2738 79 35
CSPA – Catherine Cobden, c.cobden@canadiansteel.ca, 613.238.6049
CANACERO – Salvador Quesada, squesada@canacero.mx, 52 (55) 5448-8162
SMA – Annie Stefanec, stefanec@steelnet.org, 202.296.1515
Alacero – Fernanda Valente, fevalente@alacero.org, (55 11) 3195-5803
Brazil Steel Institute – Débora Oliveira, debora.oliveira@acobrasil.org.br, 55 (21) 3445-6327 | 6300
JISF – Shigeru Hagiuda, hagiuda@jisf.or.jp, 81 3 3669 4835
Russian Steel – Alexey Sentyurin, senturin@russtal.ru 79 153226225
Turkish Steel Producers Association – Veysel Yayan, veyselyayan@celik.org.tr, 90 3124663734
ESTA – François Michalet, francois.michalet@esta-tube.com, 33 1 41 31 56 43
AMME – Alisher Zholdybayev, zholdybayev@agmp.kz, 87029141261
SAISI – Charles Dednam, charles@saisi.org, 27 12 380 0900
KOSA – Taekyung Koh, taekyung.koh@ekosa.or.kr, 82 2-559-3546
Ukrmetalurgprom – Oleksandr Kalenkov, office@ukrmetprom.org, 38 (044) 279 05 25
SSINA – Larry Lasoff, LLasoff@kelleydrye.com, 202.342.8530
CPTI – Tamara Browne, tbrowne@schagrinassociates.com, 202.223.1700
CFSBI – Casey P. Bouton , cbouton@taubensee.com, 800-459-5101
SEIFSA – Michael Ade, michael.ade@seifsa.co.za, 011 298 9432
Acero Argentino – Carlos A. Vaccaro, c.vaccaro@acero.org.ar, (5411) 4311-6368 / 637