

Short supply hampers Italian service centre sales
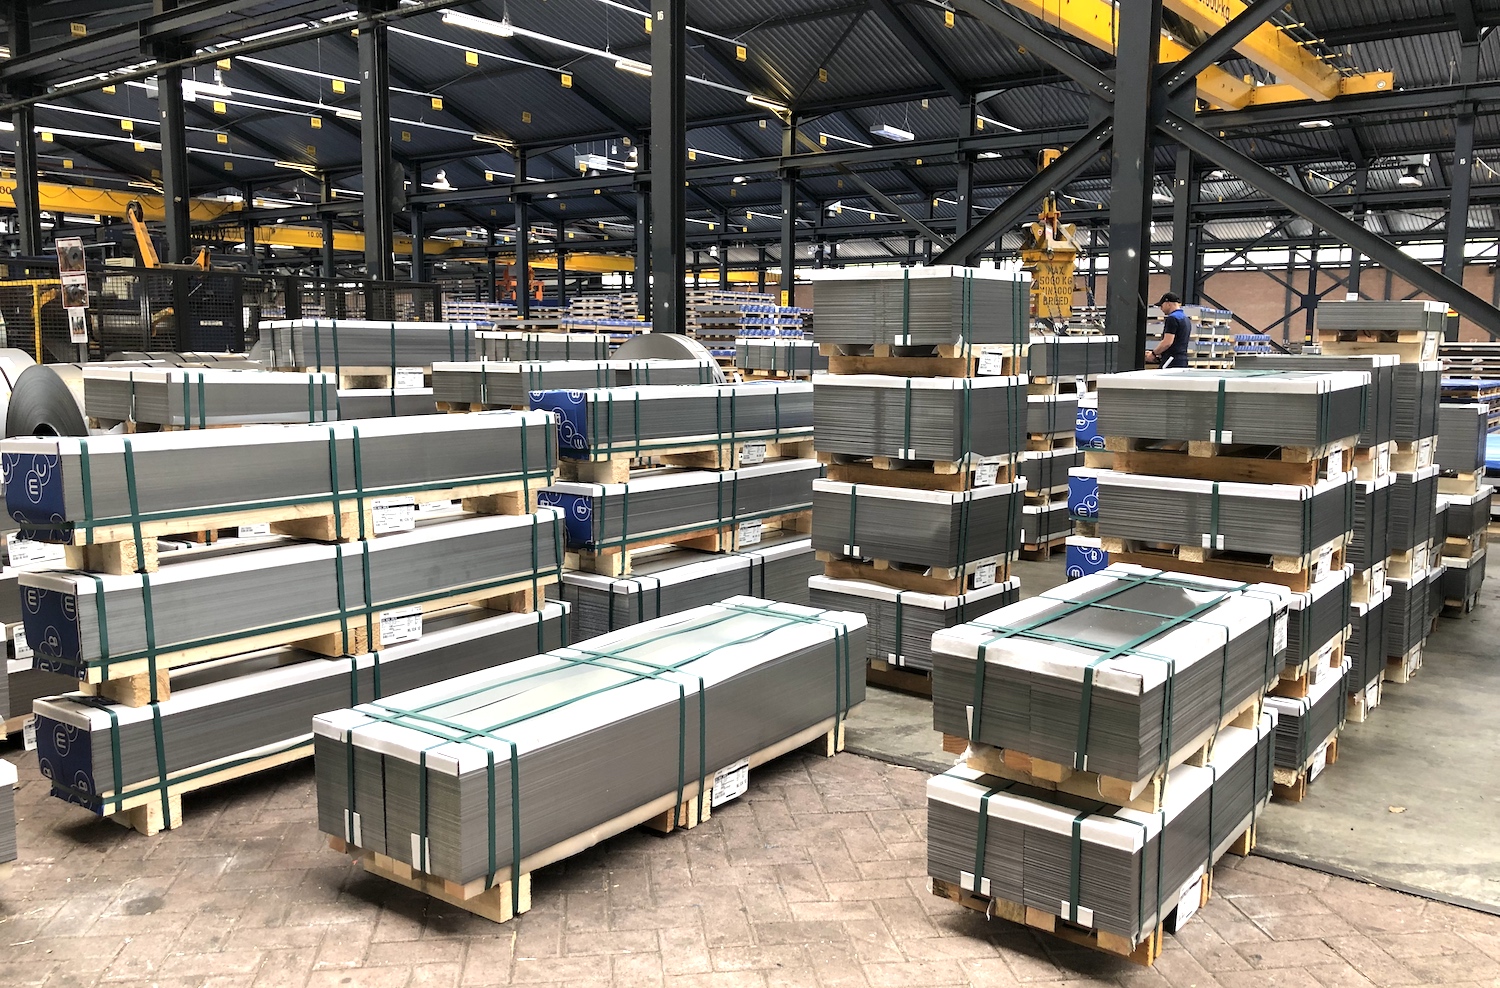
While Italian coil prices are fast increasing, service centres are sometimes struggling to pass on the steep hikes to end-users and contractors.
Demand is booming. Since September, the automotive industry has been ordering at pre-Covid-19-pandemic levels, the appliances sector is also responsible for high demand and service centre order books are filled until February.
Cold rolled and hot-dipped galvanised coil producers are filling February order books, while hot rolled coil makers have completed January order books. However, the more prices increase, the more buyers resist due to the difficulties they are having in passing on further hikes to their customers.
At the same time, the frenzy of price hikes is not forecast to stop as the country is suffering from a systemically short supply of coil, with no imports available. As the increases are happening too quickly, some customers are putting off purchasing, and risk being left without any material to sell.
Some flat product prices are not yet following the increases of HRC. Price increases are needed and expected for coated sheet, which is still at €560-570/tonne base ex-works. With HRC at €500/t base ex-works, this level is no longer sustainable. Producers tells Kallanish they intend to push up values for this product to €600/t ($710) base ex-works.
With no imports, ArcelorMittal Italia producing at minimum levels and still not taking orders for HRC, and Arvedi’s output reduced, the entire supply chain remains disrupted in the country. Business opportunities are being missed because of the lack of material, Kallanish notes.
Domestic CRC and HDG are at between €580-600/t base ex-works, while HRC is at €500/t base ex-works, sources suggest.

RCEP to promote tariff reduction on steel imports
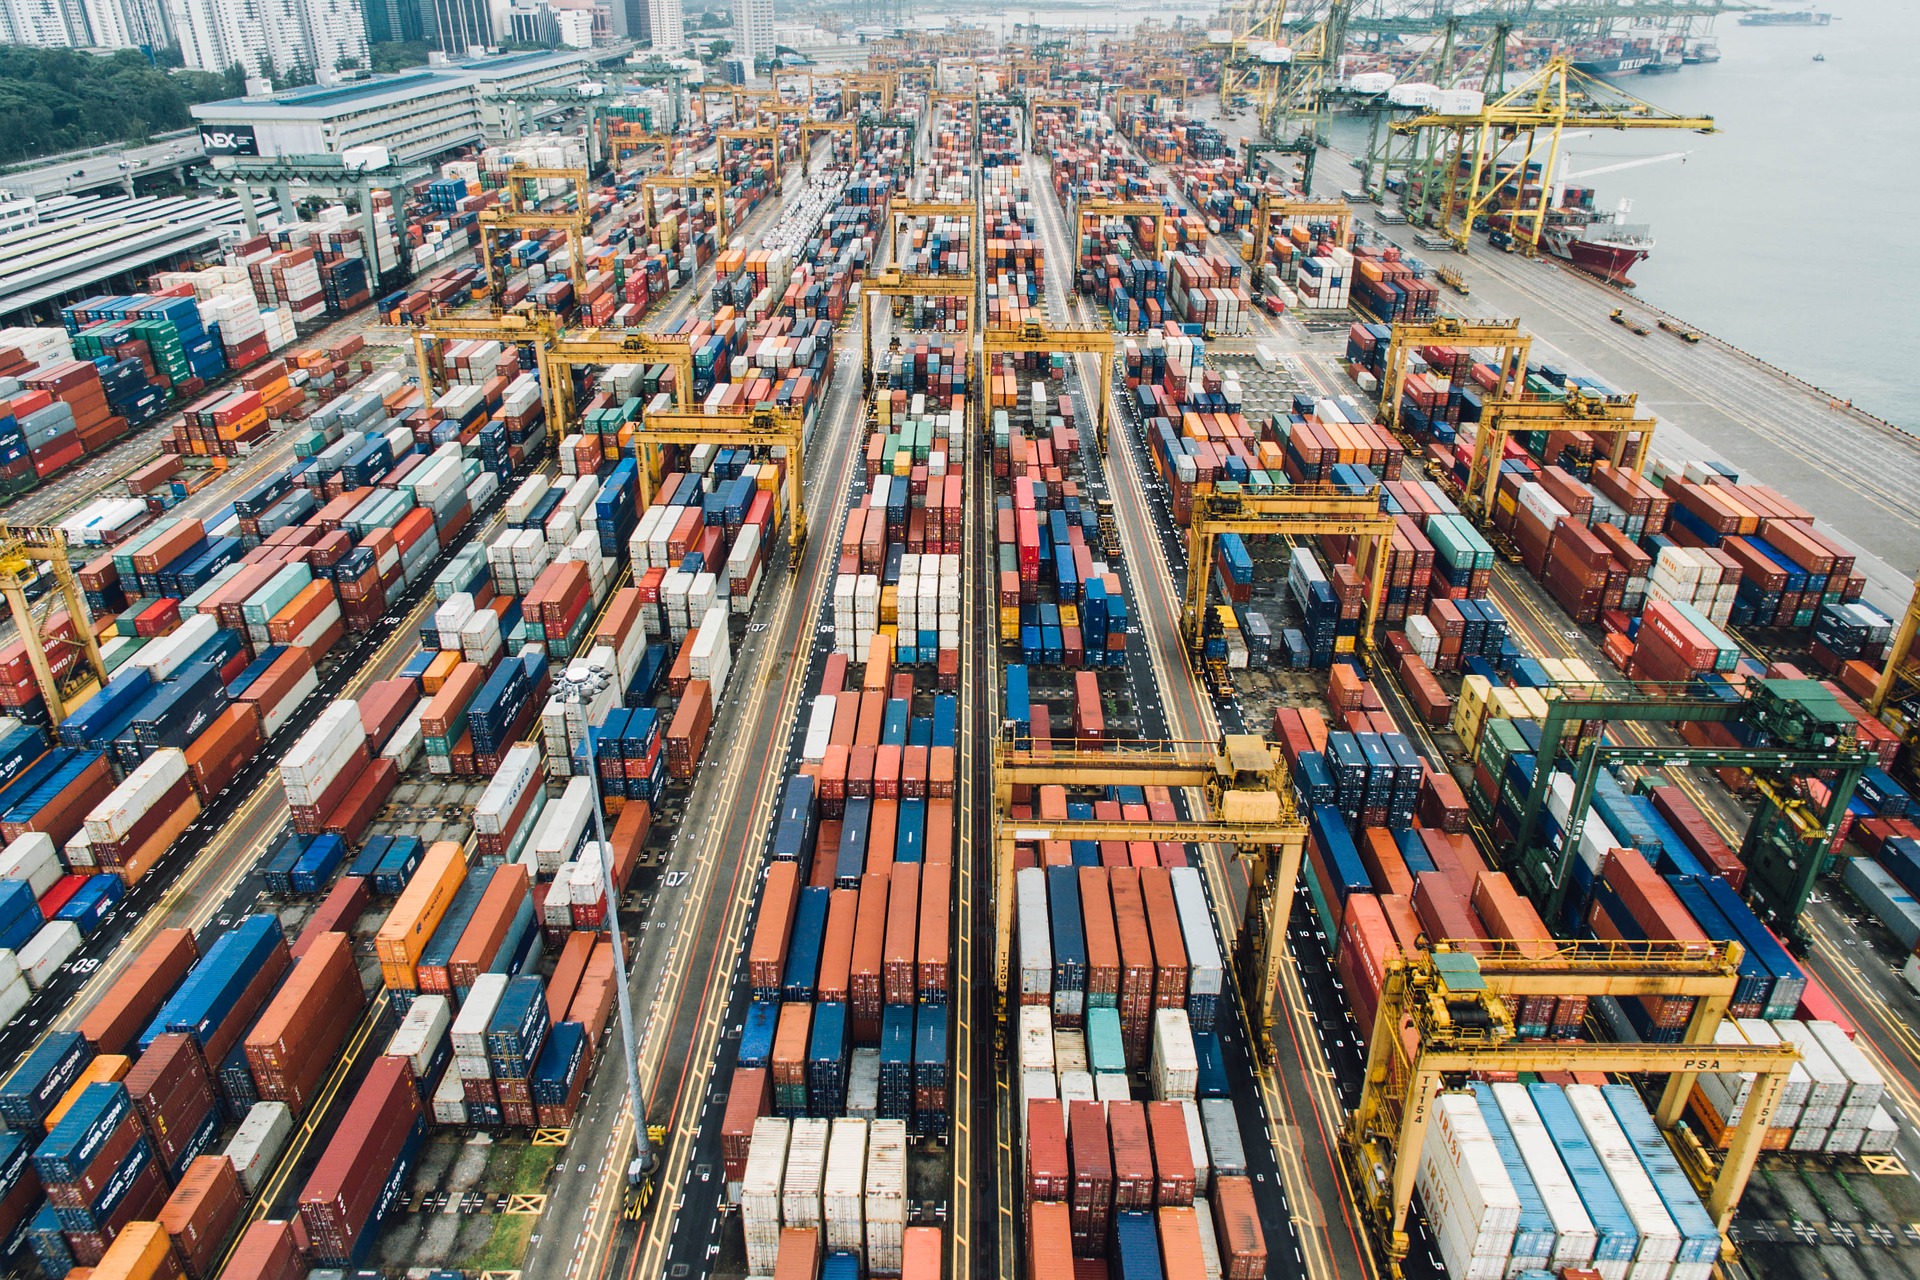
The Regional Comprehensive Economic Partnership (RCEP) is expected to promote free trade between member states, especially to reduce trade barriers by cutting tariffs on goods, Kallanish notes.
The pact was signed by 15 governments via video conference on 15 November.
Besides the ten ASEAN countries, China, Japan, South Korea, Australia and New Zealand also signed the agreement. India withdrew from negotiations in 2019, in part over concerns over reduced steel import tariffs. Market analysts have commented that the influence of RCEP could reach the level of the North American Free Trade Area or the EU Customs Union.
China Futures Daily pointed out that after the RCEP takes effect, more than 90% of goods will avoid tariff collection in trade between these countries. In future, this may increase to 95%. The zero-tariff policy will be achieved once agreements are finalised for specific products, and some should reach zero tariffs over the following ten years.
Under this framework, China and Japan could reach bilateral tariff reductions for the first time. For Japan, almost 90% of auto parts shipped to China will become tariff-free. Tariffs on gasoline engine parts as well as some steel products will be dropped when the agreement takes effect, Nikkei Asia said. As for Japan’s exports to South Korea, 92% of goods will be waived from duties, up from the current 19%.
South Korea will also now benefit from greater access to Japanese and Chinese markets. China already has a free trade agreement with ASEAN, but imports from the other signatories and exports to those countries will become tariff-free once the tariff schedules are finalised.
However, local petrochemical and steel industry professionals in Taiwan are worried that the local industry will be hit because Taiwan will be marginalized by the RCEP countries. The Taiwan Screw Industry Association said the exchange rate would have to be devalued by 15% to compensate for the potential impact of the agreement.
The sections on rules of origin could also support local crude steel producers. Before RCEP, each country and region had its own specific rules of origin, but RCEP institutes a single set of rules. For steel, products are deemed local if at least 40% of the value of the product was locally produced. This means, for example, that cold rolled coil produced from RCEP-member hot rolled coil could qualify for reduced tariffs, while that rolled from externally-sourced HRC may not.

Voestalpine sees digital sales channels booming
The High Performance Metals division of voestalpine has significantly increased sales via its online shop, and is preparing a smartphone application to further enhance digital business.
The trend was fuelled by the coronavirus crisis and related restrictions. At the Swedish distribution subsidiary Uddeholm, online sales more than doubled between February and August. “There are many suppliers on the market for standard products such as precision flat steel, but hardly anyone who also offers machined material online,” says Wolfgang Friedl, head of e-commerce in the Value Added Services division.
Products include conventional flat and round steel and custom-made products for customers. So-called “shelf” products such as powder for 3D printing, welding rods, precision flat steel or erosion blocks are also sold over the virtual counter.
Voestalpine will soon offer an app which will proactively inform about the status of the order by means of push notifications, including document downloads. Under development is also a new service module using artificial intelligence, Kallanish notes.

Celsa Huta Ostrowiec acquires fabricator

Celsa’s Polish unit, Huta Ostrowiec, has acquired Polish steel fabricator Stal-Service from construction company Porr.
Stal-Service, based on the northern outskirts of Warsaw, can produce up to 90,000 tonnes/year of construction reinforcement and 10,000 t/y of prefabricated construction elements. It sells mainly to the domestic market, as well as to Sweden, Norway and Czech Republic, Kallanish notes.
Huta Ostrowiec produces rebar, merchant bar, special bar quality and profiles. It supplies some of Poland’s largest steel distributors, including Konsorcjum Stali and Bowim.

Eurofer welcomes Turkish-origin HRC imports registration
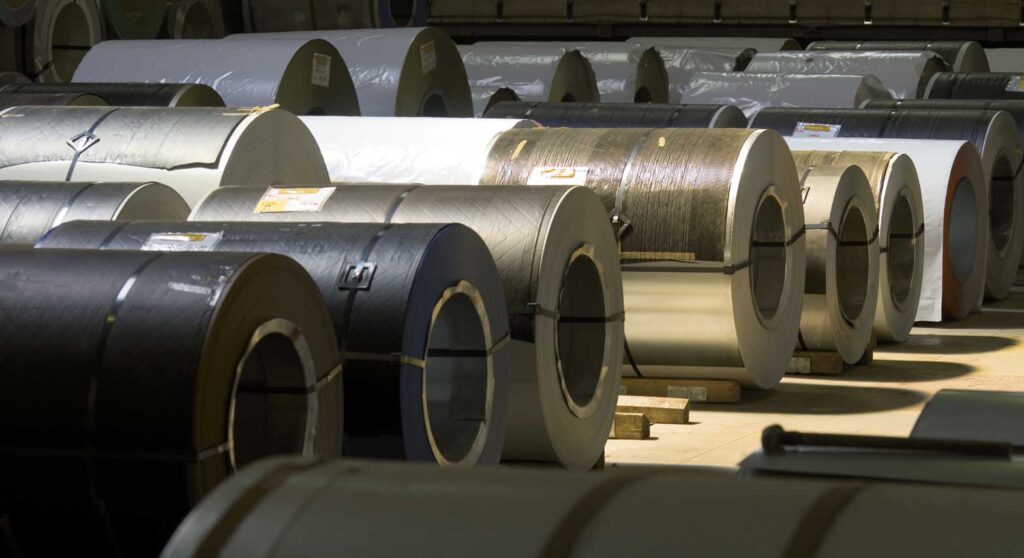
European steelmakers’ association Eurofer has welcomed the confirmation that EU hot rolled coil imports from Turkey will be subject to registration, with the investigation over potential anti-dumping duties still ongoing.
“Given the rules laid down in the basic trade defence regulation, the registration of imports is a condition for retroactive application of anti-dumping of possible provisional duties in January,” Eurofer tells Kallanish.
“The registration helps avoid opportunistic import surges ahead of the imposition of later duties,” it continues. “Practically, any imports entering the EU from Turkey as of 14 November 2020 could be subject to anti-dumping duties in the future.” The measure is a good tool to tackle the slowness of investigations on the continent, it adds.
The registration process was formally requested by Eurofer in September and has become active as of the end of last week. Provisional measures could be imposed by mid-January.
According to Eurofer data, Turkish-origin HRC imports this year could surpass 2.1 million tonnes, down almost 700,000t from the peak registered in 2018. Import activity from Turkey was impacted by both the ongoing investigation and the reduction in demand caused by the pandemic in Europe.
Tata separates Dutch unit, discusses sale to SSAB
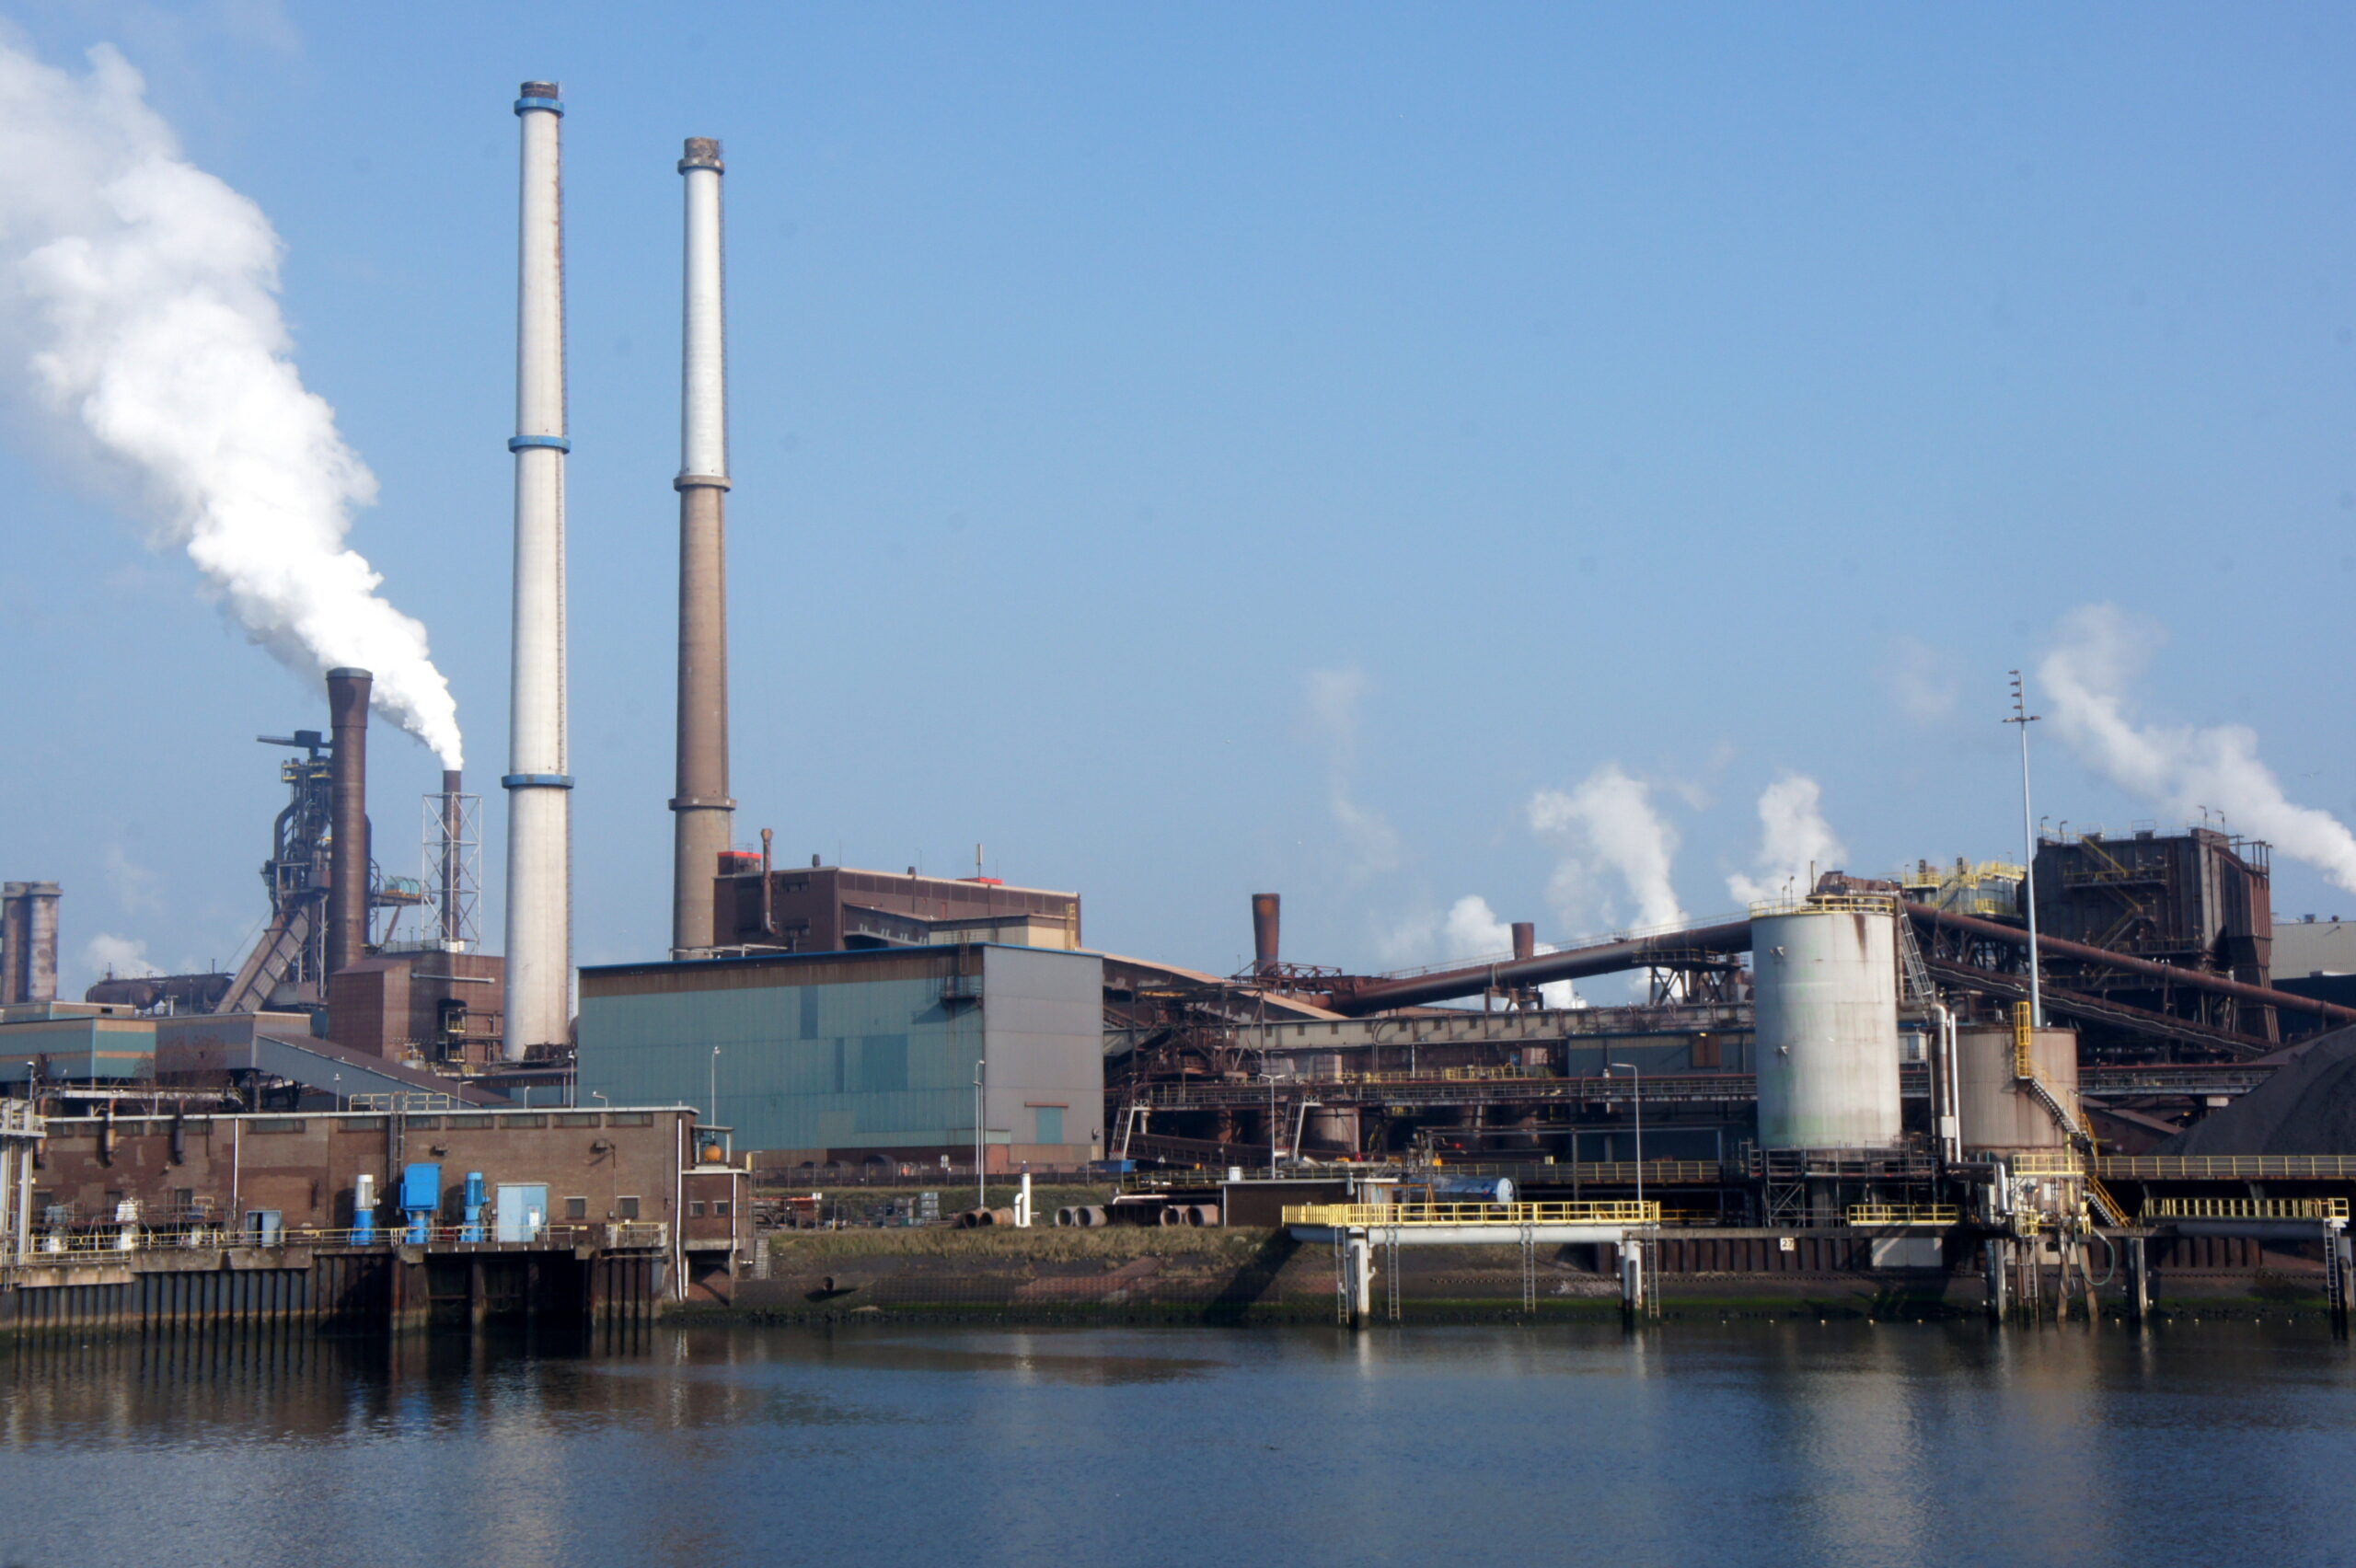
Tata Steel confirms it is in talks with Sweden’s SSAB over the potential sale of its unit in the Netherlands.
Group management is in talks with the supervisory board and management of Tata Steel Netherlands, and the process will move to the next stage including due diligence and stakeholders’ consultations, it says. Proceeds of any strategic restructuring will be deployed towards additional deleveraging of the balance sheet, it adds.
“The company has initiated the process to separate Tata Steel Netherlands and Tata Steel UK and will pursue separate strategic paths for the Netherlands and UK business in the future,” Tata Steel says in a note seen by Kallanish.
The steelmaking group adds that it continues talks with the UK government on potential measures to “…safeguard the long-term future” of Tata Steel UK. It is “…also reviewing all options to make the business self-sustaining without the need for any funding support from Tata Steel India in the future.”
SSAB says it “…has participated in several different discussions concerning consolidations in the European steel industry. The discussions with Tata are on-going but no decisions have been made. There can be no certainty that any transaction will materialize, nor as to the terms of any such potential transaction. Further announcement will be made in due course.”
Rumours about the future of Tata Steel Europe assets have circulated the market for many years. Last year the European Commission blocked the proposed merger between Tata Steel Europe and thyssenkrupp’s steel unit on competition concerns. However, observers agreed the next European steel industry consolidation move would involve Tata Steel and its strategic Ijmuiden site. This has two blast furnaces and is capable of producing some 7.5 million tonnes/year of coil.
If SSAB reaches an agreement to include Tata Steel Netherlands in its group, it will represent a significant further increase to its capacity after its acquisition of Finland’s Rautaruukki in 2014.