


S&OP Planning and Synchronization
Innovative intelligent production and supply chain planning enables to be flexible and competitive in the dynamic markets.
Realtime Technologies Synchronization module optimizes the interactive planning and control of performance, starting from S&OP planning to the optimization of production and the supply chain. All relevant real data is processed in real time, the technology maps the reality of the next hours, days and weeks in a Digital Twin. This creates transparency about service production, capacity utilization and enables synchronous control of material and resources.

China’s EAF capacity seen slowing after reaching 196 million mt/year
China’s electric arc furnace, or EAF, steelmaking capacity will increase by 14.3 million mt/year in 2021 to about 196 million mt/year, accounting for 15% of China’s total crude steel capacity, according to S&P Global Platts Analytics.
However, the growth of EAF capacity will slow down in 2022-2023, as tight scrap supply and expensive electricity will continue to undermine EAF steel’s profitability.
The net increase of China’s EAF steelmaking capacity will be just 6.1 million mt/year in total over 2022-2023, according to Platts.
Tight scrap supply
Although China has restarted scrap imports since the start of 2021, the market consensus is that the total scrap import volume in 2021 is unlikely to surpass 5 million mt/year, as recovered global demand has pushed up overseas scrap prices.
Meanwhile, according to China Association of Metal Scrap Utilization, China’s domestic scrap supply is likely to increase to 270 million mt in 2021, up by 20 million mt from 2020, accelerating from about 10 million mt increase in 2020 from 2019.
Although the imported and domestic scrap supply may increase by as much as 25 million mt in total in 2021, the scrap supply and demand are likely to remain in a tight balance, not only because EAF capacity is expanding, but also the scrap utilization ratio in pig iron and steel making process have been rising, in a bid to offset pig iron loss caused by China’s emissions reduction campaign.
Some market sources said some integrated mills, who use blast furnaces and converters to make pig iron and steel, increased their scrap consumption in the first quarter of 2021 by almost 60% from the level in early 2020, and 11% from early 2019. They said even if China’s pig iron production was unchanged year on year in early 2021, its crude steel output would still be a lot higher on a yearly basis.
Meanwhile, the ratio of China’s crude steel output to pig iron output increased from 1.19 in December 2020 to 1.21 in January-February 2021. This indicated scrap utilization ratio in China’s converter steel making process largely increased in early 2021 from late 2020, as EAF utilization rates were actually lower in January-February than in December due to Chinese Lunar New Year holidays.
In tandem, the Chinese domestic scrap prices increased by Yuan 370/mt, or 12%, from the end of 2020 to Yuan 3,390/mt as of March 19.
Hebei province’s Tangshan city announced on March 19 to reduce the utilization rates of most local blast furnaces and converters by 30% from March 20 till the end of 2021, in a bid to reduce pollutions emissions, causing scrap prices to fall slightly in recent days.
However, some market sources believed China’s efforts to reduce emissions will eventually lead to higher scrap consumption in pig iron and steel making process across the country, especially if the output cuts in Tangshan help to improve the Chinese steel profit margins.
Some sources said integrated mills could increase scrap utilization ratio to as high as 35% by adding scrap into blast furnaces, torpedo carts, converters and ladle furnaces, while the ratio is currently just around 15%-25%.
Expensive electricity
Besides scrap supply remaining tight for further boosting China’s EAF development, China’s expensive electricity prices have also hampered EAF development.
China’s industrial electricity prices range roughly from Yuan 0.45/kWh to Yuan 1.45/kWh, depending on the time of the day. Even at the lower end of the electricity prices, the power cost of EAF steel, consuming 100% scrap, will be Yuan 150/mt higher than that of steel made through blast furnace and converter route, according to Platts analytics.
Moreover, China’s electricity prices are likely to trend upward in the following years, driven by efforts to reduce carbon emission as well as by rising electricity demand.
China is expected to issue more policies to support EAF development in 2021-2025. But to establish a mature scrap supply chain is likely to take another two to three years, while expensive electricity will continue to hold back the development of electric arc furnaces or EAFs.
Platts believes blast furnaces and converters, with 1.05 billion mt/year pig iron and 1.09 billion mt/year crude steel capacity by end of 2021, will remain the main route to make iron and steel, while the EAF capacity, 197 million mt/year by end of 2021, a supplement.
— Analyst Jing Zhang


China continues to dominate Turkey’s stainless market as imports soar
Turkish buyers imported 69,000 mt of stainless coils in the first month of 2021, notably higher than the 52,200 mt imported in the same month the previous year, while Chinese suppliers continued to raise their shares in the Turkish stainless steel market with competitive prices.
China was Turkey’s top stainless coil supplier in January by shipping 26,600 mt with competitive prices, more than double year on year, S&P Global Platts observed from Turkish Statistical Institute (TUIK) data.
Chinese shipments of stainless coil to Turkey rose more than 50% year on year to 163,500 mt in 2020, despite Turkey’s provisional import duty decree imposed on many steel products on April 18, including stainless steel, to protect domestic production and employment in the domestic steel industry during the pandemic, as reported.
The rising trend in Turkey’s stainless steel imports could continue this year, as steel consumption in Turkey, including stainless steel, is expected to rise further this year, amid the rise in industry output with the easing of the pandemic.
Turkey’s stainless sheet imports from Turkey’s other main supplier, South Korea, also rose in January to 23,400 mt, 18% higher on year, while imports from the EU fell notably year on year.
Turkey’s sole stainless cold-rolling mill, Posco Assan TST, based in Izmit, Kocaeli near Istanbul, has production capacity of 300,000 mt/year of 0.3-3.0 mm thick stainless CRC up to 1,600 mm wide.
— Cenk Can

Suez Canal blockage may heighten price pressures in steel, metals
The Suez Canal blockage by the grounded Ever Given container ship is not expected to immediately impact steel and metals supplies worldwide, market sources said March 25. However, it is fueling expectations of eventual rises in bunker and freight rates and inventory-squeezing that could exacerbate current upwards price pressure, particularly in steel and copper, they said.
The waterway is used for shipments of steel and steelmaking raw materials including iron ore, pellets and hot-briquetted iron between the CIS and Asia, including China; aluminum semi-finished products from the Middle East to European nations and for copper shipments from Western nations to China.
“The commodity impact extends beyond oil and gas,” said Derek Langston, head of research at shipbroker SSY. “An array of dry bulk cargoes use the Suez Canal to access key markets in Asia, including grain from the Black Sea and Europe, coal and iron ore from the Black Sea, plus fertilizers from the Baltic Sea. Even coal and petroleum coke shipments from the US into India use the canal.
“Indeed, shipping schedules in the Black Sea are already being affected by the incident through delays to vessels arriving at port to load cargo, with the potential for further vessel shortages growing,” Langston said.
Oil and gold prices were higher early March 25 after the impact of the March 23 blockage became apparent, before sliding later in the day. More than 150 ships were reportedly in a queue to pass the blockage.
Steel sector wary
For steel sources, the crucial factor will be how long the blockage lasts.
“At the moment it’s hard to discern any noticeable impact on the European steel industry,” said a spokesman for the European Steel Association Eurofer. “This blockage of the Suez Canal is, whilst newsworthy, likely short term and likely to soon be resolved.”
If the issue is long-lasting it could have an effect on the European steel sector “as the market is already tight and deliveries slow,” a trader said.
The trader nonetheless expressed greater concern over potential supply disruptions currently feared from steelmakers ArcelorMittal Italia, due to a pending court ruling on its operation, and Liberty Steel due to financing issues.
S&P Global Platts assessed North European hot rolled coil prices at an all-time high of Eur830/mt ex-works Ruhr on March 25, up Eur30/mt on-day, while Southern European HRC prices went up by Eur15/mt on the day to Eur825/mt ex-works Italy.
Removal expectations
According to Platts Analytics, the Suez Canal Authority initially forecast Ever Given could be cleared March 25, but revised port agents’ estimates later put this at March 28 or 29 at the earliest.
“If traffic started again mid next week, it may take another 10 days to return to normal keeping in mind cargo cancellations and re-routing. Another issue is the work that will have to take place to repair damage caused to the canal structure, and whether it will add time to the transit throughout the canal,” an analytics report said.
SSY said a high tide is expected March 27 and this may be the best chance to free the vessel from her current grounding.
“Until this time it is premature to suggest further impact to the market, however if this high tide comes and goes and the vessel is still aground, this may cause long-term impact,” the broker said.
A spokesman for steelmaker Qatar Steel estimated the delays at anywhere up to three weeks.
“Tugboats work to free 400-meter, 20,000 container capacity MV Ever Given as vessels gather at either end of the key waterway between East and West. Estimations from unofficial channels are showing the expected impact of global delays between two days to three weeks,” the spokesman said.
The blockage could potentially be impacting a total of 55,000 TEU of cargo from Asia to Europe daily, assuming that vessels are fully-laden due to current high market demand, he said.
“The current expectation is that it will take some 2 days to clear the canal which will cause the delay of 110,000 TEU of cargo – which will cause a spike of cargo into the main ports in Europe as this will now arrive at the same time as cargo arriving normally a few days later. In other words, this increases the risk we will see port congestion in European ports one week from now.”
Global shipping could be impacted if the problem persists, as “the next best way to get between Asia and Europe is around the entire continent of Africa, almost 9000 km more and two weeks longer lead time,” the Qatar Steel spokesman said.
Freight rates
Marine fuel prices had reached their highest levels since January 2020 at the time of the Ever Given incident, with the Suez Canal having seen comparatively higher traffic in recent weeks, Platts Analytics said.
Analytics sees that shipowners are not in a position yet to command a higher freight rate for new fixtures due to the uncertainty of when the vessel will be cleared to transit normally through the Suez Canal.
However, “we would expect to see over the next couple of weeks rates spiking before calming down again once the backlog is cleared. The owners will not want to miss out on these increased spot rates. Freight rates are low compared to prior years due to the ongoing COVID-19 situation. These Suez Canal delays could see rates in April and May remain higher than pre-incident freight levels,” Platts Analytics said.
— Diana Kinch, Annalisa Villa, Hector Forster, Jacqueline Holman and Filip Warwick
Suez Canal blockage spares Mid-East importers for now
The blockage of the Suez Canal by a large container ship earlier this week has so far had minimal impact on steel and raw materials trade. But there could be disruption if the vessel takes longer to re-float, Middle Eastern sources tell Kallanish.
Various Gulf Cooperation Council billet buyers say they have so far felt no impact on supply from, for example, the CIS that is transported south through the Suez Canal. One major United Arab Emirates-based buyer says its last lot purchased is already alongside at port. One major Saudi Arabian steelmaker meanwhile says its raw materials imports remain unaffected and it hopes the situation will normalise quickly.
Ship owners could however take advantage of the situation and push up freight rates, which are already at historic highs due to container shortages. This has made some intercontinental steel trade unworkable. The Baltic Dry Index, on the other hand, fell on Wednesday after the news of the Suez Canal situation.
One GCC-based mill says that although feedstock can be sourced locally, avoiding the Suez Canal blockage, steel exports in container to destinations such as Africa have been made unworkable. This is due to costly freight and container shortages. Last month a GCC coil processor also said skyrocketing container freight rates were making its export business difficult.
The jury remains out on how long the blockage will last. In 2017 a Japanese container ship that ran aground was re-floated within hours. At press deadline on Thursday the Suez Canal Authority was still working on re-floating the vessel and navigation through the Suez Canal was suspended. 13 north-bound vessels have dropped anchor in the Bitter Lakes waiting area until navigation can be resumed.
The authority’s crisis management committee held a meeting on Thursday with Dutch salvage firm SMIT to discuss ways to re-float the ship. It was decided to carry out dredging works around the ship’s perimeter.
Adam Smith Germany


Industry has decarbonisation technology, needs policy support: Primetals
The technology required for steelmaking decarbonisation is already available, but policy support is needed to make the transition economical, says Primetals head of sales direct reduction Christian Böhm. Moreover, a potential lack of feedstock for direct reduced iron production could pose a problem after 2030.
In order for hydrogen steelmaking to be successful, an economical supply of “green/yellow” electrical power and hydrogen is required. This means electricity costing $0.02-0.03 cents per kWh and hydrogen at $1-2 per kg. Prices must become competitive versus natural gas, according to Böhm.
There also has to be adequate iron ore feedstock supply. DRI-electric arc furnace route producers require high-grade materials, which may be in short supply following the expected commissioning of substantial new DRI capacity in the coming years.
There should be sufficient iron ore fines and DR-grade pellet availability until 2030. “But what comes after, it’s a crystal ball, we can only guess; but based on the number of direct reduction facilities and electric arc furnaces proposed, it will surely be a problem,” Böhm said at this week’s International Iron Metallics Conference 2021 attended by Kallanish.
The transition will be gradual and done in steps. This will first see the optimisation of existing plants, followed by the transition phase and then the final “green” steel phase. It will take time to change the mindset of people, Böhm pointed out. Moreover, carbon emissions need to be made costly to incentive this transition.
Around two thirds of global steelmaking is done through the basic oxygen furnace route. This route will still account for 55% of steelmaking in 2050, Böhm suggested. It is unlikely the world will achieve zero carbon per tonne of liquid steel by 2050, “but at least we will be very close”, he commented. The final phase will see a 70-80% CO2 reduction versus today.
“Technology is not the point, it’s the economics. We need the framework conditions to have these technologies being applied,” Böhm concluded.
Adam Smith Germany
Ore-based metallics demand to continue growing: IMH
The availability of merchant pig iron in the global market is driving the reduction of CO2 emissions, as it supports one of the most ecologically friendly steelmaking routes, the electric arc furnace, says Industrial Metallurgical Holding (IMH) vice president Sergey Frolov.
China is set to continue raising its EAF capacity, indicating pig iron, HBI/DRI and other metallics supply issues in the future. To offset the high content of residual elements and impurities in ferrous scrap used in EAFs, higher volumes of virgin metallics will be needed, both to increase quality of steel and to reduce pollution, he said at this week’s International Iron Metallics Conference 2021 attended by Kallanish.
The demand outlook for merchant pig iron and other metallics therefore remains positive. WSD forecasts 2 billion tonnes of steel to be produced globally by 2025, with the biggest share of it made by EAFs. The share is expected to increase from 29% in 2019 to 53% in 2070 amid the ongoing reduction of carbon footprint and other pollution.
IMH significantly increased its pig iron exports to China in 2020, a trend that started in mid-2019. The firm exported 58% of all its pig iron to Asia in 2020, up from just 9% in 2019 and 2018. The US reduced its intake from 56% in 2019 to 19% in 2020. Turkey took a 10% share, down from 15% in 2019, and the EU took 11%, down from 19% in 2019.
The EAF route produces four times less carbon per tonne of steel compared to BOF-based production, Frolov said. In the last five years, in line with the US and EU, China has been increasing its share of environment-friendly steelmaking technologies, raising the share of EAFs from 6% in 2014 to 9% in 2019. This means a production of 47 million tonnes in 2015 versus an estimated 128mt in 2021. The EU’s share of EAF-produced steel rose from 39% in 2014 to 41% in 2019, Frolov noted.
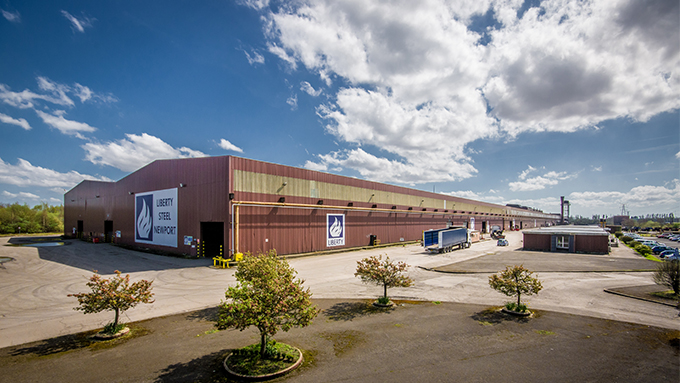
UK government mulls supporting Liberty ‘in its entirety’
Westminster is looking at supporting Liberty Steel in England and Wales “in its entirety”, UK business secretary Kwasi Kwarteng said in the House of Commons on Thursday.
Pressed by some members of parliament on how much government ministers knew about Liberty lender Greensill Capital’s financial situation before its collapse, Kwarteng said an investigation is now under way, Kallanish notes.
In terms of government intervention in Liberty, “it is not appropriate now, given where we are, to disclose anything of that kind, but of course this is an ongoing situation that we’re monitoring very closely”, the business secretary said. However, he later added that Liberty has many units spread across England and Wales and “we’re looking very closely at what specific assets, what specific jobs are necessary, and we hope to support the company in its entirety”.
Kwarteng stressed there is a future for UK steel. The government’s plans will require around 5 million tonnes of steel in the next decade, and it “absolutely a commitment of mine” to ensure the UK has a viable steel industry to support this demand, he added. He refused, however, to be draw in to revealing specifics on what commitments the government had made to ensure local content in UK projects.
In terms of uncompetitive energy prices, Kwarteng said work had been commissioned to tackle this issue and that he is in contact with the UK Chancellor to see what can be done to address this problem.
Adam Smith Germany