

Geschäftslage in der deutschen Zulieferindustrie erholt sich
Nach dem pandemiegeprägten Vorjahr war der Start in das Jahr 2021 für die gesamte Zulieferindustrie von existenzieller Bedeutung. Die Erholung der Lage – Stand Ende des ersten Quartals 2021 – spiegelt sich deutlich im Geschäftsklima der Zulieferer wider: In allen Segmenten der deutschen Zulieferindustrie hat sich die aktuelle Geschäftslage auf breiter Front verbessert. Die Dynamik ist vergleichbar mit der Erholung nach der Finanzkrise 2009. Gleichzeitig stiegen die Geschäftsaussichten für die nächsten sechs Monate. Optimistischer war die Erwartungshaltung der Zulieferer zuletzt im Februar 2011. Dennoch sind die Signale aus den Kundenbranchen extrem zwiespältig: Die Fahrzeugbauindustrie sendet aufgrund der Lieferprobleme bei Elektronikbauteilen unverändert Bremssignale aus. Die ursprünglich optimistischen Prognosen der Automobilhersteller für das Jahr 2021 dürften kaum mehr zu halten sein. In der Folge sind Prognoserevisionen auch auf Zuliefererseite erwartbar. Der Maschinenbau als zweitwichtigste Kundenbranche hat demgegenüber wieder Fahrt aufgenommen. Hier sind Aufwärtsrevisionen der ursprünglich eher konservativen Erwartungen wahrscheinlich.
Der Strukturwandel zur Dekarbonisierung der Gesellschaft ist längt auch in der Zulieferindustrie angekommen. In einem konjunkturell höchst unsicheren Umfeld müssen die zum Teil sehr mittelständischen Zulieferbetriebe teure Investitionsentscheidungen treffen. Der Klimaschutz ist ein Schlüsselthema unserer Zeit, welches mit ehrgeizigen und erreichbaren Zielen prioritär vorangetrieben werden muss. Die Zulieferindustrie bekennt sich zu den Pariser Klimazielen. Die vom Gesetzgeber gesetzten CO2 – Reduktionsziele müssen sich indes auch an der technischen Machbarkeit orientieren, das gilt u.a. auch für die Festsetzung von CO2- Grenzwerten. Der Fokus des Handelns muss von vornherein im Dialog mit den betroffenen Industrien die Umsetzung der Ziele in den einzelnen Sektoren in den Blick nehmen und die hierdurch entstehenden Folgen genau und transparent benennen. Jede politische Regelsetzung und Förderung auch in der Europäischen Union muss technologieoffen sein. Das marktwirtschaftliche Prinzip, dass sich zur Erreichung der politischen Ziele die technisch beste Lösung im Wettbewerb der Technologien entwickeln und durchsetzen muss, führt zu Innovationen, die tatsächlich und ohne staatliche Förderung in großer Zahl zum Einsatz kommen. Staatlicher Dirigismus und Technologieverbote dagegen bergen die Gefahr, dass falsche Wege beschritten werden und zielführende Optimierungen nicht zum Zuge kommen können. Die Vorgaben der neuen Abgasnorm Euro 7 müssen sich an den technisch und wirtschaftlich erreichbaren Fortschritten orientieren. Genauso wie elektrische Antriebe können auch z.B. mit E-Fuels betriebene Verbrennungsmotoren einen wertvollen Beitrag zur Erreichung der Klimaziele leisten.
Dies gilt auch und gerade in Hinsicht auf zeitliche Festlegungen. Entwicklungsprozesse können unerwartet schnelle Fortschritte machen oder Hemmnissen und Verzögerungen ausgesetzt sein. Es ist nicht verantwortlich, in der Hoffnung auf neu entstehende Arbeitsplätze in der Zukunft sichere bestehende Arbeitsplätze im industriellen Mittelstand akut zu gefährden. Daher ist ein Monitoring bei der Zielerreichung der Klimaziele inklusive der durch die Umsetzung zu erwartenden Folgen wesentlich.
Die mittelständischen Zulieferbetriebe können die Transformation nicht aus eigener Kraft stemmen, sondern brauchen Unterstützung durch spezielle, auf den Mittelstand zugeschnittene Förderprogramme. CO2-Emissionen können z.B. durch eine Umstellung der Energieversorgung oder neue Produktionsverfahren gesenkt werden. Dafür müssen die notwendigen Standortbedingungen geschaffen und Ressourcen zur Verfügung gestellt werden. Der Staat sollte dafür unbürokratisch Zuschüsse bereitstellen. Die Forschung und Entwicklung entlang der gesamten Wertschöpfungskette, z.B. in den Bereichen Mobilität, grünem Wasserstoff und alternative Kraftstoffe, muss konsequent fortgeführt werden. Schlüsseltechnologien, z.B. in der Antriebstechnologie, der Materialforschung, der Mikroelektronik, der Leistungselektronik, der Batterietechnologie und der Vernetzung und Digitalisierung im Fahrzeug, müssen weiterentwickelt werden. Schließlich geht es um über 1 Million Beschäftigte in rd. 9.000 Betreiben.
Quelle: ArGeZ
12.04.2021 von Hubert Hunscheidt

Carbon tax could be EU protectionism, says TCUD
Turkish Steel Producers’ Association (TCUD) general secretary Veysel Yayan says the EU imposing a carbon border tax while allocating free carbon emissions to steelmakers will not serve the bloc’s EU’s “green” steel and decarbonisation targets.
“On the contrary, it will create the impression that it is another way of implementing protectionist measures,” Yayan said at Friday’s International Steel Symposium 2021. “In this respect, the EU should be very careful not to destroy its prestige and green deal target, which, we sincerely support.”
Yayan says the Turkish steel industry’s carbon emissions are much lower, at 280kg per tonne, compared to the EU. This is given that 70% of Turkish steel production is based on electric arc furnaces, while in the EU EAF share is only 40%.
“Turkish steel should not be subject to a carbon tax as we are already producing greener steel compared to the EU,” said Yayan at the event attended by Kallanish.
The Turkish steel industry has already lowered carbon emission by 20% in the last ten years, and it is getting harder to further decrease this rate. “The zero carbon target is not very realistic for the steel industry, but we will do our best in this respect,” Yayan said.
Renewable energy takes a 60% share in Turkey’s total energy consumption, while wind power’s share is 10%. Regarding solar energy, there are numerous new projects.
Yayan says Turkish mills have to pay additional taxes for environmental measures, rather than receiving government support like in the EU. “While the situation is so, we strongly believe that the carbon tax on EU imports will not serve the EU’s green steel targets,” he explained. “This will be considered in most of countries as another way of implementing protectionist measures. The EU is already ignoring the free trade agreement between us through various safeguard measures.”
“Although we support decarbonisation, this should not pose an obstacle to trade,” Yayan concluded.
Burcak Alpman Turkey


Carbon emissions prices to remain elevated: Czech association
Prices of EU carbon emissions are unlikely to retreat again following their recent surge, as the forthcoming EU Emissions Trading System (ETS) revision will tighten the market to better reflect the EU’s climate ambitions. So says Czech and Slovak steel association Steel Union chairman Daniel Urban.
Over the last two years carbon emissions allowances have soared from around €10/tonne of CO2 to €40/t ($48). Steelmakers are no longer receiving free allocations and need to buy allowances from the market.
The production of one tonne of steel produces about 2 tonnes of CO2, with the main source being coke, which is used as a reducing agent for iron ore. There is presently no other technology for producing steel from iron ore that works technically and economically on the required scale, Urban says in a note on the association website seen by Kallanish.
“The steel industry is a global industry,” Urban says. “We cannot pass on climate costs to our sales prices, because our steel would become globally uncompetitive. So, we need a chance to compete on a fair and level field.” To address this issue, the European Commission plans to introduce a carbon border tax, although it remains unclear what this will look like, and if it will be effective or compatible with WTO rules, he adds.
“In the next two or three years, it will be decided whether Europe will maintain its own industrial base,” Urban continues. “Of course, demand for steel in Europe will not disappear. However, it risks being satisfied by third country producers. This would be a failure of European climate policy, because steel must be a pillar of climate neutrality and of the circular economy.”
Adam Smith Germany
Liberty Ostrava assets stay in Czech Republic: minister
Czech industry and trade minister Karel Havlíček says he has agreed with Liberty Ostrava management and trade unions that the steel plant’s assets will not be moved outside the country.
“The situation in Liberty Ostrava is becoming more complicated due to problems with the financing of the multinational parent holding GFG Alliance,” Havlicek tweeted after the meeting in Ostrava on Friday.
Liberty Ostrava said on Thursday it shipped over 550,000 tonnes of steel in the first quarter and increased production almost 20% on-year to over 600,000t (see Kallanish passim). Output in each month surpassed 200,000t, the highest monthly level since 2016. The firm also forecasts its Q1 Ebitda will increase to over €60 million ($72m), a quarterly record since it was acquired by GFG in July 2019.
Earlier in the week trade unions at Liberty Ostrava declared strike readiness in protest over the uncertainty surrounding the future of the plant’s owner, Liberty Steel. Unions said they reject the proposal to lend Ostrava’s carbon emissions allowances to Romanian sister company Liberty Galati, which is reported to be in need of €100m to purchase CO2 certificates.
Trade union OS Kovo chairman Jaroslav Souček called on Havlíček last month to intervene in the Ostrava plant amid concerns over its future.
Adam Smith Germany

Thyssenkrupp fast-tracks Acciai Speciali Terni sale
Thyssenkrupp is accelerating the sale of Italian stainless steel producer subsidiary Acciai Speciali Terni (AST). Trade unions tell Kallanish the company has started the first phase of the sale, where potential buyers will have access to some of AST’s production and sales documents, and assess its financial situation.
This phase should last 1-2 months and should enable potential buyers to make an informed offer. JP Morgan will handle the procedure and select the best candidate for the next phase.
Italian steelmaker Arvedi and Posco are rumoured to be competing for AST, while re-roller Marcegaglia has recently reiterated its interest in the steelmaker. Marcegaglia consumes around 500,000 tonnes/year of stainless steel and buys 30% of its coils from Terni, chief executive Antonio Marcegaglia confirms to Kallanish. The re-roller is able to provide a solid industrial plan based on extending industrial synergies already in place with AST, he adds.
According to rumours, another potential Chinese investor has expressed interest in the steelmaker. Last year Thyssenkrupp announced it was seeking either a partnership or a sale for its Italian subsidiary pursuing its restructuring strategy (see Kallanish passim).
Natalia Capra France
Tata Steel UK invests in tubes division
Tata Steel UK is investing in a single high-tech warehouse, and the relocation and upgrading of the rectangular hollow section processing line and the cold mill at its Corby site in the East Midlands. This will see improved efficiency and reduced energy consumption.
“We are creating a single site warehouse within the East Works, which will allow the closure of the South warehouse,” project leader Nigel Chudley says in a note seen by Kallanish. “Significant work is ongoing to prepare the ground for the installation of a racked warehouse solution. Over the last couple of weeks the team have been working with our contractors to break ground, which is the first element of a 14-week programme to prepare the flooring which will support 18,000 tonnes of finished tube product.”
The new warehousing system will bring significant advantages to the current system, enabling the tubes operation to rotate stock much more efficiently and reduce stock losses, Tata Steel UK observes.
The Corby site produces steel tube products from steel made at the Port Talbot works. Manufacturing processes on the site will now be brought closer together as part of the £25 million ($34m) scheme. This is being paid for in part with the sale of land freed up by the changes as well as savings from operational improvements.
The investment comes amid uncertainty over the future of Tata Steel in the UK, as the firm continues to seek assurances from the UK government while separating its UK and Netherlands units.
Adam Smith Germany
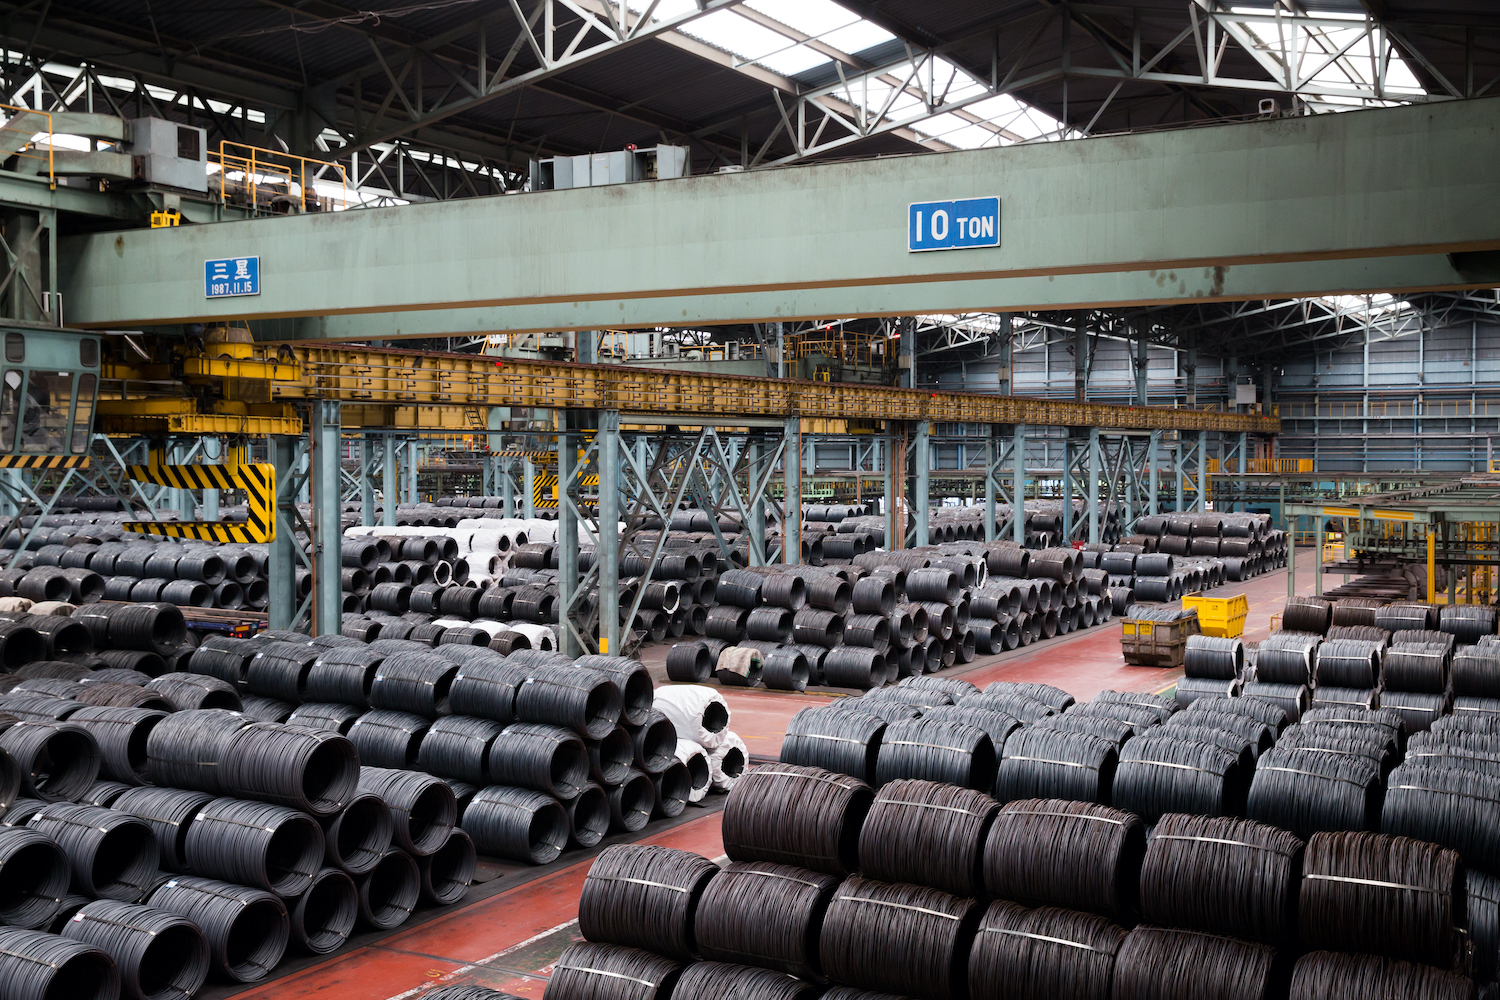
Chinese first-quarter steel demand surges over 50%
Chinese official economic data for the first quarter shows crude steel output has remained very strong despite attempts to curb production levels in Tangshan. This has been driven by the strong recovery in end user demand, which gained over 50% year-on-year in Q1, Kallanish calculates.
Chinese crude steel output in March was up 19.1% y-o-y to 94.02 million tonnes, according to the National Bureau of Statistics (NBS). This brought output over the quarter to 271.04mt, up 15.6% y-o-y.
Q1 2020 saw output constrained by the Covid-19 lockdown, but March data was also the second highest on record after August 2020. Mills were producing crude steel at an annualised rate of 1.107 billion tonnes/year. This shows steelmakers operating as close to capacity as they can, while margins have been strong.
As noted in last month’s Kallanish China Steel Intelligence, China does not yet have the policies in place to engineer a y-o-y decline in steel output.
China’s trade balance meanwhile moved in the direction of exports in March despite higher steel imports. This was in part because exporters were rushing through cargoes ahead of an anticipated change in export tax rebates. Accounting for this, China’s apparent finished steel demand was up 19.81% in March at 84.1mt, and up 15.36% over the quarter at 246.14mt.
The biggest difference between Q1 2020 and 2021 however has been in end user demand. Accounting for inventory change, implied end user demand in March was up 30.01% to 89.79mt, but over the first quarter demand was up 51.61% at 196.28mt. The increase over the quarter equates to roughly the one month of demand lost due to the lockdown in 2020.
On a daily basis, demand in March recovered both on-year and from the winter, but is in fact still slightly below the average for the second half of 2020. As the weak basis for comparison fades after Q1, China’s output and demand growth rates will also slow sharply, and could turn negative by the end of the year.

German steel haulier expands in east of country
Hergarten, which has Germany’ s largest full-service truck fleet dedicated to steel, has opened another 1,000-square-metre location in Chemnitz, in eastern Germany.
The new opening replaces a smaller warehouse location in Lichtenau near Chemnitz, which could not be expanded further and will be closed. The office staff from Lichtenau will now work in Chemnitz, and customers will retain all their previous contact persons, Kallanish hears from the company.
Hergarten is headquartered in Cologne in the west, and has nine more locations nationwide.
The Chemnitz site will handle 150 tonnes of consolidated goods per day. This includes sheet metal packages in small and medium formats or steel pipes and solid material with lengths of up to 13 metres. The material will come from the Rhineland and the Ruhr area and, after arriving in Chemnitz, remains in the warehouse for less than 24 hours before it is forwarded to customers.
The company now has total operating space of 46,000 square metres in Germany. It handles around 440,000 orders, comprising 1.1 million tonnes/year.
Christian Koehl Germany