

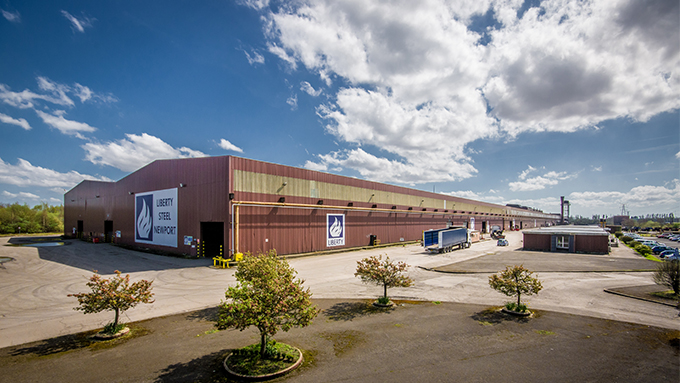
Liberty Magona to reduce production before June idling
Liberty Steel’s Italian coil re-rolling facility, La Magona, will slow production starting this week due to a shortage of hot rolled coil. In a letter sent to the economic development ministry (Mise), trade unions have asked for an urgent meeting with the government and the company, sources close to the firm tell Kallanish.
From mid-June the entire mill will be idled. The plant will consume its HRC stock until the end of the month, but it is running out and “finding HRC suppliers willing to work with a company in financial trouble is proving to be challenging”, a source comments. Most HRC suppliers are refusing to work with Liberty Steel as the company is not in the position to provide bank guarantees following the collapse of lender Greensill Capital.
Its main supplier, ArcelorMittal, is said to have “cut Liberty Magona’s lifeline” after Liberty’s Liege plant failed to pay the supplier for HRC.
Coating and galvanising lines no.1 and no.4 will stop production at Magona. Galvanising line no. 5 and coating line no. 2 will continue to operate until mid-June. At the end of the month maintenance works will be carried out at pickling and galvanising line no.4, sources say.
With a capacity of 600,000 tonnes/year Magona counts one pickling line, two rolling mills, two galvanising lines and one coating line. One more galvanising line was idled in 2010. With a substantial investment on this line, the company could reach a capacity of 900,000 t/y, sources observe.
Liberty Steel did not respond to requests for comment before deadline on Friday.
Natalia Capra France


Russia mulls doubling scrap export duty to €90/t
Russia’s economic development ministry is to decide the fate of the possible increase of ferrous scrap export duty to €90/tonne ($110) this week. This comes after economic development minister Maxim Reshetnikov ordered the appropriate departments to conduct a feasibility study of the size of the increase.
This is in order to make a balanced decision and not jeopardise the country’s scrap processors, he said at a meeting on Friday, giving the deadline for the next meeting as 26 May, the ministry says. The department is considering to increase the existing 5% duty with the minimum fiscal value of €45/t, to €90/t. The value was increased from €15/t on 29 January for 180 days (see Kallanish passim).
Reshetnikov states the importance of increasing the scrap export duty in order to alleviate risks of rising domestic steel prices and retain necessary volumes of scrap for domestic supply. He however concedes it is important to justify the size of the increase and secure a balance between scrap processors’ and users’ interests.
The ministry has two days to analyse the consequences of application of higher export duty on Russian businesses profitability and investment potential. Reshetnikov also underlined the necessity of securing predictable terms and to give guarantees to the industry that the duty will be amended in the event of scrap export prices declining, the ministry says.
Most Russian scrap is exported to Turkey, which saw scrap import prices reaching $510/tonne cfr Turkey on Friday for premium HMS 1/2 80:20.

Global pig iron output dips in April
Global pig iron production declined slightly, by 0.7% on-month, but rose 11.2% on-year to 113.4 million tonnes in April. Four-month output rose 8.3% on-year to 458.2mt.
China produced 76mt of pig iron in April, 1.6% up on-month and 3.8% up on-year, while January-April output gained 8.7% on-year at 306.6mt.
India’s output declined 12.6% on-month but rose 86.8% on-year to 6.05mt, as four-month output rose 2.7% on-year to 25.9mt.
All Asian iron producing countries reduced output of pig iron to various degrees, expect for Iran, which kept volumes flat on-month. This reduced combined Asian output in April by 0.3% on-month to 92.8mt. Year-to-date output grew, however, by 8.7% to 376.4mt, Kallanish notes.
EU-27 ironmakers also cut output in April, which at 6.47mt was 6% down on-month but rose 22.2% on-year, as year-to-date volumes rose 5.5% on-year to 26mt. The decline was on the back of slight output decreases in every country, with Germany reducing output the most, by 10% on-month, to 2.1mt.
Turkey also cut April output by 7.8% on-month to 0.85mt, but increased it on-year by 16.9%. January-April pig iron output volumes rose 4.8% on-year to 3.52mt.
The descending output trend also prevailed among CIS producers, whose combined output of 6.6mt was 3.1% down on-month, but rose 14.3% on-year, with Russia, Ukraine and Kazakhstan all reducing output. Year-to-date output rose 3.9% on-year to 26mt.
North America’s pig iron output declined 2.3% on-month but rose 60.2% on-year to 2.67mt, bringing total January-April output up 10.9% on-year to 10.4mt.
Meanwhile, South American output rose 6.6% on-month in April to 2.6mt, as Brazil ramped up production by 7.9% on-month to 2.35mt. Year-to-date South American output rose 12.6% to 10.2mt.

European plate market sees further hikes amid tight supply, higher slab costs
European plate prices jumped above Eur1,000/mt EXW across Europe following tighter material availability and higher slab costs, sources said May 21.
Several mills and rerollers were heard out of the market due to a mix between full order books, technical problems and slab costs.
One reroller was heard preferring to sell slab on the international market or use it for coils production rather than plate rolling.
The plate market, however, also benefited from the coils shortage as one source said some buyers started to buy thinner plate and use it instead of coils despite different surface properties.
Heavy plate prices have been trailing behind hot-rolled prices since early October 2020, when the coils material shortage started to be so severe that the usual Eur70-90/mt price gap — with heavy plate more expensive than HRC — turned the opposite way.
“Italians are definitely eager to close the gap,” said a European stockist, adding that fresh offers were heard at Eur1,050/mt EXW Italy for S235 grade.
A German SSC source said that even though rerollers have hiked offers, lead times have not lengthened.
“Maybe they are not getting booked that well. Big projects are missing, there hasn’t been anything major since the Nordstream pipeline project,” the source said.
As one German mill was heard fully booked and one only offering limited material, German buyers continued to look elsewhere. Thyssenkrupp’s plate mill has been fully idled since March this year.
Italian and Ruhr prices were heard neck and neck and opportunities below Eur1,000/mt EXW across Europe have been reported to be gone with further increases expected to come. One Eastern European mill was expected to come back to the market with a Eur50/mt hike.
— Laura Varriale

Non-EU import offers re-emerge in European hot-rolled coil market
Buying activity was muted May 21 as participants assessed the situation following latest price hikes and a significant rise in import offers from the European market, sources said.
An Italian reroller said offers from non-EU countries were at Eur1,030/mt CFR for October arrival, while a German stockholder said an offer from India at Eur1,100/mt FCA Antwerp came in. Egypt was heard offering at Eur1,080/mt CFR Antwerp.
A German SSC source said he received the India offer as well, along with offers from Libya and Taiwan. A South Korean offer was also received with shipment time in October.
“Maybe they are coming because it is an attractive market [price wise],” said the SSC source.
The stockholder source said the re-emergence of imports could be seen as a signal that the markets are peaking, though it was too early to say. The stockholder also reported an Italian SSC offering coils into Germany.
One European mill said they achieved Eur1,100/mt EXW plus Eur12/mt carbon surcharge, while a Scandinavian mill said that they were looking to achieve Eur1,100-1,150/mt EXW. One German mill was heard to be still offering below Eur1,100/mt EXW Ruhr for November delivery, though this was considered the bottom of the market.
The daily Platts HRC assessment for EXW Ruhr was stable at Eur1,105/mt EXW Ruhr May 21. The daily Italian HRC assessment for EXW Italy also remained stable at Eur1,100/mt EXW Italy May 21.
Availability of material remains to be the main issue in the market. Although some import offers could potentially be a window of opportunity, buyers were hesitant to commit given long lead times and uncertainty over the extension of safeguard quotas on imports into the EU following the expiration June 30.
Several sources said that one reroller would be coming back from maintenance the following week but would still have to work through a backlog of six weeks until sources expect any easing in material availability palpable on the market.
The UK HRC market, however, saw more movement within the week with participants reporting HRC levels between GBP950-970/mt, though buying activity slowed by May 21.
“Everyone has done their deals for the fourth quarter,” said a UK-based source, adding that buying appetite further ahead would be scant given the uncertainty over future developments in 2022.
UK sources said non-EU import offers for HRC had not arrived in the UK yet with one trader saying that the UK safeguard quota extension proposal published May 19 could be a turn-off for buying non-EU material.
— Laura Varriale
German steel processors see production stoppages due to undersupply: WSM
German steel processors are experiencing production stoppages due to the severe material shortage the European steel sector is currently facing, German steel processing association WSM said May 21.
Around 98% of steel and metal processors in Germany are have difficulties in buying steel, with 89% affected by production cuts, according to a WSM member survey. Around 87% cannot meet deliveries to customers anymore, according to the survey.
More than 80% of German processors believe steel producers, as well as customers in the automotive and mechanical engineering industries, have underestimated the economic recovery following the first pandemic-related shutdowns, the survey showed.
Bottlenecks can be seen in annual contract volumes and particularly in additional volumes, WSM said in a statement. One claim from steel processors in the survey was that steel mills would be “limiting material availability artificially,” it said.
Mills have been vehemently denying claims of keeping production curbs, saying that most producers would be running on full capacity.
“The results of the survey are alarming,” said WSM Chairman Christian Vietmeyer. “The steel supply has to speed up to meet increasing demand. The steel processing industry is already experiencing production stoppages. This is poison for the economic recovery that we need. We need urgently more steel and raw materials.”
Steel prices have continued on all-time highs for more than eight weeks, resulting from demand outpacing production rates since summer 2020, when demand started to pick up after widespread pandemic-related shutdowns. The daily Platts hot-rolled coil assessment stood at Eur1105/mt EXW Ruhr, May 20, seeing a Eur145/mt surge in a month, increasing continuously from the lowest point in June 2020 at Eur396/mt EXW Ruhr.
— Laura Varriale
World crude steel output in April rose 23% on year to 169.5 million mt: worldsteel
World crude steel production for the 64 countries reporting to the World Steel Association was 169.5 million mt in April, a 23.3% increase on the yera-ago month, marking a continuing recovery by the sector from the impact of COVID-19, worldsteel reported May 21.
In April 2020, global steel production had hit a recent monthly low of 137.5 million mt as pandemic lockdowns curbed output at some steelmakers and their customers in the construction, automotive and other industries.
April 2021’s output was marginally lower than the 170.11 million mt of March, which is a longer month.
Top 10 steelmaking nations
Top producer China made 97.9 million mt of crude steel in April 2021, up 13.4% on April 2020. India produced 8.3 million mt, up 152.1%. Japan produced 7.8 million mt, up 18.9%. The US produced 6.9 million mt, up 43%.
Russia is estimated to have produced 6.5 million mt, up 15.1%. South Korea is estimated to have produced 5.9 million mt, up 15.4%. Germany produced 3.4 million mt, up 31.5%.
Turkey produced 3.3 million mt, up 46.6%. Brazil produced 3.1 million mt, up 59.3%. Iran is estimated to have produced 2.5 million mt, up 6.4%, worldsteel said.
The 64 countries included in worldsteel’s statistics produced a total of 662.8 million mt of crude steel in January-April, up 13.7% on the same period in 2020, worldsteel said. These countries accounted for approximately 98% of total world crude steel production in 2020, the association said.
Blast furnace iron
Iron produced in blast furnaces amounted to 113.41 million mt in April, up 11.2% on April 2020 levels. In January-April, this amounted to 458.15 million mt, up 8.3% from a year ago.
Direct reduced iron output in April was 6.97 million mt, up 52.8% from April 2020. In January-April, DRI output was 30.43 million mt, up 13.6% from a year ago, worldsteel reported.
— Diana Kinch
China lands uppercut on iron ore prices, but no knockout blow
It’s round one to China in its efforts to cool the red-hot iron ore and steel sectors, but victory in future rounds largely depends on making increasingly harder choices, and hoping factors beyond its control work in Beijing’s favour.
The catalyst for the chill was reports that China’s government will strengthen what it termed the management of commodity supply and demand to curb “unreasonable” increases in prices – action that has so far seen the spot iron ore price retreat by almost 15% since its record high of $235.55 a tonne on May 12.
The spot price of iron ore for delivery to North China, as assessed by commodity price reporting agency Argus, dropped to $200.90 a tonne on May 21, a third consecutive losing session.
The decline in China’s main domestic iron ore futures market, the Dalian Commodity Exchange (DCE), was more pronounced: front-month contract slid 5.4% last week to end at 1,090.50 ($172) a tonne.
The selling continued on Monday, with the most-traded iron ore contract for September delivery on the DCE sliding as much as 9.5%, almost hitting the day’s downside limit of 10%. That left it at 1,016 yuan a tonne, its weakest since April 15.
What China’s pledged action means in practice is stepping up supervision of trading and trying to manage stockpiles of commodities, coupled with efforts by exchanges to raise the cost of trading.
In some ways this amounts to more talking the market down, with Beijing using its considerable powers of persuasion to try and force market participants to toe the line for what it deems to be the greater good.
The question is how long will this tactic work, especially if it isn’t matched by more concrete steps to boost supply of commodities or limit their demand?
RECORD STEEL OUTPUT
China buys about 70% of total seaborne iron ore and produces roughly half of the world’s steel output.
So far this year it has been sucking up as much iron ore as it can get in order to produce record amounts of steel, as the economy benefits from the stimulus measures put in place to boost the recovery from the impact of the coronavirus pandemic.
Iron ore imports are up 6.7% in the first four months of the year to 381.98 million tonnes, according to official data.
Steel output hit a record in April, reaching 97.85 million tonnes, up 4.1% from March. That took production for the first four months of the year to 374.56 million, up 16% on the same period in 2020.
The gains in steel output defy repeated assertions by Beijing that annual production this year will be below the 1.065 billion tonnes produced in 2020, part of China’s efforts to limit pollution from the energy-intensive steel-making process.
It’s also hard to believe that iron ore and steel prices in China will slide dramatically if the country continues to pump out steel at the current rates.
Equally, it’s not the case that vast stockpiles are being built up. Iron ore port inventories, as monitored by SteelHome, rose to 128.35 million tonnes in the week to May 21 – up slightly from the prior week’s 128.30 million but down from this year’s peak of 135.9 million in late April.
Steel rebar inventories have declined for the past 10 weeks, dropping to 7.24 million tonnes in the week to May 21, and are now 38% below the peak of 11.55 million tonnes from the week of March 12.
WORLD DEMAND, SUPPLY ISSUES
The other factors beyond China’s control including rising iron ore demand in other importers, and ongoing issues with supply, especially from number two exporter Brazil.
Japan, Asia’s second-biggest buyer of iron ore, imported 8.99 million tonnes in April, according to Refinitiv, the highest monthly total since September 2019.
South Korea, the third-biggest importer in Asia, brought in 6.79 million tonnes in April. That was down from 7.32 million a month earlier, but March’s total was the highest since October 2015, and even the April outcome was stronger than any month from January 2020 onwards, with the exception of March and November 2020.
Meanwhile Europe’s seaborne imports rose to 8.71 million tonnes in April, the highest since October last year, and marking a third consecutive months of gains.
On the supply side, Refinitiv data showed Brazil shipping 25.75 million tonnes in April, down from March’s 27.54 million and well below the 34-35 million tonnes per month being achieved in August and September last year.
Top exporter Australia shipped 71.28 million tonnes in April, down from 76.73 in March as a cyclone struck the main producing area in Western Australia state. A recovery is predicted, but the current volumes are still some way below the monthly potential of above 80 million tonnes.
Overall, it’s hard to see a sustained decline in the price of seaborne iron ore until several factors start to come together.
Supply will have to return to closer to maximum levels, and China will actually have to reduce steel output. The X-factor is rest of the world demand for iron ore, and so far in 2021 that looks like a solid growth story.
By Clyde Russel
