

ISTA disappointed at UK safeguard proposal review
ISTA, the International Steel Trade Association with headquarters in the UK, said it is “disappointed” at the latest review of safeguard measures published by the local UK authorities, Kallanish reports.
According to the association the decisions over the future of the measures “do not go far enough to allow the flexibility of supply and demand needed in today’s market in order to support UK consumer industries and economic recovery. In particular, the restrictions placed on reinforcing bars and structural hollow sections would actually hamper that recovery.”
According to ISTA the decision to maintain the 25% duty for imports beyond quotas is also wrong, because it just carries forward the level imposed three years ago without a further assessment of the current situation.
The association is set to press the UK authorities to include in the measures a “shipping clause” to protect those orders made at the beginning of the year that are planned to be delivered in Q3. “It can take five months to deliver an overseas contract to ensure a smooth supply to the UK customer; we (and our customers, and their customers) will be given less than one month’s notice of any applicable quota or safeguarding duty unless a shipping clause applies,” ISTA notice.
“Cost-efficient producers are enjoying record margins at the expense of the downstream industries and do not need this level of protection. However, as ISTA doubts that TRID will be prepared to drop restrictions completely, it proposes that quotas are significantly increased, especially where the quotas have been fixed at such a low level that they will simply not get used at all due to the risk of incurring the 25% penalty,” the association concluded.
After the formal proposal from UK authorities on safeguard measures, the market is now awaiting a decision from the European Commission on the same issue.
Emanuele Norsa Italy

Meeting on inflation hits steel futures
Chinese rebar and steel futures prices on Monday were hit by a joint meeting held by five national departments last Sunday. The meeting mentioned the upcoming regulation of spot and futures markets and sent sentiment spiralling downwards, Kallanish notes.
On the Shanghai Futures Exchange the October rebar contract closed CNY 138/tonne lower than the previous Friday at CNY 4,974/t ($773/t), while the same contract for HRC closed down CNY 177/t at CNY 5,316/t.
The Sunday meeting was composed of the National Development and Reform Commission, Ministry of Industry and Information Technology, State-owned Assets Supervision and Administration Commission, State Administration for Market Regulation, and Securities Regulatory Commission. In addition to mentioning regulation, they talked with some powerful steelmakers and industry associations and issued requirements related to actions that could support higher prices.
The meeting stated that excessive speculation in the market had disrupted normal production and sales, and pushed up prices. Although China has yet to detail actions it will take to control inflation, speculators are fleeing commodity futures in expectation of a crackdown.
By Kallanish Team

Hot-rolled crests $1,600/st in US
US hot-rolled prices appear to have hit yet another historic milestone, topping $1,600/short ton, Kallanish reports.
Market concern last week about a China-led pullback appears unfounded, says a source at one top-tier domestic mill.
“The pullback in China seems only related to China, and the sustainability of the pullback is something I question as they never seem to make less steel, like they say they are going to,” he says.
The source notes that hot-rolled was sold in the US for $1,600-1,620/st last week, with the bulk of transactions being north of 1,000 st.
Cold-rolled and coated, moreover, were sold from $1,800-1,830/st.
A Midwest buyer confirms that he now cannot source hot-rolled for under $1,600/st, while a West Coast buyer adds that lingering quotas on South Korea are insulating the US from any Chinese market shocks.
“Obviously, China cannot ship direct, but they could ship into South Korea,” he says. “But the strict quota should prevent South Korea from dumping.”
Kallanish raised its hot-rolled assessment Monday to $1,600-1,620/st, with cold-rolled likewise moving up to $1,800-1,820/st. All prices are ex-works, domestic mill.
Dan Hilliard USA
Swiss Steel gets new big stakeholder
The transfer of 10% in Swiss Steel by the main shareholder to a new investor on Friday was hailed by the group as a “significant change in the shareholder structure,” Kallanish reports.
“Swiss Steel Holding AG has been informed that BigPoint Holding AG has sold 306,000,000 shares ( …) to PCS Holding AG,” the maker of special long products wrote in a very brief statement. PCS is the investment vehicle of Swiss Entrepreneur Peter Spuhler, main owner of trains maker company Stadler Rail.
The announcement was preceded by the news that Liwet Holding had failed with an appeal to block a capital increase at the group. The investment vehicle of Russian billionaire Viktor Vekselberg had opposed the move, which was instigated by Martin Haefner, the man behind BigPoint (see Kallanish passim).
In an interpretation of the latest development, Swiss business daily Handelszeitung criticises mistakes by the group’s management and expresses belief that the new owner could bring some movement going forward. Among other things, the paper points out that an intended sale of Ascometal would have been a “bad idea,” given that the French unit returned to profit in the first quarter.
The author notes that Ascometal was originally acquired to facilitate a reshuffle of activities with Deutsche Edelstahlwerke, which suffers from high costs. He speculates that in the long run, one of the four German mills could be closed, with production moved to Ascometal.
Christian Koehl Germany
Liberty Steel cherche à vendre ses sites français
Liberty Steel cherche un repreneur pour ses sites d’Ascoval et de Hayange, en France. Au Luxembourg, la situation est toujours incertaine.
Voici quelques jours, Sanjeev Gupta, le patron de GFG Alliance, a confirmé à la presse française avoir mandaté la banque Rothschild pour la vente de deux sites de production de Liberty Steel, à savoir Ascoval, situé à Saint-Saulve (Nord), et l’usine de rails de Hayange (Moselle).
La maison mère de Liberty Steel est en proie à des difficultés financières après la faillite de Greensill, le principal créancier du groupe sidérurgique. Depuis, Sanjeev Gupta et GFG Alliance sont à la recherche de liquidités afin de faire fonctionner l’ensemble des usines dans le secteur sidérurgique.
Dudelange tourne au ralenti
La situation du groupe sidérurgique laisse craindre le pire au Luxembourg . Pour le moment, le site de Liberty Steel à Dudelange tourne au ralenti. «Les approvisionnements sont de 5.000 tonnes, c’est 10 fois moins que la normale. Pourtant, la demande est là, et la conjoncture est bonne. Mais Liberty Steel n’a pas les liquidités pour davantage d’approvisionnements», glisse Robert Fornieri, secrétaire général adjoint de la coordination Fédération Industrie-Sidérurgie au LCGB.
Conséquence directe, l’usine ne tourne qu’avec 25 à 45% de ses effectifs. Le reste du personnel est au chômage partiel. L’avenir reste donc très incertain pour le site luxembourgeois, et les syndicats commencent doucement à perdre patience.
Seul fait rassurant: la prise en main du dossier par les équipes de Franz Fayot (LSAP). Le ministère de l’Économie étudie les solutions afin de pérenniser les activités sur le site , mais aussi sécuriser l’activité sidérurgique du pays. Liberty Steel produit à Dudelange de l’Usibor pour ArcelorMittal. La fermeture ou l’arrêt du site dudelangeois pourrait mettre plus de 300 employés sur la touche, mais également toucher ArcelorMittal. Le géant sidérurgique se refuse de commenter la situation chez son partenaire. «Nous ne commentons pas les relations contractuelles avec Liberty Steel», indique la Communication d’ArcelorMittal.
Le dossier est complexe. Le site de Dudelange a été vendu à Liberty Steel par ArcelorMittal sous la pression de la Commission européenne afin de valider le rachat d’Ilva en Italie par ArcelorMittal . Dès lors, un rachat du site de Dudelange par ArcelorMittal semble improbable. D’ailleurs, la question d’un rachat est balayée d’un revers de la main par ArcelorMittal. «Concernant la reprise de Dudelange, la question ne se pose pas, puisque la Commission européenne a fait de la cession des différents sites d’ArcelorMittal un point de son autorisation pour la reprise d’Ilva, et cela impacterait directement les conditions de concurrence en Europe», indique la Communication d’ArcelorMittal.
US HRC May-October contracts move higher on LME
The London Metal Exchange’s US hot-rolled coil forward curve registered gains for the front- to six-month contracts the week ended May 21, while the further end of the curve saw significant losses.
The front of the forward curve regained strength over the week following decreases for most contracts the week ended May 14, with the May-June spread’s contango widening from $40 the previous week to $57 as HRC prices were expected to continue rising in the near term.
Still, the remainder of the forward curve maintained a backwardated structure and continued to suggest HRC prices would move significantly lower after July. The July-October spread widened from $150 the previous week to $220.
The May contract increased by $13.50 to $1,537.50/st, settling $57.25 below the latest daily Platts HRC spot price of $1,594.75/st.
The June contract rose by $59.50 to $1,594.50/st, while the July contract ended the week $55 higher at $1,575/st. The October contracts increased by $40 to $1,355/st.
Both contracts on the further end of the curve dropped over the week amid lingering uncertainty over the long-term market outlook. The 12-month contract moved $85 lower to $1,060/st, while the 15-month contract dropped by $58.50 to $1,050/st.
The contract’s weekly trading volume totaled 1,400 st the week ended May 21, down from 4,990 st the week prior. The contract has traded a total of 616,520 st since its launch in March 2019.
Rising contract prices in the futures market were supported by ongoing firm market conditions in the physical market. As availability remained limited and continued to support HRC prices at all-time highs, more buyers reported transactions at around $1,600/st amid constrained supply options.
— Ingrid Lexova

ISTA slams proposed UK import curbs extension on some steel
UK-based International Steel Trade Association ISTA considers that the UK government’s proposed continuation of some steel import curbs and quotas after June 30 may not allow the flexibility of supply and demand needed to support UK consumer industries’ recovery.
“ISTA is disappointed that the measures announced by TRID (the Department of International Trade’s Trade Remedies Investigations Directorate) do not go far enough to allow the flexibility of supply and demand needed in today’s market in order to support UK consumer industries and economic recovery. In particular, the restrictions placed on reinforcing bars and structural hollow sections would actually hamper that recovery,” the association said in a statement over the weekend.
On May 19 TRID published an intended preliminary decision to extend UK steel import safeguards and tariff rate quotas for three years from July 1 on certain product categories, including hot-rolled sheets and strips, cold-rolled sheets and rebars, where imports have been “significant.” This will cover 102 product codes.
Imports of other products deemed not to have been imported in significant quantities, or which are not produced in the UK or have not caused serious injury to domestic producers, including some metallic coated sheets, tin mill products and stainless bars, involving 135 product codes, are however proposed to be freed from quotas.
TRID has invited feedback from interested parties on the proposed measure by May 26.
ISTA argues that UK import quotas should be significantly increased, particularly as UK steel demand is met by both domestic steel producers – currently enjoying high margins due to record-high steel prices – and by imports.
Imports had a 60-65% market share in 2019, with the EU accounting for 40%; Turkey 8% and South Korea 4%, according to ISTA, which includes some 80 companies including international traders, importers, stockholders and shipping companies.
ISTA questioned in its statement the grounds on which the “out-of-quota safeguarding duty of 25%” – a penal levy for tonnages exceeding quota limits – has been continued.
Global trends ‘changing’
“Its origins lie in the USA 232 [import tariff] measures and subsequent EU reaction from three years ago, and the same levy appears to have been carried over without any commercial calculation or consideration for changing global trends during the intervening three years,” ISTA said.
It notes that for some product categories, EU quotas may now be increased to the detriment of steel from other origins.
After leaving the European Union, the UK “transitioned” the existing EU tariff rate quotas, introduced in 2018 under its safeguard scheme, to the UK. The European Commission has yet to announce a proposal on how it plans to proceed after the EU’s current steel import safeguards expire on June 30.
After TRID’s May 19 announcement, steel producers’ group UK Steel protested that the proposed measures did not go far enough to protect the UK steel industry, and that all steel import controls should be extended for a further three years, because if they weren’t “the UK will become a magnet for huge volumes of steel imports.”
ISTA dismissed UK Steel’s notion as “a fantasy completely out of step with the reality of what has been going on globally for the past six months,” with product access by steel consumers restricted by soaring prices in a protected market.
— Diana Kinch
Liberty to sell some of its UK assets to raise cash
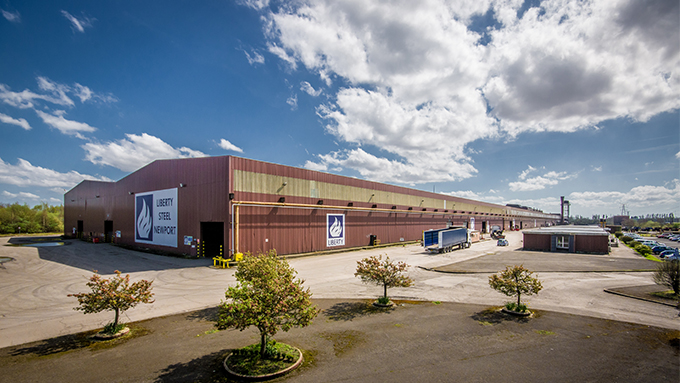
Liberty Steel, part of metals and energy group GFG Alliance, owned by magnate Sanjeev Gupta and his family, said on May 24 that as part of the company’s “restructuring” it is looking to sell its aerospace and special alloys steel business in Stocksbridge, UK and its downstream plants, the narrow strip mill at Brinsworth and Performance Steels at West Bromwich.
Liberty is experiencing cash-flow problems after its biggest financier Greensill Capital collapsed in March and is seeking fresh capital. The company recently said that in the past the company said that it will “fix or sell underperforming units” in a restructuring and refinancing drive as it recovers from Greensill’s collapse.
According to Liberty, the sale of Stocksbridge, which produces steel for the aerospace, auto and other highly engineered applications, “will allow Liberty to focus on developing its Rotherham plant, including its electric arc furnaces into a 2 million tonnes [per year] recycled greensteel plant.”
Also in the UK, Liberty said it has started the formal sale process of Liberty Aluminium Technologies and Liberty Pressing Solutions.
Union reaction
UK unions said that Stocksbridge and its downstream plants – as they are strategically important businesses for the UK’s defense, energy and aerospace sectors – must be “secured” and they asked Sanjeev Gupta to keep his promise “that none of our steel plants will close on his watch.”
“Liberty must act as a responsible seller and run a transparent sales process which fully engages the trade unions. We will expect to meet any potential buyer to scrutinize their plans and test their commitment to the workforce and to our industry,” the unions stated May 24.
“Whilst we are encouraged that Liberty and Credit Suisse appear to be making progress on the refinancing, we need to see a solution to inject cash into the UK as a matter of urgency.”
According to recent UK media reports Chinese steel producer Jingye Group, owner of British Steel, the UK’s second largest steelmaker, is now eyeing Liberty Steel’s UK plants, as well as Indian producer JSW. JSW said that such reports “are not only speculative but also misleading and mischievous. We have made and will continue to make disclosures in compliance with our obligations under SEBI (Listing Obligations and Disclosure Requirements) Regulations,” JSW said in a statement.
A British Steel spokesman said that they do not comment on commercial inquiries.
Liberty UK’s plants are not the only cash-strapped plants in the group. Italian unions told Platts that the re-rolling plant La Magona in Tuscany, Italy, also needs fresh capital.
“The situation is critical as we don’t have new raw materials coming in and we need to use all our materials in stock,” a union official told Platts on May 24, adding that from next week La Magona’s pickling line No. 4 and coated line No. 1 will suspend production, while pickling line No. 5 and coated line No. 2 will continue until the first two weeks of June. Italian unions have scheduled a meeting with Liberty on May 25
News of the planned sales by Liberty UK coincided with Liberty Steel Group’s announcement that Sanjeev Gupta and his newly-formed Restructuring and Transformation Committee are in advanced discussions with Credit Suisse Asset Management (CS) to reach a formal standstill agreement on its Liberty Primary Metals Australia business while refinancing is completed that will repay CS out in full.
“Both parties also made significant progress in agreeing a framework to resolve GFG Alliance’s remaining exposure with CS,” a press release said. Credit Suisse lost more than GBP 1bn ($1.42bn) when Greensill went down, according to UK media.
Liberty Steel has grown rapidly in recent years, including via acquisition of troubled assets, to become Europe’s fourth largest steelmaker with 6 million mt/year of crude steel production capacity in the region.
Liberty Steel UK is the third largest steelmaker in the country – with nine sites across England, Scotland and Wales – producing both flat and long products.
— Annalisa Villa