

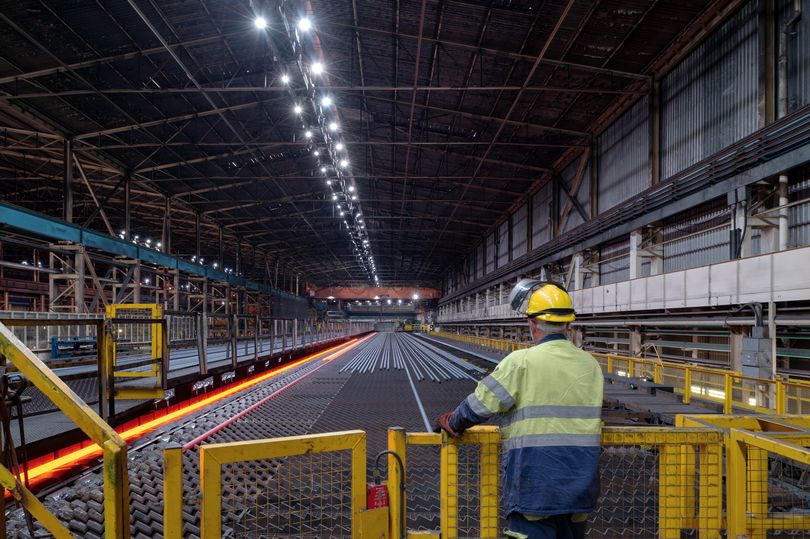
Plusieurs candidats à la reprise de l’usine Liberty Steel de Hayange
Le dépôt des candidatures s’est terminé ce mercredi 2 juin pour les candidats à la reprise de l’usine – spécialisée dans le rail – de Hayange (Moselle). Une douzaine d’offres sont arrivées sur la table.
La chute annoncée du groupe Liberty Steel, propriété du magnat anglo-indien Sanjeev Gupta, a précipité la mise en vente de plusieurs sites de production lui appartenant, dont celui de l’usine de rails de Hayange en Moselle. Cette dernière lamine notamment les rails du TGV.
Selon la presse française, les repreneurs se pressent pour visiter les installations. À commencer par ArcelorMittal et Saarstahl, qui avaient été éconduits l’été dernier, quand l’État français avait privilégié Liberty Steel.
La direction française du site mosellan a confirmé «une douzaine d’offres, dont huit significatives». Parmi elles, on note deux groupes sidérurgiques italiens, dont Beltrame, et l’espagnol Sidenor. Ce mercredi 2 juin était la date limite pour le dépôt de candidatures.
Le changement d’actionnaire sur le site de Hayange doit avoir lieu en juillet prochain.
Quant à l’usine dudelangeoise de Liberty Steel, elle tourne toujours au ralenti et suscite forcément des inquiétudes. Un piquet de protestation devant celle-ci est d’ailleurs prévu ce vendredi 4 juin par l’OGBL et le LCGB .
Écrit par Julien Carette
Publié 03.06.2021
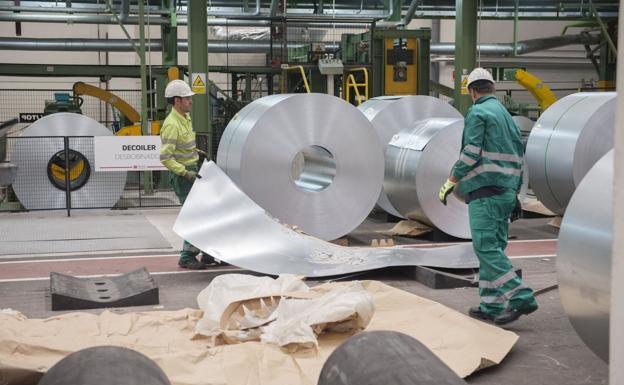
Stainless market to return to 2019 levels, BIR
Stainless steel production in Europe, the Middle East and Asia could well return to 2019 levels this year. This however is not predicted to happen in the USA, Japan and India, Nornickel analyst Alina Racu said at the Bureau of International Recycling (BIR) convention this week attended by Kallanish.
Racu also sees a swift post-Covid-19-pandemic recovery in the global stainless steel market. The 2.4% reduction in global stainless consumption in 2020 “was actually smaller than the declines witnessed at the time of the global financial crisis of 2008 and 2009,” Racu observed. “Steep year-on-year falls in the USA (-17%), Europe (-9%) and Japan (-6%) were largely counterbalanced by consumption growth of more than 6% in China on the back of its government’s metals-intensive stimulus plan.”
Olivier Masson, senior analyst at Roskill, said at the meeting: “If China were to put a cost” on mills’ carbon emissions and on the environmental footprint of raw material production processes, this could bring greater use of scrap.” He forecasts a very small hike in scrap consumption in China because of increased nickel pig iron availability.
The stainless steel sector is forecast to remain the main driver for global nickel demand despite a surge in demand from the automotive industry for electric battery grade nickel, BIR says.
The global stainless market is currently affected by a significant shortage of stainless coil, particularly cold rolled coil for which prices are going over the level of €3,000/tonne ($3,656) (see separate story).
Natalia Capra France


EU service centre, distribution shipments rebound in March
EU-27 plus UK service centre (SSC) shipments rose 2.8% on-year in the first quarter, but shipments at multi-product and proximity steel stockholding distributors were down 0.2%, according to European distributors’ association EUROMETAL.
Strip Mill Products shipments surged 21.7% on-year in March after falling 1.7% on-year in February, Kallanish notes.
When expressed in days of shipments, stocks at EU SSC reached 57 days in March versus 76 days in March 2020. For March 2021, the index of stock volumes dropped to 83, compared with 91 in March 2020. The index is based on 100 as the average for 2018.
Multi-product and proximity steel stockholding distributors saw lower shipments for all long steel in Q1 but higher strip mill product, tubular product and stainless steel deliveries.
Shipments in March rose 8.6% on-year, with only rebar seeing a decline.
When expressed in days of shipments, stock volumes levelled in March at 54 days of shipments, compared to 65 days in March 2020. Stock volumes index fell to 76 in March from 84 a year earlier, with the 100 base as the average for 2018.
Adam Smith Germany

Scrap trade inches down, US overtakes Korea: BIR
Global external steel scrap trading – including internal EU-28 trade – amounted to 99.3 million tonnes in 2020, down only 1.3% on-year despite the Covid-19 impact on major scrap-using regions, the Bureau of International Recycling (BIR) points out.
The EU-28 remained the world’s leading steel scrap exporter, growing its outbound shipments in 2020 by 4% on-year to 22.63 million tonnes, the main buyer being Turkey with 14.06mt, up 17.5%. Shipments also grew to Pakistan by 18%, but fell to Egypt and India by 3.8% and 33% respectively. The largest EU-28 steel scrap exporter was the UK with 5.66mt.
The US reduced scrap exports by 4.6% last year to 16.87mt, despite increases to Turkey, Mexico, Malaysia and Bangladesh. Vietnam reduced intake considerably, BIR says in a note seen by Kallanish.
Japan, Russia and Canada also grew scrap exports in 2020 by 23%, 15% and 3% respectively to 9.4mt, 4.7mt and 4.5mt.
Global crude steel production totalled 1.877 billion tonnes in 2020, up 0.1%, with electric arc furnace-based output down 5.7% to 493mt.
Steel scrap consumption jumped 2% in China last year to 220.3mt from 215.9mt a year earlier, underlining China’s position as the world’s largest steel scrap user. The proportion of steel scrap used in the country’s steel production was slightly lower in 2020 at 20.7%, a result of higher oxygen furnace production.
Steel scrap usage also increased in Turkey last year, by 7.8% to 30.08mt, while the country’s crude steel production climbed 6.1%. The proportion of steel scrap used in the country’s crude steel production increased to 84.1% in 2020.
Conversely, there were declines in steel scrap consumption in the EU-28, the USA, Russia, Japan and the Republic of Korea. The EU-28 recorded a steel scrap consumption drop of 10.3% to 77.54mt, while US use fell 17.6% to 50mt.
Turkey remained the world’s largest scrap importer, growing intake by 19% to 22.44mt. It was followed by India, despite a decline in intake of 23.7% to 5.38mt. The US overtook Korea as third-largest importer, increasing intake 5.7% in 2020 to 4.51mt.
Adam Smith Germany

Steel shipments from EU distributors 2.8% up January-March: EUROMETAL
Steel shipments from the EU 27+ UK flat steel service centers rose 2.8% year on year in first three months of 2021, the EUROMETAL steel stockholders and distributors association said June 2.
EU multi-product & proximity steel stockholding distribution, mainly long products, were down 0.2%.
Flat products shipments in March rose 21.7%, on the year and were down 17% from February.
The March 2021 index of stocks volumes dropped to 83 from 91 in March 2020, as the pandemic had not yet hit year-ago month volumes. Stocks at EU steel service centers reached 57 days in March 2021, compared to 76 days in March 2020, EUROMETAL said
Demand for flat products in Europe have risen since end-2020, with prices climbing Eur665/mt to a record high Eur1,140/mt base ex-works Ruhr in June.
EU Multi-Product & Proximity Steel Stockholding Distribution
In the first three months of 2021, EU27+ UK Multi-Product & Proximity Steel Stockholding Distribution registered lower shipments for all long products and higher shipments for flat mill products, tubular and stainless steel products.
In March, “total steel products” shipments increased year on year by 8.6%. Only rebar saw a negative trend, as the first three months of the year are typically not strong due to its use in seasonal construction.
Stock volumes index of EU27+ UK Multi-Product & Proximity Steel Stockholding Distribution registered at 76 in March, down from 84 in the year-ago month (average 2018 = Index 100).
Stock volumes in March saw 54 days of shipments, compared with 65 days in March 2020.
— Annalisa Villa

European HDG demand softens as buyers assess pricing viability
European hot-dipped galvanized prices were heard higher in the week ending June 2 as steel mills looked to adapt their pricing strategies to reflect those of market-leading mill ArcelorMittal, having raised HDG and CRC offer prices by Eur20/mt to Eur1,320/mt delivered across Europe May 28.
The chronic shortage of semiconductors seen over the last few months has also resulted in lower automotive demand, with more steel availability for other buyers, sources told S&P Global Platts.
In the Benelux area, some HDG offers were heard as high as Eur1,400/mt ex-works Ruhr, with transactions heard by one service center source at Eur1,350/mt ex-works Ruhr.
“It’s not the price that matters, it’s the delivery times and the possibility of getting material,” the same source said. “It’s difficult to see the prices these days.”
The source also noted a softening in demand as buyers take a wait-and-see approach to determine the viability of ever-changing prices in a heated European market now slowing ahead of the summer slump.
“Most customers know that no one has any material, so they are waiting for projects to start,” the source said. “We hear from other service centers that they are waiting a little bit [to buy], and this says something. If mills receive less orders, I think they will decrease prices — I think. Maybe not this year, but from the beginning of next year, definitely.”
In the Italian market, the supply situation for HDG and CRC was also tight, with a service center source painting a bleak outlook for production given the partial closure of the Liberty Magona steel plant.
“I do expect significant tension on galvanized steel,” the source said.
Mills were heard to be offering at Eur1,285/mt ex-works Italy for CRC, and Eur1,295/mt for HDG, with some said to be asking for even more at Eur1,320-1,325/mt for smaller quantities.
— Amanda Flint