

The impact of the procurement crisis on European OEMs: LMC Automotive
Early optimism by European automakers and analysts alike, with claims that vehicle output would improve markedly in the second half of 2021, has long since faded as the procurement crisis persists. The most recent setback has been the forced closure of semiconductor facilities in Malaysia to contain the latest COVID-19 outbreak. The crisis hinges upon raw material price increases, semiconductor shortages and bottlenecks in the production of intermediate products.
Undeniably, the major constraint to European Light Vehicle output so far this year has been the scarcity of chips, which is estimated to account for roughly 80% of the total loss in output from our pre-crisis expectations. Meanwhile, shortages of other vehicle components, such as wiring harnesses and brake parts, have further exacerbated the slowdown, albeit to a lesser extent.
Tata Steel picks hydrogen DRI-EAF path for IJmuiden
Tata Steel has chosen the hydrogen route for decarbonisation at its IJmuiden steelworks in the Netherlands, which will involve the introduction of direct reduced iron technology and electric arc furnaces. The firm will now carry out a detailed assessment for this purpose.
Tata Steel Europe chief executive Henrik Adam said at the Kallanish Europe Steel Markets virtual conference in June the firm was investigating options for the development of a 100MW green hydrogen electrolyser to feed the steelmaking process at IJmuiden. The producer previously stated it aims to reduce CO2 emissions by 5 million tonnes/year by 2030.
“By choosing hydrogen as the technology to produce steel in the Netherlands, we want to take an important strategic step in making our steel production more sustainable,” says Tata Steel ceo T.V. Narendran. “We fully support the steps to be taken by the management in IJmuiden. The decarbonisation pathway in IJmuiden will also help us chart the future transition roadmap of Tata Steel’s other integrated steel-making sites.”
Tata Steel Netherlands board chairman Hans van den Berg says: “In the next eight years IJmuiden will change into a manufacturing site with fewer chimneys. As a result of our choice for hydrogen we will work closely together with local and national authorities and our direct neighbours to become a green steel manufacturer in a clean environment.”
Separately, Tata Steel has signed up with Danish technology firm Optimum Voyage to use big-data to help lower emissions from ships delivering raw materials to its European operations. The technology will monitor vessels carrying raw materials to Tata Steel and simulate all possible route variations. As well as making journeys more efficient it will allow for any potential changes or delays to ongoing voyages to be planned for in real time, Tata says.
Adam Smith Germany

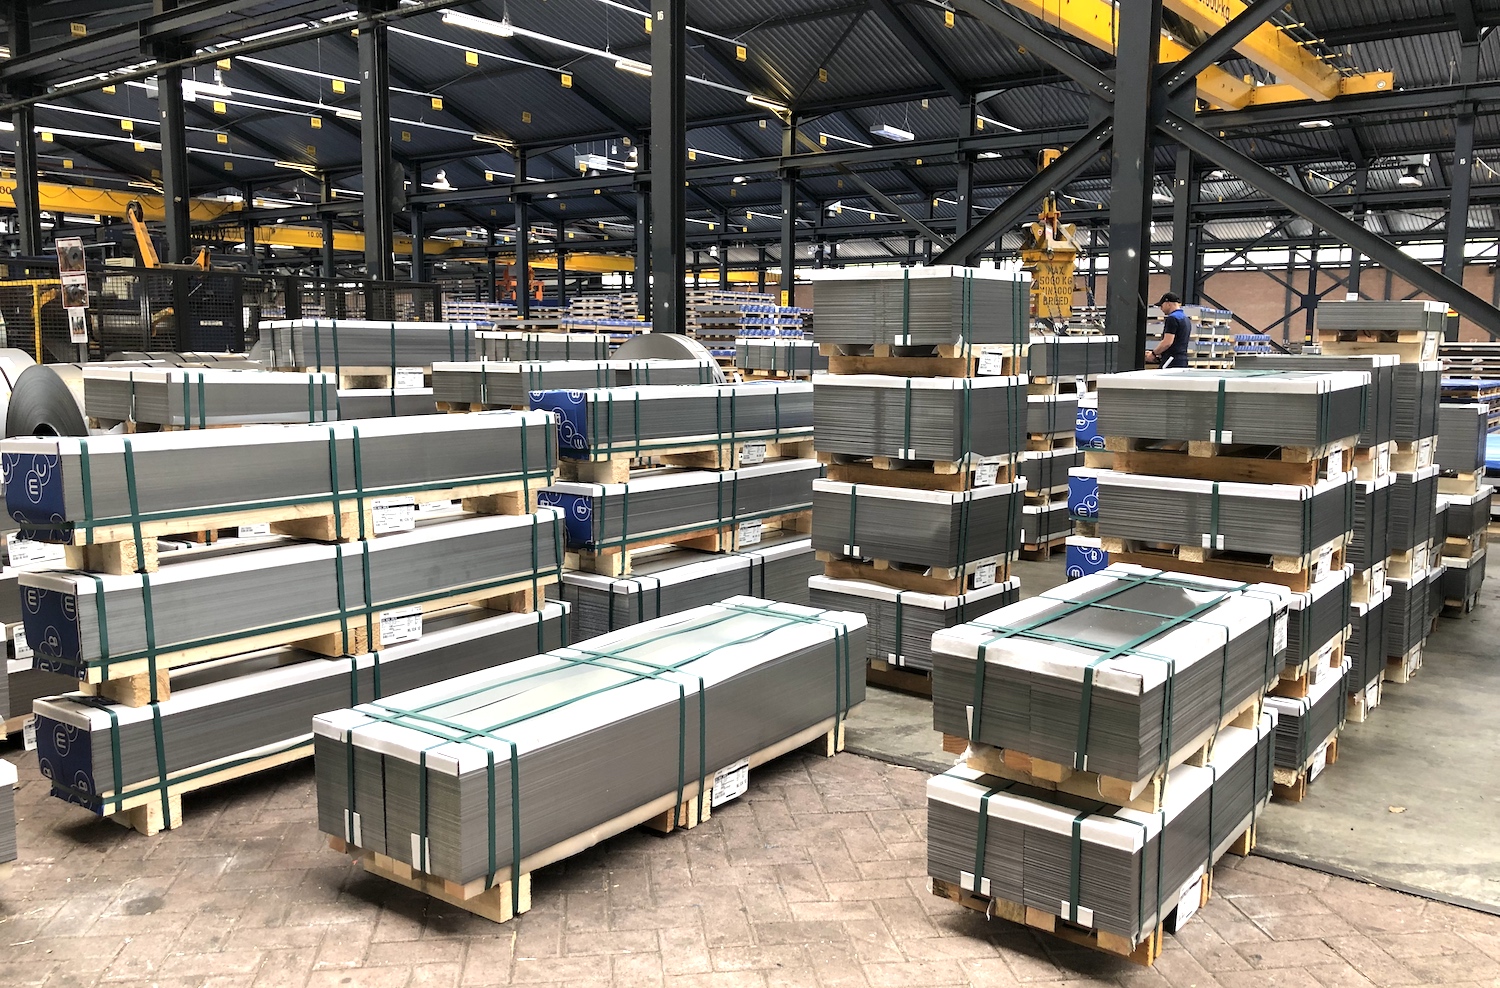
Maastricht service centre starts up new levelling line
Dutch steel service centre Laura Metaal Staalcenter Maastricht has started up the new levelling machine which it ordered from German technology supplier Kohler last year.
The company invested in the new machine to meet increasing demand for high-tensile steels. Kohler’s Peak Performer 100P.2500-RB-C replaces an old machine which was outdated, and dismantled in the spring.
Depending on the yield strength of the steel, sheets up to 2,000mm wide can be processed up to a thickness of 12mm. In practice, a maximum of 2,100mm will be processed as this is the maximum width of the de-coil lines at the service centre.
The biggest problems often occur with thin sheet material, especially with 3mm and 4mm thick sheets, explains managing director Pieter Haumann. In the production of coils, the final flatness of the sheets after de-flashing is influenced by various parameters such as the rolling temperature, or cooling time. “For this reason, we have invested specifically in being able to straighten in the thin range up to a width of 2,000mm and with a maximum yield strength of 1,000 N/mm2,” he tells Kallanish.
Laura Metaal Staalcenter Maastricht is a job order company that stores and processes material owned by other traders and distributors. Its warehouse has space for up to 72,000 tonnes of coil and 25,000t of sheet, specialising in hot-rolled high-strength steel. Tata Steel Europe owns 49% of the company.
Christian Koehl Germany

Thyssenkrupp sells Italian stainless plant AST to Arvedi
Thyssenkrupp (tk) has agreed to sell its Italian stainless steel mill, Acciai Speciali Terni (AST), to Italy’s Arvedi. The deal includes the associated sales organisation in Germany, Italy and Turkey.
AST currently employs around 2,700 people and generated sales of around €1.7 billion ($2 billion) in fiscal year 2019/2020.
The parties have agreed not to disclose the purchase price, and the closing of the transaction is expected in the first half of 2022, Kallanish learns from thyssenkrupp. The German company notes it is examining a possible minority shareholding in AST.
“We are pleased to have found a new owner for AST in the Arvedi Group, which will drive the development of the company with investments and innovations,” says thyssenkrupp’s Volkmar Dinstuhl, the current chairman of AST.
“This transaction is strategic for the whole Italian economy and represents an initial step towards new exciting developments,” says founder and president of Arvedi, Cavaliere Giovanni Arvedi. He adds that “we are very pleased that tk is considering a potential minority shareholding in AST”, which he says is proof of tk’s trust in the company.
For thyssenkrupp, the sale means the end of a process lasting many years, after it decided to part with its tradition of making stainless steel, and divested most activities to Outokumpu.
Earlier this summer, four companies were reported shortlisted for acquiring AST. Apart from Arvedi, these were Marcegaglia, Posco and Baosteel, according to union sources.
Christian Koehl Germany
Italian sections prices hold up despite scrap falls
Italian beam and merchant bar prices remain stable compared to the beginning of the month despite the declining values of rebar and scrap, Kallanish notes.
Demand in the country has slowed due to buyers adopting a wait-and-see attitude in light of the wave of price falls registered in recent weeks. Some buyers believe values for beams and merchant bars will decline but producers are holding their levels and do not intend to decrease. At present, apparent demand is lacking, but real demand remains lively, with large end-users’ order books well filled for the coming months.
Sections producers also have full order books, with good orders from end-users and some distributors, despite incursions of Spanish material offered at €20/tonne ($23) below domestic prices.
Market sources say merchant bar is still traded at August prices of €460-490/t base ex-works despite slower activity. Including €420/t average size extras, local merchant bar remains at €880-910/t ex-works, sources suggest.
Sections values also remain at high levels of €600/t base ex-works for the first category and €630-640/t ex-works from distributors. In Italy, including €380-390/t average size extras, the first category of beams is at €980-990/t ex-works. Prices increase by €20/t for each subsequent category, sources say.
Natalia Capra France

EU dumping probe pulls down demand for Turkish HDG exports
The European Commission (EC), which announced on June 24 a dumping investigation into hot-dip galvanized coil imports from Turkey and Russia, may announce the preliminary findings of the investigation in the first month of 2022, a Turkish coated coil mill manager told Platts Sept. 16.
Highlighting that they submitted information to the EC in recent weeks, the manager also said that after hearings and the preliminary determination an announcement of definitive measures might not come until mid-2022 or even later.
The probe covers calendar year 2020 and will determine whether the products under investigation are being dumped and if dumped imports have caused injury to EU producers. In addition, the EC said the examination of trends relevant for the assessment of injury will cover the period from Jan. 1 2017 to the end of the investigation period.
Another coated coil producer manager told Platts Sept. 16 that the EC is expected to announce the result of the investigation at the end of December and the provisional measures, if any, will enter into force at the end of January.
“We have submitted the files and we will answer the questionnaires that came from the EC until [Sept. 23]. The result will probably be announced in late-December,” the manager said, adding that EU customers have already begun to ask if they can share any dumping duty amounts to facilitate December sales.
The investigation has already started to affect Turkish mills’ HDG export volumes to the EU in recent months, as it raised European buyers’ cautiousness about a possible duty.
Lower demand from Turkey’s main HDG export destination has also raised the pressure on Turkish mills’ HDG pricing. Some Turkish mills’ 0.50 mm thick HDG offer prices have fallen as low as $1,200-$1,250/mt EXW in recent days, depending on coating thickness, amid slow demand in the domestic market as well. Offers for the same grade HDG were as high as $1,350-$1,400/mt EXW in June.
In April the EC imposed definitive anti-dumping duties of 4.7%-7.3% on imports of hot-rolled coil from Turkey.
A Turkish service center manager said that when an investigation is opened by the EC, it generally results in a dumping duty. “However, the rates of the AD duty are important. I don’t expect Turkish mills will face high rates at the end of the HDG investigation,” he said.
— Cenk Can

Salzgitter supplying green steel to white goods maker BSH
German steelmaker Salzgitter struck a supply deal with Germany-headquartered white goods manufacturer BSH Hausgerate for the delivery of low carbon emissions steel as BSH is decarbonizing its value chain, Salzgitter and BSH said in a joint press note Sept. 16.
The steel, with a first load shipped out in September, will initially be used for mounting brackets in washing machine production at BSH’s Lodz plant in Poland, reducing BSH’s carbon footprint by 66%.
A Salzgitter spokesperson told S&P Global Platts that the shipped volumes to BSH were test volumes and the initial tonnages would be in the two-digit range.
Salzgitter told Platts that further volume increases would depend on market development dominated by customers’ purchasing strategies.
“The maximum possible production is less limited by equipment performance but rather the more challenging production logistics. That’s why we can’t give a specific maximum production capacity at the moment,” said the spokesperson.
Salzgitter said the aim is to produce 2 million mt of low carbon emissions steel by 2025.
According to the press release, BSH’s development and manufacturing processes at its worldwide locations have been CO2 neutral since the end of 2020.
Race to reduce CO2 footprint under Scope 3 by 2030
“In comparison with 2018, we want to shave 15% off our Scope 3 CO2 footprint generated by procuring raw materials and parts, as well as through household appliance usage,” said BSH Chief Operations Officer Silke Maurer.
“We are now looking very carefully at areas where we have less of a direct impact, such as the production of raw materials and the recycling of products, for instance,” Maurer added.
BSH’s brand portfolio includes appliance brands such as Bosch, Siemens, Gaggenau and Neff.
Salzgitter’s EAF-based subsidiary Peiner Trager produces a range of long steel and special products and has supplied EAF-based slabs to Salzgitter Flachstahl for producing lower-emissions flat steel.
Salzgitter’s overall crude steel capacity is 7 million mt/year and plans to gradually replace blast furnaces from the middle of this decade through 2045 with DRI plants, initially fueled by natural gas and later hydrogen.
Going forward, hydrogen production and new EAFs are to be operated exclusively using renewable power, allowing carbon emissions from steel production to be reduced by 95% by 2045.
— Laura Varriale

European hot-rolled steel coil market seeing continued buying hesitancy
Buyers are continuing to meet steel mill offers with hesitancy across the European hot-rolled coil spot market amid bearish sentiment, sources told S&P Global Platts Sept. 15.
Trading remains quiet with only sporadic opportunities arising for mills to sell small volumes on the spot market.
A Northern European mill said they were seeing Eur1,180/mt EXW as the bottom price on the spot market and that they were achieving it at times.
Buy-side sources, however, put the widespread market value at Eur1,100/mt EXW Ruhr.
“There is more availability in the market, more import offers, material coming in, lack of auto intake,” said a German stockholder, adding that they are trying not to increase stock levels as inventory levels were growing faster than sales volumes going out to their customers.
Market participants remain bearish throughout Europe although – taking lower volume take up by the automotive industry aside — overall steel demand has not dropped at customer markets.
“Demand is not so bad, but prices are decreasing and every day we watch a little jump down…probably due to import from countries with free quota,” said an Italian service center source, referring to import sources from Asia and Northern Africa that have not reached the current quota limit.
The usual September uptick that occurs when the market returns from the summer holiday has failed to appear on the market so far and market activity on the spot market has been reduced to inquiries and observing the market while long-term contract negotiations are taking place.
“Everyone is back in the market, sentiment is the same as everywhere, so not very positive and buyers hesitant. I would say it is cautious but not softening and for the time being no chance for increase,” said a European trading source, putting indicative workable levels for Italy at Eur1,100/mt EXW and Ruhr at Eur1,100/mt EXW.
Other sources put tradable values for Italy at Eur1,030/mt EXW.
— Laura Varriale, Amanda Flint