


Celsa set to improve profitability in 2021
Spanish longs supplier Celsa says that it will see a leap in both sales and profits in 2021, Kallanish notes. According to the Group`s chairman and ceo Francesc Rubiralta, the turnover will be an expected €5.2 billion ($5.31 billion) and Ebitda could be €600 million this year, a boost in sales revenues of over 57% and in earning of almost €300m or 100%, year-on-year.
“Celsa is on track to surpass the pre-pandemic sales this year and even reach the highest turnover in our history,” Rubiralta says. The business improvement will be possible after major changes in the international steel trade and environmental awareness that augur good long-term prospects for the company due to its competitive advantage in terms of sustainability and vertical integration.
“Celsa has avoided rising raw material costs because 93% of the steel it produces comes from scrap metal collected by the group itself, and as its furnaces are electric, it emits 20 times less CO2 than its competitors, which is currently key with the price of emission rights quadrupled compared to the pre-pandemic,” the executive explains.
However, the Spanish government rescue fund to help overcome the impact of the Covid-19 crisis (Sepi) is necessary to alleviate Celsa`s loss of solvency, Rubiralta continues. The ceo, who does not specify the amount requested, estimates that the good prospects for the future should serve as a guarantee to obtain the go-ahead for the rescue and regain solvency and be able to “sit down and negotiate” the refinancing of its existing debt with main creditor banks. The group’s debt in Spain reached €2.7 billion, after investing more than €1.7 billion between 2001 and 2019. Celsa stopped paying off its long-term debt in the first year of the pandemic, saving about €200 million to date, financial media El Economista suggests.
“Our strategic plan until 2028 includes investments of €100m in Spain and units abroad and involves expanding markets, including exports to China since 2022. Celsa`s steel is already green and we are very well-positioned to capitalize on what is coming,” Rubiralta adds.
Todor Kirkov Bulgaria


EU shredded ferrous scrap prices soften for October contracts
October ferrous scrap prices across Europe fell sharply on month, but recyclers were expected to push for higher prices amid the rising international market, market participants said Oct. 11.
In Northern Europe, the Platts October assessment Oct. 11 for domestic shredded scrap was at Eur380/mt delivered, down from Eur397.50/mt in September.
Some September shredded scrap contracts agreed after the Platts index was published on Sept. 10 were heard to have settled lower than Eur397.50/mt delivered, with sources citing deals and workable levels around Eur380/mt delivered in September. Thus, prices for October were considered to be largely unchanged relative to the later deals heard in September.
In October, the Platts Northern Europe domestic shredded scrap index was at $439.77/mt delivered in US dollar terms, while the Platts shredded scrap bulk export Rotterdam index was at $425/mt FOB Oct. 8, a spread of $14.77/mt.
The spread between the domestic and export prices has steadily narrowed from August, when it was as high as $87.79/mt.
Turkish deepsea import ferrous scrap prices have recently risen sharply from a recent low of $433/mt CFR Sept. 24-28. Platts assessed Turkish imports of premium heavy melting scrap 1/2 (80:20) Oct. 11 at $463/mt CFR, up $5.50/mt on day. Shredded prices have roughly remained around $15-20/mt above HMS 1/2 (80:20) prices.
The sharp hike was fueled by high bulk freight rates and concerns over supply of higher-quality ferrous scrap in the coming months, as scrap collection rates usually slow down into the winter. Rising energy costs have led a number of Turkish mills to buy deepsea cargoes for as far ahead as second half November shipment. Market sources said mills were looking to secure their raw material costs, with energy prices unclear over the winter period.
South EU shredded prices also fall sharply
In Italy, prices remained firmly above the Northern European market, but E40 shredded scrap also fell sharply on month in Italy and Spain.
Platts’ assessment for Southern European shredded scrap was at Eur400/mt delivered for October contracts, down sharply from Eur432.50/mt from September.
“The Turkish import market is better so [domestic scrap] prices are not expected to go down, also taking into account that there is no good quality scrap,” an Italian recycler said. “I know steelmakers want to offset higher energy costs paying by far less for the scrap, but we will not allow this as the international market is recovering.”
In Spain, some sellers were holding shredded scrap offers as high as Eur425/mt delivered.
Some Italian recyclers were heard to sell into the shortsea Turkish import market, finding more attractive prices than in the domestic Italian market for grades such as HMS, for which supply is more ample.
Italian mills were heard to target Eur720/mt EXW for domestic rebar, amid rising energy costs, while Platts assessed TSI Northwest Europe Rebar at Eur772.50/mt ex-works Oct. 6, down Eur17.50/mt on the week.
— Viral Shah, Annalisa Villa


Acciaierie d’Italia restarts 2 BFs after maintenance
Acciaierie d’Italia, the joint venture between ArcelorMittal and state-owned Invitalia, has restarted blast furnace no. 1 and 4 at its Taranto steelworks after a stoppage last week due to maintenance works, a company source confirms.
The steelmaker will produce 6 million tonnes of steel in 2022, and expects to reach 4.4mt this year. Acciaierie d’Italia restarted blast furnace no.4 at Taranto in June, after restarting no.2 in February. In June the Taranto plant resumed production with three blast furnaces (BF no.1, 2 and 4). Meltshop no.1 and BF no.4 were idled in March for maintenance (see Kallanish passim).
The Italian coils sector is closely monitoring the ramp-up of Taranto’s production. The steelmaker’s recent judiciary turmoil, global pandemic, frequent production stoppages and production slowdown have contributed to the country’s short supply of hot-rolled coils. The current HRC tightness is easing in Italy as more imported material has been purchased over the past months. HRC prices have fallen compared to the beginning of September, reaching €900-930/t ($1,040-1,074/t) base ex-works for service centre quality material.
Natalia Capra France
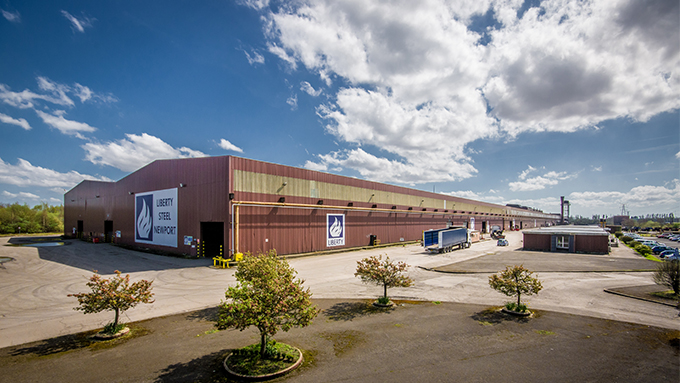
Liberty secures funding for Rotherham restart in October
GFG Alliance will inject £50 million ($68m) of new funding into Liberty Steel UK (LSUK) to enable the restart of the UK unit’s core Rotherham electric arc furnace. Production ramp-up will begin this month, with a view to reaching a 50,000 tonnes/month rate “as soon as possible”, a GFG spokesperson tells Kallanish.
The move sets the foundation for LSUK’s longer-term refinancing and expansion of Rotherham’s capacity to create a 2 million tonnes/year “GREENSTEEL” plant, the firm says. “There is a significant opportunity to expand recycling of scrap steel for growth markets such as infrastructure and engineering,” it adds.
Investment plans in Rotherham, reviewed by industry consultants, will boost production capacity, increase employment and introduce new products. “LSUK’s downstream operations remain core to LSUK’s asset base and will provide downstream capacity for Rotherham’s output, enabling increased shift opportunities at the Thrybergh and Scunthorpe mills,” GFG observes.
The fresh funding will also enable LSUK’s speciality steel division, SSUK, formed of Stocksbridge, Narrow Strip and Performance Steel, to run focused production campaigns for key customers.
Funds will be allocated to LSUK through a new separate corporate entity Liberty Capital. LSUK will run as normal with funding for growth in working capital approved through Liberty Capital. This arrangement will ensure fast and effective deployment of the £50m in initial funds in the UK, enabling LSUK to restart its operations, GFG says.
“The next stage in our global refinancing will be in Europe where a significant number of new lenders are expressing interest in refinancing our steel assets,” says chief restructuring officer Jeffrey S. Stein.
Adam Smith Germany
Cleveland-Cliffs charges into scrap with $775m acquisition
US flat-rolled and iron ore producer Cleveland-Cliffs has entered the scrap market – in a big way – with its $775 million buy of Ferrous Processing and Trading Company (FPT), Kallanish learns from a company statement.
FPT represents about 15% of the domestic merchant prime scrap market spread over 22 facilities, Cleveland-Cliffs says. About 90% of the company’s revenues come from its Midwest locations in Ohio and Michigan.
“Cleveland-Cliffs is entering the scrap business as a major player through the acquisition of a large scrap company,” says ceo Lourenco Goncalves. “Even more importantly, FPT has a very meaningful presence in prime scrap. With all the new flat-rolled EAF capacity coming online in our market over the next four years, prime scrap will only become more and more scarce.”
Nucor and US Steel both recently announced 3m short tons of new EAF capacity apiece.
“The acquisition of FPT will enhance our ability to buy back prime scrap directly from our clients, cutting the middlemen and improving the margin contribution from scrap for both Cleveland-Cliffs and for the manufacturing and service centre clients that will be able to sell scrap directly back to us,” Goncalves adds.
The buy is expected to close in the fourth quarter.
Dan Hilliard USA

Iron ore prices roar higher on market return
Seaborne iron ore prices jumped on Monday as the return of China from the October holiday led to more spot cargo bookings.
The Kallanish KORE 62% Fe index leapt $15.15/tonne to $136.88/dry metric tonne cfr Qingdao. The Kallanish KORE 65% Fe index gained %13.76/t to $158.35/dmt cfr, and the KORE 58% Fe index increased $18.36/t to $108.83/dmt cfr. A total of 170,000t of Carajas Fines shipped on 8 October traded at $160/t. A total of 120,000t of PB Fines and 80,000t of Yandi Fines traded at floating prices.
On the Dalian Commodity Exchange, January 2022 iron ore settled up CNY 22/t at CNY 771/t ($119.57/t), while on the Singapore Exchange November 62% Fe futures settled up $10.79/t at $135.44/t. The same contract for 65% Fe and 58% Fe futures settled up $10.15/t at $157.15/t, and up $7.03/t at $96.99/t respectively.
Chinese scrap and billet prices have also been strong. Grade 6mm+ heavy scrap delivered to mills in the Yangtze River Delta increased CNY 15/t to CNY 3,772/t on Monday. In Tangshan, billet prices were up CNY 20/t on Saturday and then stable through Monday at CNY 5,330/t.
Steel market sentiment has strengthened as China returned from the October holiday. End user demand has picked up due to seasonally stronger construction activity. Steel output meanwhile is also recovering from late-September’s multi-year low (see related article).
Sentiment had improved sufficiently that a number of spot iron ore deals began to emerge. Benchmark 62% Fe iron ore is now at its highest level since 7 September.