

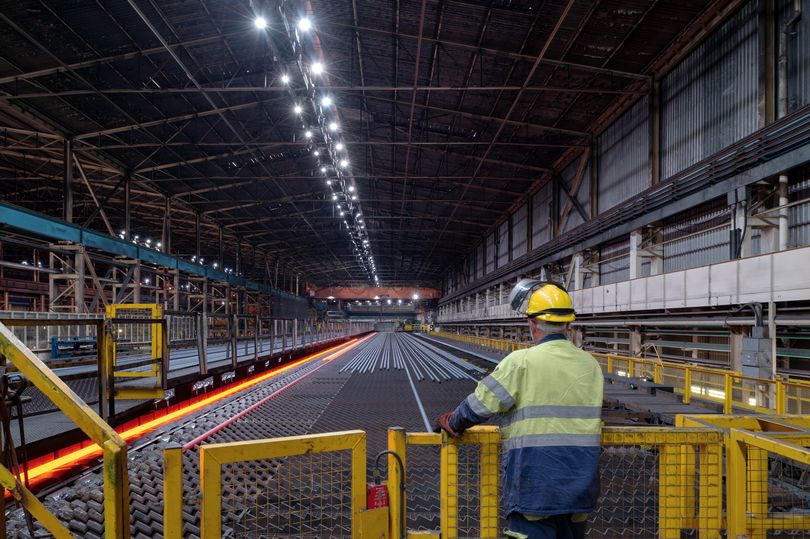
Liberty Steel évite le pire à Liège: bonne nouvelle pour Dudelange
Mardi, le tribunal de l’entreprise de Liège a validé le plan de restructuration proposé par Liberty Steel, évitant au sidérurgiste la liquidation. Une bonne nouvelle pour Dudelange.
Liberty Steel fait toujours face à d’importantes difficultés financières depuis la faillite de son principal créancier, Greensill. À Liège, la situation était devenue tendue avec les travailleurs des différents sites.
Le soulagement est venu du tribunal qui a accepté, mardi, la proposition de restructuration financière du sidérurgiste. Ce dernier va créer une nouvelle société avec un client industriel qui va devenir un partenaire dans le cadre d’une joint-venture avec la Sogepa (l’équivalent de la SNCI). Seule ombre au tableau: le plan prévoit la suppression de 90 emplois, «surtout administratifs», selon des sources syndicales. Initialement, ce plan prévoyait la suppression de 153 personnes. Ce partenariat à trois devrait maintenir l’activité de Liberty Steel en région liégeoise et sauver 690 emplois sur les sites de production de Tilleur et Flémalle.
Pour le site de Dudelange, la décision du tribunal liégeois est une bonne nouvelle dans la mesure où les sites belges vont pouvoir continuer à fonctionner, et donc à approvisionner le site luxembourgeois. «C’est effectivement rassurant pour les travailleurs du site de Dudelange. Même s’il faut maintenant voir comment ce partenariat à trois va se construire et comment il va fonctionner en matière de volume», tempère Robert Fornieri, secrétaire général adjoint du LCGB.
Une production toujours très faible à Dudelange
À Dudelange, Liberty Steel n’a toujours pas retrouvé la pleine capacité de production que peuvent offrir sa main-d’œuvre et ses outils en raison de problèmes de liquidités pour acheter des matières premières. Une situation accentuée par la hausse des prix de l’énergie qui pénalise également la sidérurgie, grande consommatrice d’électricité. «Il y aura jusqu’à la fin de l’année une production assez faible sur le site de Liberty Steel à Dudelange et les prévisions pour 2022 tablent sur une reprise progressive assez lente», explique le syndicaliste.
Dès lundi, les syndicats et la direction doivent d’ailleurs se rencontrer à nouveau pour faire le point sur la situation et les perspectives à venir. Actuellement, le site produit seulement à 20% de ses capacités.
Rappelons tout de même que 30 à 40% des effectifs du site sont encore en chômage partiel. «On commence à atteindre les limites du chômage partiel puisque certains travailleurs vont devoir retourner en poste, car ils arrivent au plafond maximal du chômage partiel, qui est de 1.200 heures», pointe Robert Fornieri.
Depuis les déboires de GFG Alliance, maison mère de Liberty Steel, les syndicats luxembourgeois plaident pour un départ du sidérurgiste et l’arrivée d’un investisseur industriel avec le soutien de la SNCI. Interrogé sur la possibilité d’un scénario à trois comme en Belgique, Robert Fornieri a répondu par la négative. «On a toujours été contre. On a toujours plaidé pour un autre partenaire industriel, mais sans Liberty Steel. Malheureusement, Liberty Steel n’a aucune envie de lâcher Dudelange et l’on doit faire avec. Mais ils doivent alors apporter des garanties sur la pérennité du site et les volumes de production à venir», conclut le syndicaliste.
Publié The 24.11.2021

Turkey’s 2021 crude steel output marches toward record with high October figure
After reaching a historical high of 3.5 million mt in August, Turkish crude steel output reached the same high level again in October, notably up by 8% on year, with the support of newly added steel capacity, according to World Steel Association data Nov. 23.
Russian steel giant, Magnitogorsk Iron & Steel Works, resumed operation of its 2.3 million mt/year hot mill at MMK Metalurji in Turkey on Aug. 9, supporting Turkish crude steel output figures in recent months. Production of 200,000-260,000 mt of HRC is planned for 2021, with the plant due to reach full capacity in 2022.
Turkish mills’ crude steel output reached 33.3 million mt in the first ten months of the year, 14.2% higher on year, according to worldsteel.
If the increasing trend continues, the Turkish Steel Producers’ Association (TCUD) expects 2021 production to exceed 39 million mt, a record high, and notably higher than the 35.8 million mt produced in 2020 amid the COVID-19 pandemic.
New Turkish steel mill investments announced this year could carry annual Turkish steel output substantially above 40 million mt in the coming years, and Turkey could even become Europe’s largest steel producer, surpassing Germany, industry sources observed.
Germany produced 33.6 million mt of crude steel in the first ten months of 2021, up 15.1% on year, according to worldsteel.
— Cenk Can


Oct global crude steel production falls 10% on year: worldsteel
Global crude steel production fell 10% year on year in October to 145.7 million mt, the third consecutive year-on-year drop as output in China dropped for the fifth straight month, weighing on volumes, according to World Steel Association data published Nov. 23.
However, the global production was 0.9% higher than September’s 17-month low.
Largest producer China produced 71.6 million mt of crude steel in October, down 22% year on year and falling 2.9% on the month to the lowest monthly volume since February 2019.
October was also the first month since March 2018 that China produced less than 50% of total global crude steel, at 49.14% of the total share.
“China is a clear player in the world market, and their reduced production has had a general impact on global production. I can’t believe that a [Chinese] production increase is possible, but I know some volumes are exported from China from what can’t be sold in the Chinese market. They’d like to support domestic prices,” a German mill source told S&P Global Platts.
The world’s second-largest steel producer India increased output in October by 2.4% year on year and 2.6% month on month to 9.8 million mt.
Production from Japan climbed 14% on the year and 1% from September to 8.2 million mt, while output from the US also rose 21% year on year and 2.8% month on month to 7.5 million mt.
Russia is estimated to have produced 6.1 million mt, up 0.5% year on year and a 3.4% month on month increase, while output from South Korea dropped 1% on the year to 5.8 million mt, although this was 6.2% higher than the previous month.
European production rises
Crude steel production in the whole of Europe, including the UK, climbed 6.8% year on year to 17.8 million mt, which was also up 5.2% month on month.
Germany, the largest European steel producer, produced 3.65 million mt, up 7% year on year and 9.4% month on month.
The European market has been contending with a surplus of steel as automobile manufacturers relinquish steel volumes on the back of falling demand from the ongoing semiconductor and chip shortage, resulting in reduced automobile production.
The return of large automotive orders has resulted in speedier delivery from mills for as early as December — two months earlier than expected.
Sources have expressed their concern about ramping up production amid the ongoing auto demand crisis. In response to this, some producers were heard to temporarily suspend their galvanizing lines until there is further clarity on real European demand for steel.
“I don’t know what to think of mills ramping up production. It’s risky, but perhaps they want to catch as much volume as possible before there is a real collapse,” a UK trading source told Platts.
Turkey, Brazil increase output
Meanwhile, Turkey produced 3.5 million mt, up 8% on the year and 4.9% higher than September’s volume.
Brazil’s estimated output rose 10% year on year to 3.15 million mt, which was down 3.2% from the previous month, while Iran’s estimated production fell 15% on the year to 2.2 million mt, although climbed 75% month on month.
Iron produced in blast furnaces worldwide in October amounted to 100.9 million mt, down almost 12% year on year and 1.4% lower than the previous month.
Production of direct reduced iron climbed 9.5% year on year to 9.1 million mt in October, which was also 3.5% higher on the month.
The data released covers the 64 countries that report to worldsteel, accounting for around 98% of the world’s crude steel production.
— Jacqueline Holman, Amanda Flint

Hydrogen conversion will quintuple electricity demand: German steelmakers
As European mills are suffering from skyrocketing energy costs, the outlook for carbon-free steelmaking appears troubled.
For an annual output of 42 million tonnes, German mills use approximately 25 terawatt hours (TWh) of electricity. Around two thirds of steel output comes via the blast furnace/oxygen converter route, which consumes some 400 kilowatt hours (KWh) per tonne of steel produced. The electric arc furnace route has a higher power consumption, at 530 KWh per tonne, according to a dossier issued by the German economy ministry.
The current plans and pledges of the country’s steel industry envisage that steelmaking, along with the production of electricity needed in the process, will be based entirely on hydrogen by mid-century. But this aim requires a power consumption of 130 TWh – more than five times the amount used at present, Kallanish learns from industry federation WV Stahl.
The lion’s share of this volume, 112 TWh/year, will be needed for electrolysis for the generation of 2.2 million tonnes of green hydrogen, mostly used in direct iron reduction. Under this scenario, the scrap-based EAF route is the lesser consumer of electricity, and will take only around 15 TWh, assuming that in future the route still accounts for one third of national output.
2021 has seen a massive increase of electricity prices in various European countries (see separate story). Compared to October 2020, the price per KWh went up from some €0.04 to more than €0.13, and is expected to climb further.
For the calculation of steel production costs, this means a year-on-year increase from €16 to €52 ($18-58) per tonne on the oxygen route, and from €21 to €69 on the EAF route. It must be noted that oxygen-route integrated mills, by way of co-generation and combined cycles, generate a large share of their power demand themselves, while most EAF mills do not have this synergy.
Christian Koehl Germany

Higher stocks moderate ore prices, downside limited: Fitch
Higher inventories than in the previous two years will moderate iron ore prices in 2022, but cost inflation – including shipping rates and environmental compliance – will limit downside risks in the coming years, says Fitch Ratings.
The credit rating agency has cut its 2022 iron ore price assumption to $90/tonne from $100/t cfr China for 62% Fe fines. “We expect the iron ore market to be more balanced in 2022 following a large deficit in 2021,” it says in a note sent to Kallanish.
For hard coking coal, the agency has revised up its price assumption for 2022 to $160/t from $135/t fob Australia. Prices will moderate from current levels due to lower demand from China, driven by the government-induced decline in steel production and winter season curbs. “However, supply is likely to remain disrupted, while there are some pockets of growing demand, including India, which support our higher-than-previously expected short-term assumption,” Fitch observes.
Nickel is meanwhile seen at $16,000/t LME spot in 2022 versus the previous $15,000/t amid residual effects of low stocks and higher prices in 2021. But in the longer term there is the risk of increased supply from Indonesia, which could potentially lead to small market surpluses.
Adam Smith Germany