


Italian crude steel output up 19.8 % in 2021 amid strong demand
Italian crude steel production in 2021 was up by 19.8% to 24.41 million mt amid strong demand for both long and flat products, although December recorded the first year-on-year fall in 12 months as mills reduced production on high energy costs, data released Jan. 20 by iron and steel association Federacciai showed.
Last year’s output also surpassed the 23.192 million mt in 2019, the last full year before the pandemic.
In December, crude steel production was down by 7% year on year to 1.5 million mt as mills were hit by the soaring energy costs. Long steel long products registered a decrease of 5.1% to 814,000 mt, while flat products were down by 3.9% to 781,000 mt.
The head of Federacciai, Alessandro Banzato, recently underscored in an interview with S&P Global Platts that high energy prices are an ongoing problem which could dent the positive outlook for 2022 unless addressed by the government.
Energy costs are the second most important cost for steel producers after raw materials. For the most electro-intensive producers, electricity represents approximately 20% of converting globally priced raw materials into finished steel products.
According to Federacciai data, electricity costs rose to an average of Eur124.37/MWh ($142/MWh) in 2021, against an average cost of Eur36.12/MWh in 2020. In December alone, average prices reached Eur281,24/MWh. The “typical” electric arc furnace without oxyfuel burners uses 475 kWh of power per metric ton of steel produced.
Crude production in 2021 started to pick up in March last year with prices that reached their highest historical level in mid-June.
In the whole 2021 long production went down by 21.8% to 13.6 million mt while flat production decreased by 16.6% to 11 million mt.
— Annalisa Villa


NLMK ramps up 2021 output but cuts sales
In 2021 NLMK increased output of crude steel by 10% on-year to 17.4 million tonnes. However, consolidated sales fell 4% to 16.8mt amid a renewal of slab sales to NLMK USA and lower commercial pig iron sales resulting from higher steel production, NLMK says in a statement sent to Kallanish.
Steel output increased on the back of basic oxygen and blast furnace upgrades at the principal Lipetsk site and higher output at the Russian Long products and NLMK USA segments.
Fourth-quarter steel output rose 16% on-quarter and on-year to 4.5mt, as oxygen supply infrastructure was repaired after the incident in August. Consolidated sales rose 8% on-quarter and 6% on-year to 4.5mt, as finished products sales gained 12% on-quarter and 18% on-year to 3.1mt on higher galvanised and hot rolled steel deliveries.
But sales growth was slower than output growth, rising 4% on-quarter and 5% on-year to 4.35mt. This was amid a 26% on-quarter and 16% on-year reduction in merchant semis shipments as internal slab shipments doubled on-quarter. Billet sales fell 86% on-quarter in Q4 amid negative profitability due to temporary export duties. The share of semis in sales was 31% or 1.4mt, down 2 percentage points on-quarter and 7pp on-year. Finished products sales at 3.1mt were up 12% on-quarter and 18% on-year.
NLMK cut Q4 export sales by 17% on-quarter and 21% on-year to 1.2mt amid high demand in home markets. This grew 14% on-quarter and 20% on-year to 3.2mt, with US sales at 0.52mt, down 11% on-quarter and up 41% on-year, and EU sales up 12% on-quarter and down 17% on-year. Russian sales grew 24% on-quarter and 31% on-year to 3.16mt on high construction sector activity.
Annual sales declined by 4% on-year to 16.8mt as sales of merchant semis fell 20% to 3.9mt on higher internal supply to NLMK USA, although finished products sales rose 6% to 11.2mt. Home market sales rose 6% to 11.4mt amid higher Russian and US consumption, while export sales fell 22% to 5.2mt due to the high baseline in 2020, when supplies were redirected to export markets.

Gas flow disruption to hit Turkish steel production
With Turkey’s steel industry already reeling from high costs and low finished steel demand, it has been further hit by natural gas usage restrictions, Kallanish observes.
In the middle of winter, as consumption of natural gas approaches record levels, gas supply problems have emerged. Turkish gas supplier Botas says the amount of gas purchased from Iran decreased by two thirds as of 17 January, and it was reset to zero as of 20 January. Iran informed Botas there was a “technical failure” and that gas flow would not be available for ten days.
Botas subsequently sent a letter to industrial plants and gas-cycle power plants that produce electricity saying it will cut natural gas flow by 40%.
The letter sent was sent to businesses with a daily consumption of more than 300 thousand cubic meters of natural gas. It reads: “Due to the increase in natural gas consumption related with seasonal conditions and the natural gas cut from foreign supply sources, some difficulties are being encountered in maintaining the supply-demand balance in our country. In order to eliminate the difficulties encountered in maintaining the natural gas supply-demand balance in our country, it has become necessary to take and implement the necessary additional measures.”
“As of 08:00 on 21 January until further notice, therefore, gas intake by enterprises is limited to an amount corresponding to 60% of its average daily gas intake amount,” it continues.
Kallanish learns that this situation will hit electric arc furnace-based steel producers rather than blast furnaces.
A Turkish EAF mill comments: “We now face the risk of not fulfilling our contractual obligations. This will cause delays to out shipments. It is not good considering we were already struggling to sell.”
Burcak Alpman Turkey

European stainless coil sales reach standoff
European stainless steel coil prices continue to increase amid a shortage of European material and increasing alloy surcharges, Kallanish learns from market sources.
Cold rolled coil is now being transacted at €4,400-4,500/tonne ($4,993-5,106) delivered on average for European material depending on customer and volumes of orders. This is CRC sold for March delivery, while mills will now quote April and May delivery. The price comprises €1,800/t base plus an average of €2,600 alloy surcharges, Kallanish notes.
Hot rolled coil prices have stopped increasing at €3,800-3,900/t delivered, due to lower-priced import offers, particularly from China, and service centres buying on the import market.
At the same time, Chinese mills have decreased their HRC and CRC prices significantly, enticing European buyers to purchase. Including duty, Chinese CRC is now at €3,650-3,670/t cfr, while HRC is at €3,200/t cfr. The gap between European and Chinese material is almost €800/t.
CRC is also being sold by Indian steelmakers into Europe at €3,700-3,750/t cfr including import duty, while CRC from Taiwan is mostly at Chinese levels, sources suggest.
Customers are importing material instead of buying in Europe and, for the first time in months, a standoff over European coil sales is being reported. The lull in the market is forecast to continue and even worsen.
Meanwhile in Europe, nickel prices skyrocketed to $24,400/t in the morning of 20 January only to decline to $23,700 some hours later. Alloy surcharges continue to be extremely high and will increase in the coming months. This is contributing to discouraging buyers from purchasing in Europe, Kallanish notes.
Natalia Capra France
Uncertainty hits Italian merchant bar prices
The Italian merchant bar market remains in a lull after the latest increases implemented in January of €30/tonne ($34) did not stick, market participants tell Kallanish.
General demand remains weak, with large distributors sometimes transacting at lower prices than producers. Today’s contracts remain at the equivalent of €500-520/t ex-works, stable on the beginning of January. Including size extras, domestic values are at €920-940/t ex-works. Purchases are still occurring back-to-back and apparent demand is practically absent at the current high prices.
Some merchant bar producers are asking for €580/t base ex-works. However, considering the uncertain market, keeping prices elevated next month may become too challenging. Sources forecast a price decrease in February, particularly if scrap values continue to fall in Italy.
Natalia Capra France
UK steelmakers urge swift US tariff agreement
The start of formal talks between the UK and US to address the US’s 232 steel and aluminium tariffs is welcome news, given the US is the UK’s second largest market. The talks must be concluded swiftly to erase the competitive disadvantage UK suppliers are suffering versus their EU counterparts, after the bloc’s own deal with the US came into effect from 1 January, says UK Steel.
“Given the competitive disadvantage created by the EU deal, it is vital that these talks are concluded swiftly to limit any additional damage to UK producers,” says Gareth Stace, director general of the association representing UK steelmakers. “The tariffs have already reduced UK exports to the US by nearly 50%. Importantly, we hope the UK Government can put its new independent trade powers to full use, building on the terms of the EU’s deal and delivering the best possible outcome for UK producers.”
US Secretary of State Gina Raimondo and UK Secretary of State for International Trade Anne-Marie Trevelyn met virtually on Wednesday to discuss their shared global overcapacity concerns (see Kallanish passim). Raimondo, Trevelyn, and US Trade Representative Katherine Tai will begin formal discussions to address these issues that threaten the industries of both nations. This will include appropriate trade measures and what the UK hopes will be the eventual removal of the tariffs.
According to US government data, approximately 265,391 tonnes of steel products were exported from the UK to the US in 2021. Cold rolled sheet, heavy structurals, large-diameter pipe, and stainless semi-finished steel were the most exported products.
Adam Smith Germany
ArcelorMittal to expand certified low emissions steel beam sales in Germany
Steelmaker ArcelorMittal said Jan. 20 it is offering more certified recycled and renewably produced long steel products in Germany and will expand accessibility to using online sales later this year.
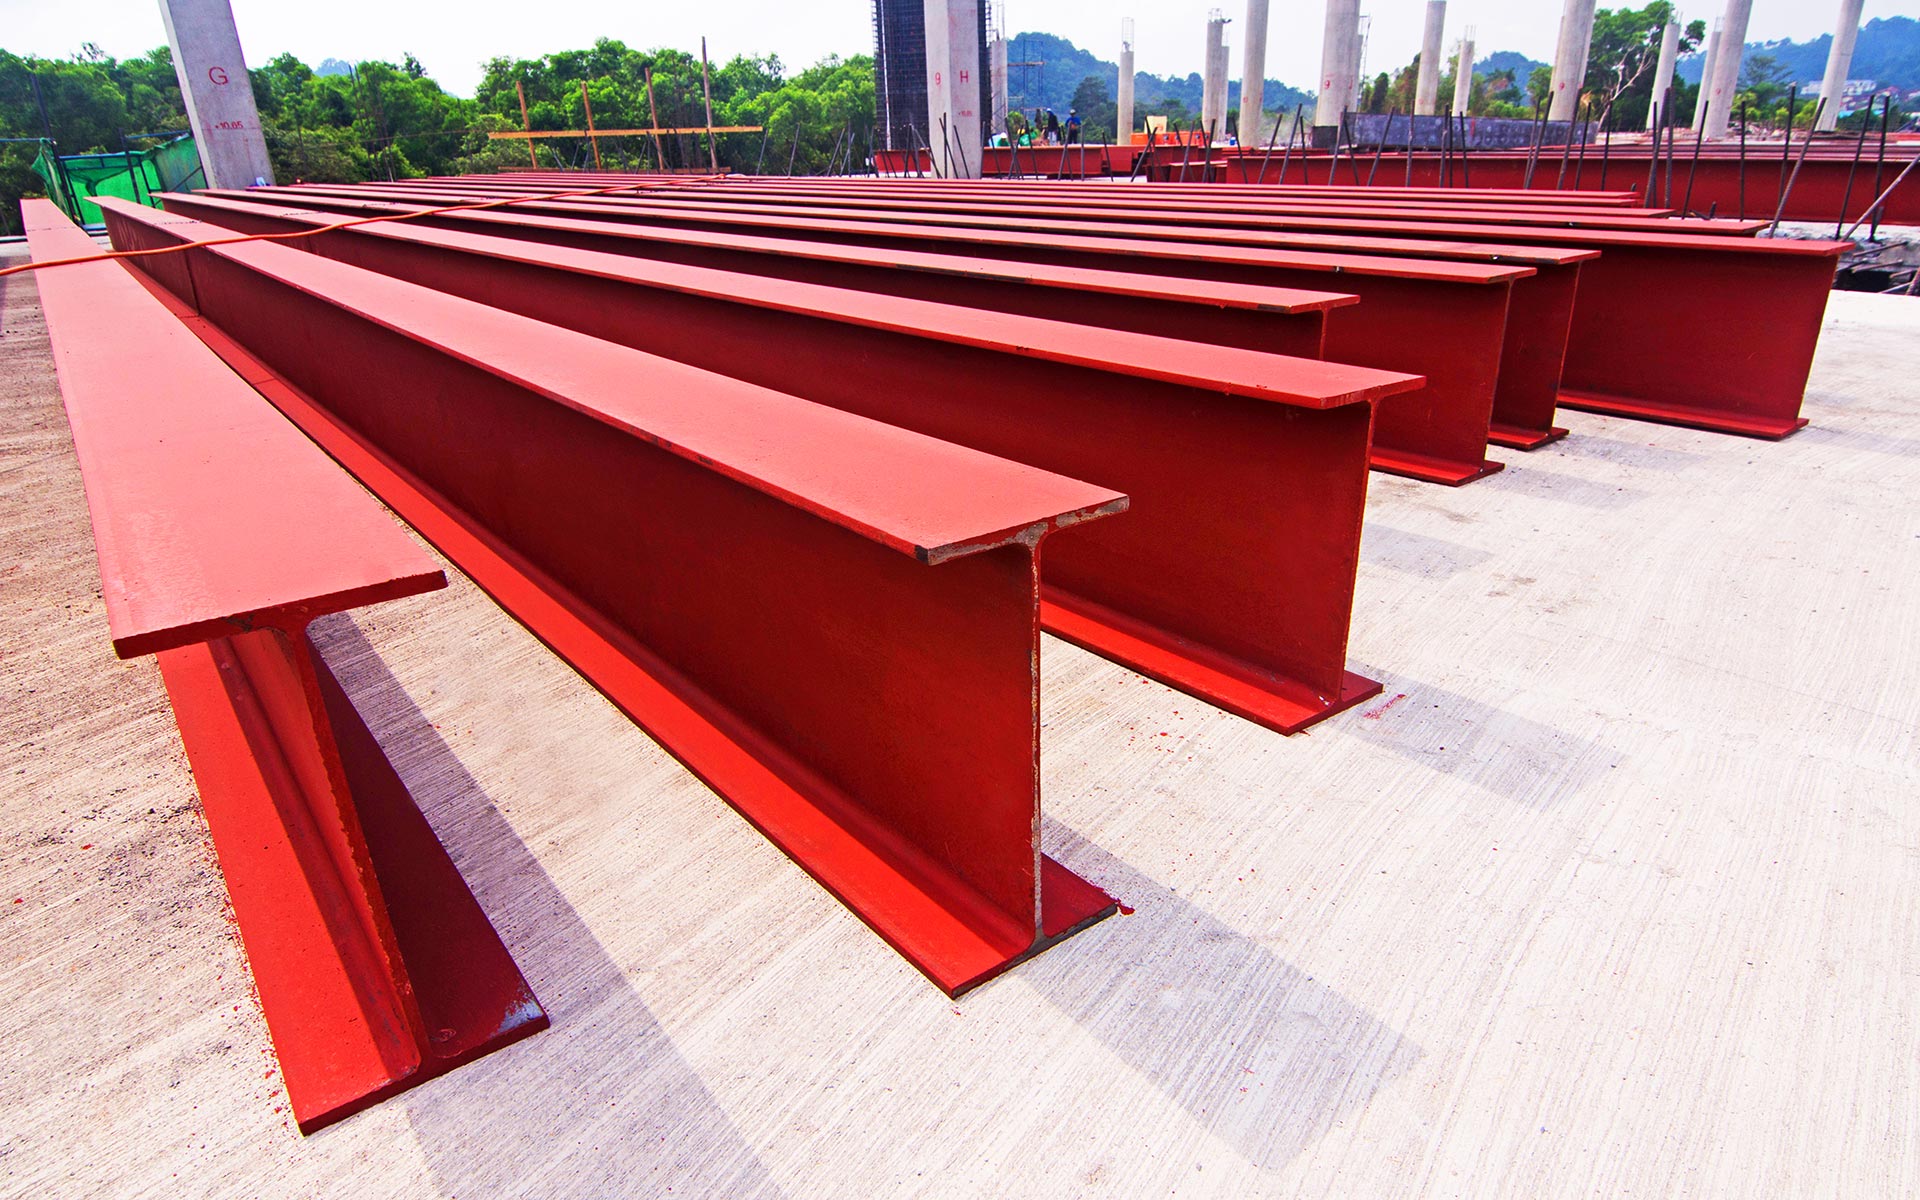
ArcelorMittal said in a statement it is increasing availability of its XCarb-branded steel beams, which is stated at 333 kg of CO2 per ton of finished product including raw materials supply and transportation.
The company referred to a published environmental product declaration for XCarb recycled and renewably produced structural sections and merchant bars, published by Institut Bauen und Umwelt, which states 1.1631 mt of scrap is used to produce 1 mt of finished steel.
The beams offered from its Essen Downstream Solutions center are in the following dimensions: HE100 to HE300, IPE180 to IPE600 in grades S235JR+M and S355J2+M.
The XCarb beams, made at ArcelorMittal Differdange in Luxembourg, are the first to offer a guarantee of 100% recycled steel scrap and 100% renewable electricity from solar and wind projects in its production, it said.
Long steel products are typically produced via ferrous scrap in electric arc furnaces, with power supplied through various generation sources and rolled and processed into finished sizes and grades. Some producers are becoming more interested around upstream raw materials and transportation emissions, certifying energy supplies, and carbon prices and markets for industry benchmarking.
“In Germany, the demand for low-CO2 products is growing, as climate change mitigation has become the most important challenge of the 21st century,” the company said.
Downstream Solutions supplies mainly steel for construction to distributors and construction partners and usually handles large requests for major German projects from Essen, including projects requesting XCarb beams, it said.
“The volume we have stocked now will help us to take the first step with our customers, leading the way in a sustainable direction,” said Oliver Menrath, managing director of Downstream Solutions Germany. “While the XCarb brand is now only available through traditional sales, we also plan to sell these low-CO2 beams through our e-steel platform later this year, becoming the first in the market to offer low-emissions steel online.”
XCarb brands all ArcelorMittal’s carbon reduced and zero carbon steel product offering. In addition to recycled and renewably produced steel, ArcelorMittal offers to sell blast furnace-based steel with XCarb green steel certificates, which include CO2 savings made by the group an independently confirmed by DNV GL.
— Hector Forster
SMA urges caution as US seeks new steel tariff deals
The Steel Manufacturers Association Jan. 20 urged the US government to exercise caution as it negotiates with other countries on arrangements to replace its 25% Section 232 steel tariff, adding that the best interests of the domestic steel industry must be considered.
“It is important that America maintains a strong Section 232 program for the US steel industry at a time when imports are surging, capacity utilization is trending down and major domestic steel producers are making monumental investments that are modernizing and electrifying our steel industry,” SMA President Philip Bell said in a statement.
Bell said that the US should be concerned about any additional alternative arrangement that will lead to increased steel imports and support countries not committed to free and fair trade.
Bell’s comments follow a Jan. 19 joint statement from US and UK trade representatives that announced the start of bilateral discussions to address global steel and aluminum excess capacity and resolve a metal tariff dispute.
It is expected that the US will modify the enforcement of its steel tariff on UK exports, much like the US’ previous deal reached in October to replace the tariff on imports from the EU with a tariff-rate quota arrangement.
The Section 232 steel and aluminum tariffs were imposed on most countries in 2018 under former President Donald Trump.
Total US steel imports in November 2021 hit 2.86 million mt, significantly up from 1.24 million mt in November 2020, according to US Census data. In the same comparison, steel imports from the UK rose to 17, 219 mt from 11,885 mt.
In 2021, US steel imports reached 26.98 million mt through November, already surpassing the 2020 full-year total of 20 million mt.
“The announcement that the US and the UK will start negotiations to find an alternative scheme to the current 232 tariffs was expected,” Bell said.
However, Bell added that the UK steel industry is export-oriented, and its production is “dominated by firms from China and India.”
“We must ensure that any agreement does not have unintended consequences and is structured in a way that meets the trade and climate objectives of our country,” he said.
The SMA represents the US electric arc furnace steel industry, which accounts for about 70% of domestic steel production.
The American Iron & Steel Institute, another trade association that represents the US steel industry, echoed the SMA’s sentiment.
“We think it is essential that the [Biden] administration ensures that the various new agreements it is considering do not result in a flood of imports that could undermine the goal of the Section 232 program to maintain a healthy domestic capacity utilization rate,” AISI CEO Kevin Dempsey said in a Jan. 19 statement to S&P Global Platts.
— Nick Lazzaro