130 participants at the 1st AMSCI & EUROMETAL Steel Trade Webinar

EUROMETAL organized together with AMSCI (American Metals Supply Chain Institute) a Steel Trade Webinar on the 24th of February.
Our webinar generated some lively questions and insights especially thanks to the high level presenters.
For this first EUROMETAL & AMSCI Steel Trade Webinar, we decided to focus on:
- The implications of Safeguards in the US and the EU
- The latest trade agreement between the US and EU offering a tariff-rate quota (TRQ) for imports from the EU
- The further perspective of Section 232 under the Biden administration.
- Invasion of Ukraine: how safeguard quotas and steel supplies will be affected?
We had a total of 185 registrations and 140 participants.

Russian sanctions seen altering EU trading patterns
Steel trade could be restricted by the raft of sanctions announced on Thursday by EU officials aimed at directly hitting Russia’s economic base following its invasion of Ukraine.
European Commission President Ursula von der Leyen confirmed on Thursday that sanctions will “target strategic sectors of the Russian economy by blocking their access to technologies and markets that are key to Russia”.
During a webinar organised by Eurometal and AMSCI, Fabrizio di Gianni from law firm Van Bael & Bellis confirmed that expectations are for sanctions to be different from the past. He explained that the target will not solely be on freezing assets, but measures will directly hit Russian economic sectors, including steel exports.
Di Gianni added that in the medium term, supply shortages from Ukraine and Russia could have an effect on future decisions on safeguard measures in Europe. Changes could be made to the system to secure the possibility of alternative supplies from other parts of the world.
An important disruption to steel trade flow from Russia and Ukraine towards the West is therefore expected, impacting global trade flow and supply of steel. The impact will come from both production and shipment stoppages in Ukraine and trade sanctions directed at Russia, Kallanish understands.
According to Eurofer numbers, in 2021 Russia exported over 3.7 million tonnes of finished steel products to Europe, while Ukraine exported over 2.5mt. These figures do not include semi-finished products, for which Europe is one of the most exposed global markets, being a large importer of slab and billet from both Russia and Ukraine.
“For the European market, the shortage of supply of iron ore from Ukraine would also be an important issue,” Metals Consulting International chief executive Alexander Siryk commented during the webinar held on Thursday. “The shortage of key supplies out of the Black Sea is going to create direct domino effects on the global steel markets.”
Emanuele Norsa Italy

EU traders highlight further port congestion issues
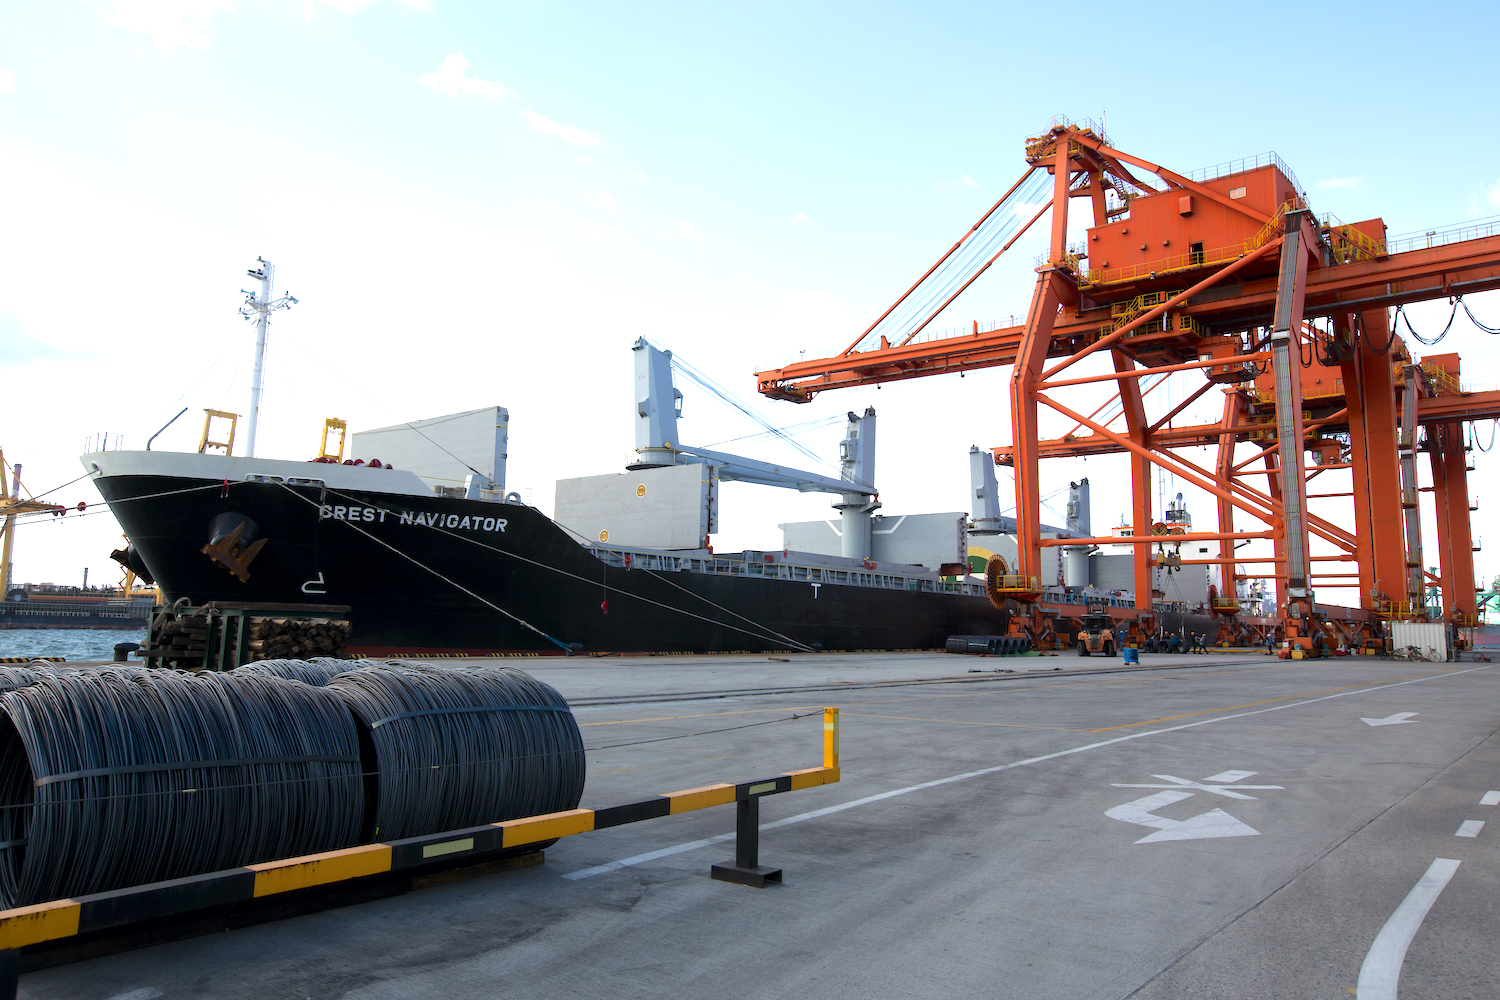
European steel traders continue being concerned by the increasing congestion at European ports, adding to the many uncertainties surrounding the steel market in 2022 so far.
A Swiss-based trader tells Kallanish that ships arriving at Italian ports can wait up to 50 days before being able to dock. This in addition to the increasing costs applied to all tariffs related to handling, stocking and transporting materials.
“Part of the issues are created by the need to store material at ports for longer than usual due to the [EU] safeguard system. Even worse however is the problem created by the skyrocketing costs of transportation and services,” the trader observes.
According to analysis provider Sea-Intelligence’s latest report in January, the European terminals congestion index doubled in 2021, reaching a new record level by the end of December. The outlook for 2022 in Europe is that the situation will continue to get worse.
A number of traders also confirm that in Antwerp, for example, some operators at the port cut to two weeks – from the previous four weeks – the period for which steel products can be stocked free of charge at the port. This decision is set to weigh further on the costs of importing steel products and on the competitiveness of such activity against domestic steel supplies.
“The cargo rotation time is presently extremely low at the port and something needs to be done about it. The congestion is a real problem,” an Antwerp port executive says.
In Spain, the situation seems to be under control at ports, while in Italy congestion at the Ravenna port is further exacerbated by a strike by lorry drivers demanding support for petrol costs.
Emanuele Norsa Italy

Metinvest halts production in Mariupol, AMKR reduces output
Metinvest has suspended some equipment at its Mariupol-based Ilyich and Azovstal plants after the Russian invasion of Ukraine on Thursday, Kallanish notes.
This decision was made by company’s crisis response centre to ensure the safety of its employees and preserve the equipment. The plants will use up hot metal and steel available on 24 February, following which operations will be put on hold.
Azovstal will suspend its operations at the coke shop, recovery and desulphurisation shop, blast furnace shop, BOF shop, plate mill, rail and structural mill, lime shop, and slag processing shop. Ilyich will suspend operations at the sinter plant, blast furnace and BOF shops, 1700 HSM and plate mill 3000, and the cold rolling mill.
The production suspension will continue for seven days. The decision on further operation of the enterprises will be made based on how the situation develops.
If Metinvest loses its assets in the Donetsk region – Azovstal, Ilyich, Pokrovskugol and Avdiivka Coke Plant – but retains the GOKs in Kryvyi Rih, the company will lose up to 40-50% of its annual profit, Ukrainian analysts said earlier this week.
ArcelorMittal Kryvyi Rih (AMKR) has meanwhile announced the suspension of steel production in Ukraine following the invasion, the company tells Kallanish.
“Regarding our plant, our team is working to slow down production to a technical minimum, but production will be stopped at our underground mines,” the firm says.
Earlier, the steelmaker reported that the plant continues to operate and its heads of departments have an emergency action plan (see Kallanish passim).
Other large Ukrainian steel enterprises, like DMZ, Ferrexpo and Interpipe, said on Thursday they were operating as usual. There were reports that Interpipe had suspended work, but the company denied this and told Kallanish it continues production as usual.
Ferrexpo’s mining and processing facilities located adjacent to the city of Horishni Plavni, in central Ukraine, where the situation remained stable on Thursday, are meanwhile operating. However, the government of Ukraine has now suspended rail transportation, the company adds.
Svetoslav Abrossimov Bulgaria

Italy braces for coil hikes amid CIS disruption
Italian hot rolled coil producers have stopped sales due to uncertainty related to the Russian-Ukrainian crisis. They are expected to return to quoting in the first March week at considerably increased prices compared to February levels, sources tell Kallanish.
The war in Ukraine and future sanctions on Russian steel will cause slab and coil shortages in Italy. Availability of both heavy plate and HRC is expected to shrink as producers are grappling with procurement issues. Some buyers in Italy are rushing to find alternative sources of supply in other European and non-European countries.
This is also touching raw materials such as pig iron, for which prices are seen increasing in the short term on shortages (see Kallanish 25 February). Meanwhile, producers of cold rolled and hot-dip galvanized coil are also suspending quoting due to uncertainty, and preparing significant increases.
HRC contracts in Italy currently remain at €880-920/tonne ($983-1,028/t) base ex-works, amid a few uncompetitive import offers starting at €880/t cfr Italy.
Demand for domestic HRC is expected to be strong when producers return to quoting, Kallanish hears. Italian steelmakers were asking for €920-930/t base ex-works for HRC before they stopped sales.
ArcelorMittal in Italy is also said to have halted sales, together with most Italian service centres who are expected to go back to selling on Monday or Tuesday.
Meanwhile, some Italian end-users that sell truck and tractor components in the CIS region are expected to experience deliveries and sales difficulties as a consequence of the war.
Elsewhere in Europe, other coil makers are either stopping sales or increasing quotes. Liberty Galati has pushed up HRC prices for April delivery to €1,000/t ex-works. The company says prices of CRC and HDG, as well as organic coated sheet will also be amended upwards (see separate article).
Steel, iron ore supply chains ‘already distorted’ by Russia-Ukraine conflict: webinar
The Russia-Ukraine conflict has already distorted iron ore and steel supply chains because of both countries’ heavy involvement in these markets, Alexander Siryk, the CEO of MCI Metals Consulting International (Düsseldorf) said on a Feb. 24 webinar that the European steel distributors’ association Eurometal and the American Metals Supply Chain Institute organized.
Russia produces around 6.5 million mt/month of steel, while Ukraine produces 1.8 million mt/month, Siryk said. Both nations are also major exporters of semi-finished steel — slabs and billet. Slabs are supplied to Europe — which would be very exposed by any major disruption — and billets to the Middle East as well as Asia.
A shortage of billets could also lead to a shortage of scrap, he said.
Some of Russia’s iron ore shipments are shipped through Ukraine, where Odessa, in the Black Sea, is the only Capesize port, with shipments often destined for China, he noted.
The European market could feel any tightness in Ukrainian iron ore supplies resulting from the conflict, Siryk said.
Alexander Julius, a member of Eurometal’s presidency, said that markets for iron and steel products are likely to get tighter as a result of the conflict and the European Commission should take this into account when imposing sanctions.
“Ukraine is not in a position to supply and Russia will most likely not be permitted to supply and this will result in a lack of material in the countries of destination, affecting end-users and steel processors, and there needs to be a substitute to make material available,” he said.
S&P Global Platts assessed Commonwealth of Independent States export billet at $663.50/mt FOB Black Sea Feb. 24, down $1.50 from Feb. 23.
Due to market disruptions resulting from the escalation of the Russia-Ukraine conflict, no bids, offers, trades, or indicative market values for the Black Sea billet assessment were reported on the day.
The Black Sea flat steel market was already reported to have “frozen” Feb. 23, prior to Russia’s Feb. 24 invasion of Ukraine, with no price changes. Turkey’s long and flat steel markets were described as being in a wait-and-see mode Feb. 24 amid trade and currency uncertainties.
Platts assessed the 62% Fe Iron Ore Index at $136.95/dry mt CFR North China Feb. 24, down $1.10 from Feb. 23 on muted procurement activities.
International trade lawyer Lawrence Hanson said on the webinar that the Ukraine situation will heighten global trade tensions.
Speakers on the webinar noted that questions may be raised over the future of Russian steelmakers’ operations in the US and the EU with new sanctions. Russia’s Evraz and NLMK Group have production assets in the US and NLMK also has operations in the EU.
— Diana Kinch

EU HRC supplies at risk from sanctions
Hot-rolled coil in the European domestic market was flat Feb. 24 as steel buyers avoided imports and anxiousness related to Russia’s military invasion of Ukraine put pressure on supplies.
The daily Platts TSI index for HRC for Northern Europe was stable on the day at Eur960/mt EXW Italy, while the daily Platts TSI index for HRC for Italy also remained stable at Eur920/mt.
With uncertainty rampant in the market due to Russia’s military invasion of Ukraine, market participants expressed concerned over potential sanctions.
Sources reported some mills holding orders due to doubts that important raw and semi-finished materials could reach the EU market from the CIS area.
Market participants in the south largely agreed that supply concerns would drive domestic prices upward.
“The market is in standby, waiting for further decisions in the coming days, probably focused on much higher asking prices,” one distributor source said.
An Italian trader source confirmed expectations of an upward price effect.
“I think prices might skyrocket,” another service center source said.
In northern Europe, sentiments on price effects were less united, with the market unsure on price direction, according to one distributor.
The distributor said mills “could afford to wait,” demonstrating less urgency in a market bearing comparative oversupply.
A distributor source said this new wave of panic has accelerated automotive recovery, with steel buyers all at once returning to the market to pick up reserved volumes.
— Benjamin Steven

Ukraine rail transport suspension following invasion hits steelmakers, miners
Ukraine’s railway operator Ukrzaliznytsia’s suspension Feb. 24 of some railway transport services following Russia’s invasion of Ukraine has impacted some of the country’s major steelmakers and iron ore miners, industry sources reported.
Production is reportedly impacted at steelmakers and iron ore miners Metinvest and ArcelorMittal Kryvyi Rih, while iron ore miner and pelletizer Ferrexpo said its facilities continue to operate.
According to an official statement, Ukrzaliznytsia’s railway capacity is needed as a priority for evacuating citizens from a number of towns and regions.
Ukrzaliznytsia informed that for the safety of citizens, it has temporarily stopped the movement of trains to Kharkiv, changed the movement of individual trains and is ready to evacuate city residents near the demarcation line.
As of 10:00 on Feb. 24, most passenger trains, all trains to Kyiv and the capital, as well as western trains run on schedule, it reported. Eastern trains continue to run at a safe speed, with slowdowns and stops possible for safety reasons near sheltered stations, it said.
A Metinvest source cited rail blockages as paralyzing its raw materials procurement and steel trade. The source said the group will continue to operate its steel and coke plants, on extended coking times, to keep them hot and given low steel demand, but that steel output will fall drastically. The group plans to take already purchased seaborne coking coal cargoes for now to keep coke plants running, according to the source.
Metinvest, which accounted for 45% of Ukraine’s crude steel output in 2021, or 9.5 million mt, said Feb. 23, before the invasion, that it had a contingency plan in place to cover any potential disruption to operations, with priority to be given to the safety of its personnel working in vulnerable sites.
Metinvest’s Ilyich and Azovsteel iron and steel works, and its Avdeevka coke plant, are all located close to the disputed Donetsk and Luhansk regions in eastern Ukraine.
Ferrexpo, the world’s third largest exporter of high grade iron ore pellets to the global steel industry, confirmed that the government of Ukraine has suspended rail transportation. “The Group is continuing to assess developments locally and will prioritise the safety of its workforce. At the present time, the Group’s mining and processing facilities are operating, which are located adjacent to the city of Horishni Plavni, in central Ukraine, where the situation remains stable,” it said in an operational update.
AM to stop underground mining
ArcelorMittal Kryvyi Rih, Ukraine’s largest integrated steel company located in Kryvyi Rih city, “is working to slow down production to a technical minimum” and production will be stopped at its underground mines, according to a statement issued by ArcelorMittal from London.
A source noted that the underground mines account for around 10% of the company’s Ukrainian mining operations, and that all open pit mining continues for now.
“We all hope for a swift resolution,” the ArcelorMittal statement said. The steelmaker “is deeply concerned about the developments in Ukraine and the potential impact this will have on our colleagues in the country. Our priority is our people and we had developed plans to help them stay safe should the situation escalate in this way,” it said.
ArcelorMittal Kryvyi Rih produces about 20% of the national steel output. In Ukraine it is also the largest steel manufacturer of both rebar and wire rod and also produces sections, angles, strips and billets. The steel plant produces over 6 million mt of crude steel a year, 5 million mt of rolled products and 5.5 million mt of hot metal. The company’s iron ore mines typically produce 24.5 million mt/year.
— Katya Bouckley, Hector Forster, Annalisa Villa
Invasion halts Ukraine steel shipments; appetite wanes for Russian steel
Steel shipments from key exporter Ukraine have been halted following Russia’s invasion of its neighbor early-Feb. 24, according to market sources. The conflict has resulted in major disruptions to logistics routes required for steel and iron ore transport.
“Deliveries from Ukraine have definitely stopped,” a Russian mill source told S&P Global Platts.
Several steel plants in Ukraine, including those of pipemaking group Interpipe and the Azovstal and Ilyich mills in Mariupol, both part of Metinvest, have stopped producing and shipping, trade sources said.
Interpipe confirmed to Platts that it stopped production and shipping in early-Feb. 24 as soon as the strikes began.
Metinvest and ArcelorMittal said they were significantly reducing their steel production, hampered by the suspension of rail freight services and closure of several ports. ArcelorMittal Kryvyi Rih, Ukraine’s largest integrated steel company located in Kryvyi Rih city, “is working to slow down production to a technical minimum” and production will be stopped at its underground mines, according to a statement issued by ArcelorMittal from London.
“We do not understand how supply chains are now operating in the country,” said a source at a steel mill. “At the moment, we perceive it as a risk to ship products by road. Consignments may get stuck or abandoned,” said the source, adding that transportation contractors are calling off truck drivers.
Traders said a missile attack from Russia took place on military facilities in the Sea of Azov area and that an increase in freight rates is expected from the Black Sea — where shipping was said to be still operational — due to risk insurance.
The Odessa port was declared closed by port authorities.
According to a Turkish government spokesperson, no decision has been taken on closing Russia’s access to the Bosphorus and that possible scenarios around the Montreux Convention, which gives Turkey control over ships passing through the straits, are under consideration.
Ukraine is the world’s 13th largest producer of steel and fifth largest exporter of iron ore by volume. It produced 21.4 million mt of crude steel in 2021. About 80% of its steel output is exported.
The country exported 44.4 million mt of iron ore products in 2021 and imported 9.85 million mt of metallurgical coal and coke products. It raised 3.9 million mt of steel scrap, of which 616,000 mt were exported.
Ukraine sends steel to the Middle East, Turkey, the EU, Africa and the Americas.
Sanctions can stall Russian purchases
The appetite has already waned for Russian steel with tougher sanctions announced or expected from the EU, the US and other countries. The Russian mill source saw as a real possibility customer refusal of deliveries from the country.
“We are operating in a zone of uncertainty,” the source said. “The port of Novorossiysk — the ships are loading — but I don’t know what to do next, the situation is difficult.”
In 2021, Russia made 76 million mt of steel, exporting around 40 million mt. In addition to numerous Atlantic buyers, China has recently become one of the biggest customers of Russian steel.
To Asia, Russian steel exports have mainly taken the form of billet in recent weeks.
News of the latest developments has dampened Asian demand, with a trader in Manila saying that rerollers in the Philippines would stop buying Russian and Ukrainian billet to avoid any potential risks.
Russia was the top non-Asian supplier of billet to the continent in 2021 by deal count, after Vietnam and Indonesia, having concluded 56 deals, compared with 72 and 63 by Vietnamese and Indonesian suppliers, respectively, according to spot data compiled by Platts.
Russian billet was sold mostly to the Philippines. While shipments via the Black Sea port of Novorossiisk appear to be unimpeded for now, and would likely be unscathed logistically out of the Russian Far East ports, sanctions on Russian banks involved in financing trades could scupper deals.
One Russian mill has stopped making offers to Asia “due to the impact of the bank issue,” an eastern China-based trader said.
Offers for Russian 5SP 130 mm billet were unchanged on the day at $715/mt CFR Manila for April shipment, two traders said, although higher offers at $720/mt on Feb. 22 were no longer available Feb. 24.
The Platts Feb. 24 assessment for billet of the specifications above slid $2/mt on the day to $708/mt CFR Manila.
Other market participants said China-based buyers could import more semi-finished steel from Russia if sanctions are widened, also as Chinese steelmakers seek to adhere to more stringent regulations concerning carbon emissions.
In the hot-rolled coil market, Russian mill MMK has been a key supplier to Asia, but has been absent from the spot market since mid-October 2021, when its last deal for early-February shipment was tracked, Platts data showed. Those cargoes would have already arrived in Vietnam.
MMK would return to offering in the middle of March for May-shipment cargoes, customers of the mill in Asia said.
Financing issues
International banking sanctions announced prior to the invasion had not impacted those that finance metallurgists, the Russia mill source said. “The main settlements are with other banks … we are reassuring customers,” the source said.
“There is already a recommendation from our risk management to convert all contracts into other currencies. Some companies are already starting to do it. I think this will be the first step for Russian companies if the US decides to restrict access to US dollars,” the source said. “Swiss franc or euro are considered and even others, shekels, Emirati dirhams.”
Russian news portal RBC reported that VTB, the second largest bank in Russia, has sent a letter to corporate clients recommending that they temporarily do not conduct any transactions in dollars and euros.
VTB was among banks targeted by new sanctions announced by US President Joe Biden late-Feb. 24.
— Staff
European steelmakers likely to raise prices on surging energy costs
European producers are preparing to increase steel prices amid a surge in energy prices in light of the Russian conflict with Ukraine; buyers are avoiding imports from both countries and some have withdrawn offers, Fastmarkets heard on Thursday February 24.
Even though the full impact of the recent escalation of the military conflict between Russia and Ukraine has yet be seen, a majority of sources expect it to push energy prices up.
“Gas prices are out of control now,” a source in Italy told Fastmarkets.
A Central European integrated mill said that their costs for gas jumped by about 55% overnight and they have withdrawn offers from the market.
Some long steel producers in Italy have withdrawn offers, while all flat steelmakers in Italy and a majority of coils producers in Northern and Central Europe have done the same. They prefer to halt and assess what the production costs will be and to review prices accordingly.
“We [will be able to] see a clearer picture in 3-5 days,” a source in Germany said.
“Nord Steam 2 is stopped, but Nord Stream 1 is still pumping gas. When it stops, and it should stop, prices [for gas may] see new highs,” a trading source in Europe told Fastmarkets.
Italian and some German producers tried to increase rebar prices recently, but demand was not strong enough to back the rise.
Sources involved in flat steel have a mixed outlook on the possibility of closure of Nord Stream 1, but they agree that energy costs will see new highs.
As a result, flat steel producers are planning to announce price increases, according to market participants, and buyers are likely to accept the new prices.
European coil producers – particularly in central Europe – traditionally rely on raw material imports from Russia and Ukraine and so will have to look for alternatives, which are likely to cost more.
Slab from both countries, which is used as feedstock by coil re-rollers in Italy and Benelux as well as by plate producers in Italy and Czech Republic, is also unlikely to continue, sources said. EU slab consumers will not be able to secure needed volumes from Brazil and other alternative sources, they said.
An Italian coil and plate re-roller was reported to have slab stocks for a few months.
Imports
European buyers could not rely on imports as an alternative to the EU-origin material because of safeguards, busy ports and the conflict between Russia and Ukraine.
“Navigation is stopped in Black Sea, ports [are] shut down. Steel that was ready to be shipped stays in ports,” a buyer in the EU said.
Exporters of coil to the EU also reportedly withdrew offers, preparing to increase offers.
Most Ukrainian ports have been closed since the Russian invasion of the country on Thursday February 24 and navigation in the Black Sea has been “paralyzed,” sources said.
Published by: Julia Bolotova, Maria Tanatar
24 Feb 2022 @ 18:29 UTC