

European Commission terminates Severstal HRC anti-dumping review
The European Commission has terminated the interim review on existing anti-dumping measures on imports of hot rolled coil from Russia’s Severstal.
The review was initiated following a complaint lodged by Eurofer last year. Now, the association has withdrawn the complaint and the European Commission has therefore decided to terminate the interim review and maintain the existing measures unchanged.
Severstal’s HRC imports into Europe have been subject to a €17.6/tonne duty since 2017, the lowest among all Russian suppliers. Severstal has since ramped up HRC supply into Europe, triggering last year’s Eurofer request to review the rate.
Last month, nevertheless, the European Commission announced a complete ban on imports of Russian steel products included in safeguard measures. This ban is part of the EU’s sanctions on Russia following its invasion of Ukraine, Kallanish notes.
Emanuele Norsa Italy


Italian plate end users face supply challenges: Fincantieri
Consumers of heavy plate in Italy and Europe are facing significant supply challenges since Russia’s invasion of Ukraine. David Bernardi, head of procurements at Fincantieri, a leading Italian industrial group, explains that alternative supply is being arranged but challenges remain related to safeguards and domestic European production.
In Italy, one of the main impacts of the war in Ukraine has been the stopping of slab imports from Ukraine. According to Siderweb data, in 2021 the country imported from Ukraine over 1.9 million tonnes of slab to be used by local re-rollers. Almost 80% of this was used by Metinvest’s Italian units, which supply heavy plate and other flat rolled products, Kallanish notes.
“We have had a strategic relationship with Metinvest for the supply of heavy plates for some time now,” Bernardi observed during a webinar this week. “Their plate mill in San Giorgio di Nogare is strategic for our supply and we are now trying to give them all the possible support to diversify slab supply and continue working in partnership.”
“We also started during recent years to diversify our plate supply, using our global network. Since last year, we have active supply channels from South Korea, India and Brazil. We are also considering opening supply channels with the US,” Bernardi added.
Amid these supply challenges, EU safeguard measures are seen as a burden for industrial groups in Europe. “Today, the safeguard measures for our sector make no sense, they only penalise the industrial system in Europe and Italy,” the executive said.
Domestic supply is not of much help either. The largest integrated steelworks in Taranto, formerly Ilva, is still struggling to boost output and relaunch its industrial activities. “Ilva used to be an important supplier for our group. We have restarted working with them since the Italian authorities entered into the group’s management,” Bernardi concluded.
Emanuele Norsa Italy

AMKR eyes exports from Poland’s Baltic Sea ports
ArcelorMittal Kryvyi Rih (AMKR) has started negotiations with the Polish government over using Poland’s Baltic Sea ports to export steel produced in Ukraine, AMKR confirms to Kallanish.
“The Polish branch of ArcelorMittal is helping AMKR in communication with the ports and the government,” AMKR chief executive Mauro Longobardo notes in an interview with Kryvyi Rih’s One TV. “We have a large volume of goods. It is necessary that foreign countries prepare for the fact that this volume will pass through them, which was not the case before.”
Another task for AMKR’s management is to develop a new logistics route for the supply of coking coal from Kazakhstan, since this raw material was hitherto transported through Russia. The Ukrainian enterprise typically received 30% of the coal needed for coke production via this route.
Fellow Ukrainian steelmaker Metinvest has meanwhile started deliveries of its coking coal to AMKR, Mauro Longobardo said in another interview with Novoye Vremya. “So far, these are trial batches, because we have not used their coal before,” he observes. “It has certain features that affect the quality of coke. Therefore, we need a new ‘recipe’, which we are developing. In return, Metinvest is ready to take an excess of coke from us because they lost the opportunity to produce their own due to the Russia-Ukraine war.”
Currently, two of AMKR’s coke batteries continue to operate at a technological minimum, while four more are hot idled, he adds. If coal supplies ramp-up and the firm wants to increase steel production, two further coke plants, No.4 and No.6, can be brought back on line.
AMKR also intends to consider launching blast furnace No.9, but not earlier than in June when it reaches 100% iron ore mining and 50-60% steelmaking capacity, he adds. “At the moment, the mining department is working at 30% capacity, and in the near future we plan to develop logistics routes to increase the export of concentrate,” Longobardo says.
AMKR restarted blast furnace No.6 on Monday after more than a month of downtime, and plans to launch blast furnace No.8 on 2 May (see Kallanish passim).
Svetoslav Abrossimov Bulgaria

Assofermet files application to lift EU safeguard measures
Italian steel trade association Assofermet has filed an application to the EU to lift safeguard measures on all 28 product categories, which have been in force since 2018, a member of the association tells Kallanish.
“Today, we are witnessing an unprecedented crisis generated by sanctions against Russia, the impossibility of importing from Ukraine and a rise in energy costs impacting raw materials, semi-finished and finished products,” the representative comments.
The EU recently cancelled the quotas assigned to Russia and Belarus, and then transferred them to other countries. However, a significant share of Russia’s quotas was transferred to countries that, under normal conditions, already had a share exceeding the needs of the European market. The quotas assigned to Ukraine have not been subject to changes but are unlikely to be used in full before the end of the war there.
“These recent decisions that do not sort out the current issue of shortage in Europe have pushed us to apply for a temporary suspension of import restrictions, so that some balance is restored in the market in the short term, protecting the entire production chain,” the representative explains.
In early 2019, definitive annual quotas were imposed by the EU on material from Korea, Taiwan, India, USA, Turkey, Vietnam, Malaysia, and other countries. These replaced the provisional measures imposed in 2018. The measures were then extended in June 2021 for a further three years, with a tariff quota liberalisation of 3% on an annual basis.
Natalia Capra France

EU prime mill hot-rolled coil offers converge toward lower levels
The EU coils market softened further April 13, with prime EU mills heard relaxing offer levels and trading limited grades of material.
A service center source confirmed a reduction in offer levels from prime mills.
“We are indeed seeing a softening in prices, tier one mills are at around Eur1,350/mt – prices have definitely moved down from the Eur1,400 mid-point we’ve been seeing the last few weeks,” the service center source said.
When asked about a future price direction, the source described the situation as complicated.
“Energy costs are sky-rocketing, and many EU mills are still dependent on iron ore and carbon coal from Russia,” the same source said. “New sanctions have blocked that supply from August, so they are now reworking supply chains which will have an impact on price – but these negotiations don’t happen overnight.”
A distributor source reported deals heard from prime mills at Eur1,350/mt, predicting further reduction in prices.
“Prices will need to correct, there is much cheaper material available from China, for example,” the distributor said. “Some are thinking of importing from China and incorporating the full dumping duty, as even then costs are competitive with current domestic levels.”
However, a second service center source stressed that EU standards precluded a full substitution of European mills for foreign import alternatives.
“Much import material cannot match European mill offerings on quality and specific grades — higher grade, certified material is not so easy to substitute,” the second service center source said.
In South Europe, prices continued to soften, with offers heard at Eur1,280/mt-Eur1,300/mt on the day. Transactional activity remained reduced, with one trader citing the price gap between imported and domestic offers as a major factor restricting willingness to restock.
Hot-rolled coil ex-works Ruhr was assessed at Eur1,350/mt on the day, and HRC in South Europe was assessed at Eur1,280/mt ex-works Italy.
— Benjamin Steven


EU value-added steel sees price cuts, mixed import sentiment
Prices softened for value-added steel coils April 13, with galvanized material under new pressure given the popularity of imported HDG.
The EU value-added coils market saw price reductions on the day as mills reduced offers against resistant buyers, following recent price hikes.
In Northern Europe, CRC remained stable at Eur1450/mt ex-works Ruhr, with HDG moving down Eur20 to Eur1500/mt ex-works.
In the South, prices fell further, with both CRC and HDG assessed down Eur50 to Eur1400/mt and Eur1450/mt, respectively.
A distributor source reported tradable value for Northern HDG at Eur1500/mt or below, emphasizing that imports recently entered the market. In terms of EU safeguard quotas, the HDG allowance for China and South Korea has been exhausted, with Chinese material exhausting the quota on the first day of the quota refresh.
The source said Turkish HDG exports were a site of interest, given Turkey’s continued access to Russian steel.
“Turkish galv exports will be able to draw a large profit by value-adding HRC sources from Russia. Turkish mills can buy from Russia at sub-Eur900, with huge potential margins if they then sell that material into Europe.”
A service center source saw the same opportunity and pressure from imported material but thought priority would still be given to domestic mills.
“The euro is getting closer to one-to-one with the dollar, making imports more expensive and thus less attractive to buyers,” said the source. “Much import material cannot match European mill offerings on quality and specific grades. Higher grade, certified material is not so easy to substitute.”
The source also noted the exhaustion of HDG quotas early in the month, saying long lead-times and ongoing uncertainties with the effects of the Ukraine war could continue to discourage interest in the import market.
— Benjamin Steven
Belgian court orders liquidation of Liberty Steel Liège, rejects restructuring plans
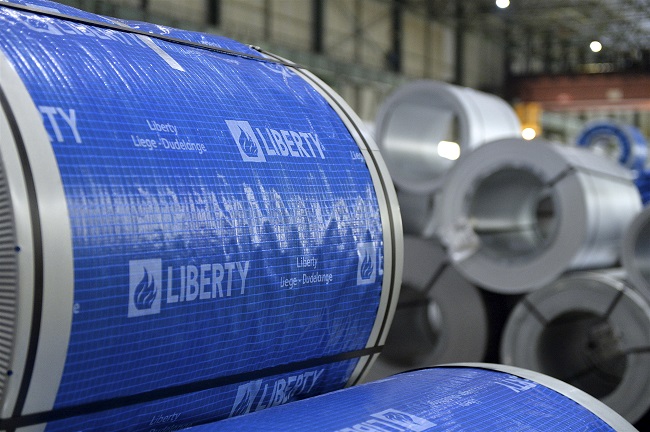
Liege Commercial Court in Belgium has rejected steelmaker Liberty Steel’s restructuring plans for its Liege subsidiary and ruled April 13 that it should be liquidated.
The court ruled against the restructuring April 13, siding with workers unions and the Walloon regionl government’s investment arm Sogepa, which no longer wanted the two Belgian steel plants, Tilleur and Flemalle, in the hands of Liberty.
In September, it was reported that Liberty had been in negotiations with the Walloon government for Sogepa to take a 49% stake in Liberty Liege and put up a loan for the plants to continue operations.
A GFG Alliance spokesperson told S&P Global Commodity Insights that the company planned to appeal the court’s decision.
“We are very disappointed that the Commercial Court has decided to ignore our legal arguments and our detailed presentation on the progress Liberty Liège has made on its transformation plan, which included the restart of the packaging line in Tilleur last month, as well as Liberty’s commitment to deliver the investment required to cover our outstanding requirements,” the spokesperson said in an emailed statement to S&P Global.
“We continue to believe our transformation plan would have provided the business with a long-term, sustainable future and preserved 650 jobs,” the spokesperson said.
The transformation plan included the tinning line at Tilleur, developing a new business model to build partnerships with major customers to manufacture specialist packaging for products, as well as using the G5 galvanization line at Flémalle to generate short-term profits.
The Tilleur packing line reopened on Feb. 14, 2022, but the Flemalle steel galvanizing lines have been at a standstill since December due to a lack of feedstock and the ongoing restructuring process.
Transformation plan
The transformation plan and restructuring process were presented to the Liege Enterprise Court on March 30, when Liberty management also explained it had been made much more complex due to rising energy and carbon prices, supply shortages due recent geopolitical developments and excessive competition from imports into Europe.
GFG Alliance, which groups together Liberty Steel Group and other metals and energy assets owned by magnate Sanjeev Gupta, acquired Liberty Liege in July 2019 from ArcelorMittal and has provided more than Eur80 million ($86.6 million) in funding since, including Eur28 million since December 2021.
However, the company said its long-term investment plans for the plants had been “undermined by the poor steel market in 2019 before the business was adversely impacted by the pandemic and supply chain disruptions.”
GFG’s main financier Greensill Capital also collapsed in March 2021.
“These issues, while being managed effectively even while the plant underwent a significant restructuring process, have been exacerbated over the last few months due to the huge rise in energy and carbon prices,” the spokesperson said.
Local Belgian media reported that the ruling was welcomed by workers unions and ended months of uncertainty. Three liquidators had already been appointed, the reports said.
The GFG spokesperson said Liberty would be working with the administrators to identify the next steps for the business and its employees.
If liquidation does go ahead, it could take several months or longer, depending on interest from potential buyers for the company and/or its assets, as well as available financing.
The spokesperson said Liberty was continuing to engage with other possible raw material suppliers and partners to restart Liberty Liège’s sister plant at Dudelange in Luxembourg.
Liberty merged its Liege, Dudelange in Luxembourg and Magona steel works in Italy into its larger Galati integrated steel operation in Romania in June 2021 as part of a broader group restructuring.
Dudelange and Liege together have production capacities estimated at 1.6 million mt/year of galvanized/coated steel, 300,000 mt/year of cold-rolled coil and 200,000 mt/year of tinplate.
The Platts North European hot-dip galvanized coil domestic ex-works price was assessed at Eur1,520/mt April 6, down from its recent high of Eur1,550/mt reached March 23, but up from Eur1,100/mt at the start of 2022.
— Jacqueline Holman