


Northwest European mills offer further discounts to secure summer volumes
Hot-rolled coil prices in Northern Europe continued a downward trend Aug. 8 as German mills offered discounts on official offers to secure volumes in the holiday period.
S&P Global Commodity Insights assessed hot-rolled coil in Northwest Europe down Eur10/mt on the day at Eur790/mt ex-works Ruhr.
While service center sources described official offer levels as relatively stable at Eur840-870/mt ex-works Northern Europe, the actual tradable range sat much lower, with unconfirmed deals heard as low as Eur770/mt ex-works Ruhr.
A trader source said mills were targeting a price level of Eur800-820/mt delivered Northern Europe, the equivalent of Eur750-760/mt ex-works Ruhr on longer distance deals. Deals within Germany sat higher on the Eur750-800/mt tradable range.
The German market was heard as “silent,” due to regional holidays, with activity in the Italian market diminishing.
“There is no trade, production, or indeed market, in Italy,” said the trader.
Achievable prices in Italy were cited stable at Eur780/mt ex-works Italy, recent indications for the Italian market have ranged from Eur750-790/mt ex-works, with no transactional activity heard due to ongoing holidays and capacity reductions.
HRC in South Europe was assessed stable on day at Eur770/mt ex-works Italy, according to S&P Global Commodity Insights data.
— Benjamin Steven, Maria Tanatar

Italian first-half car production falls
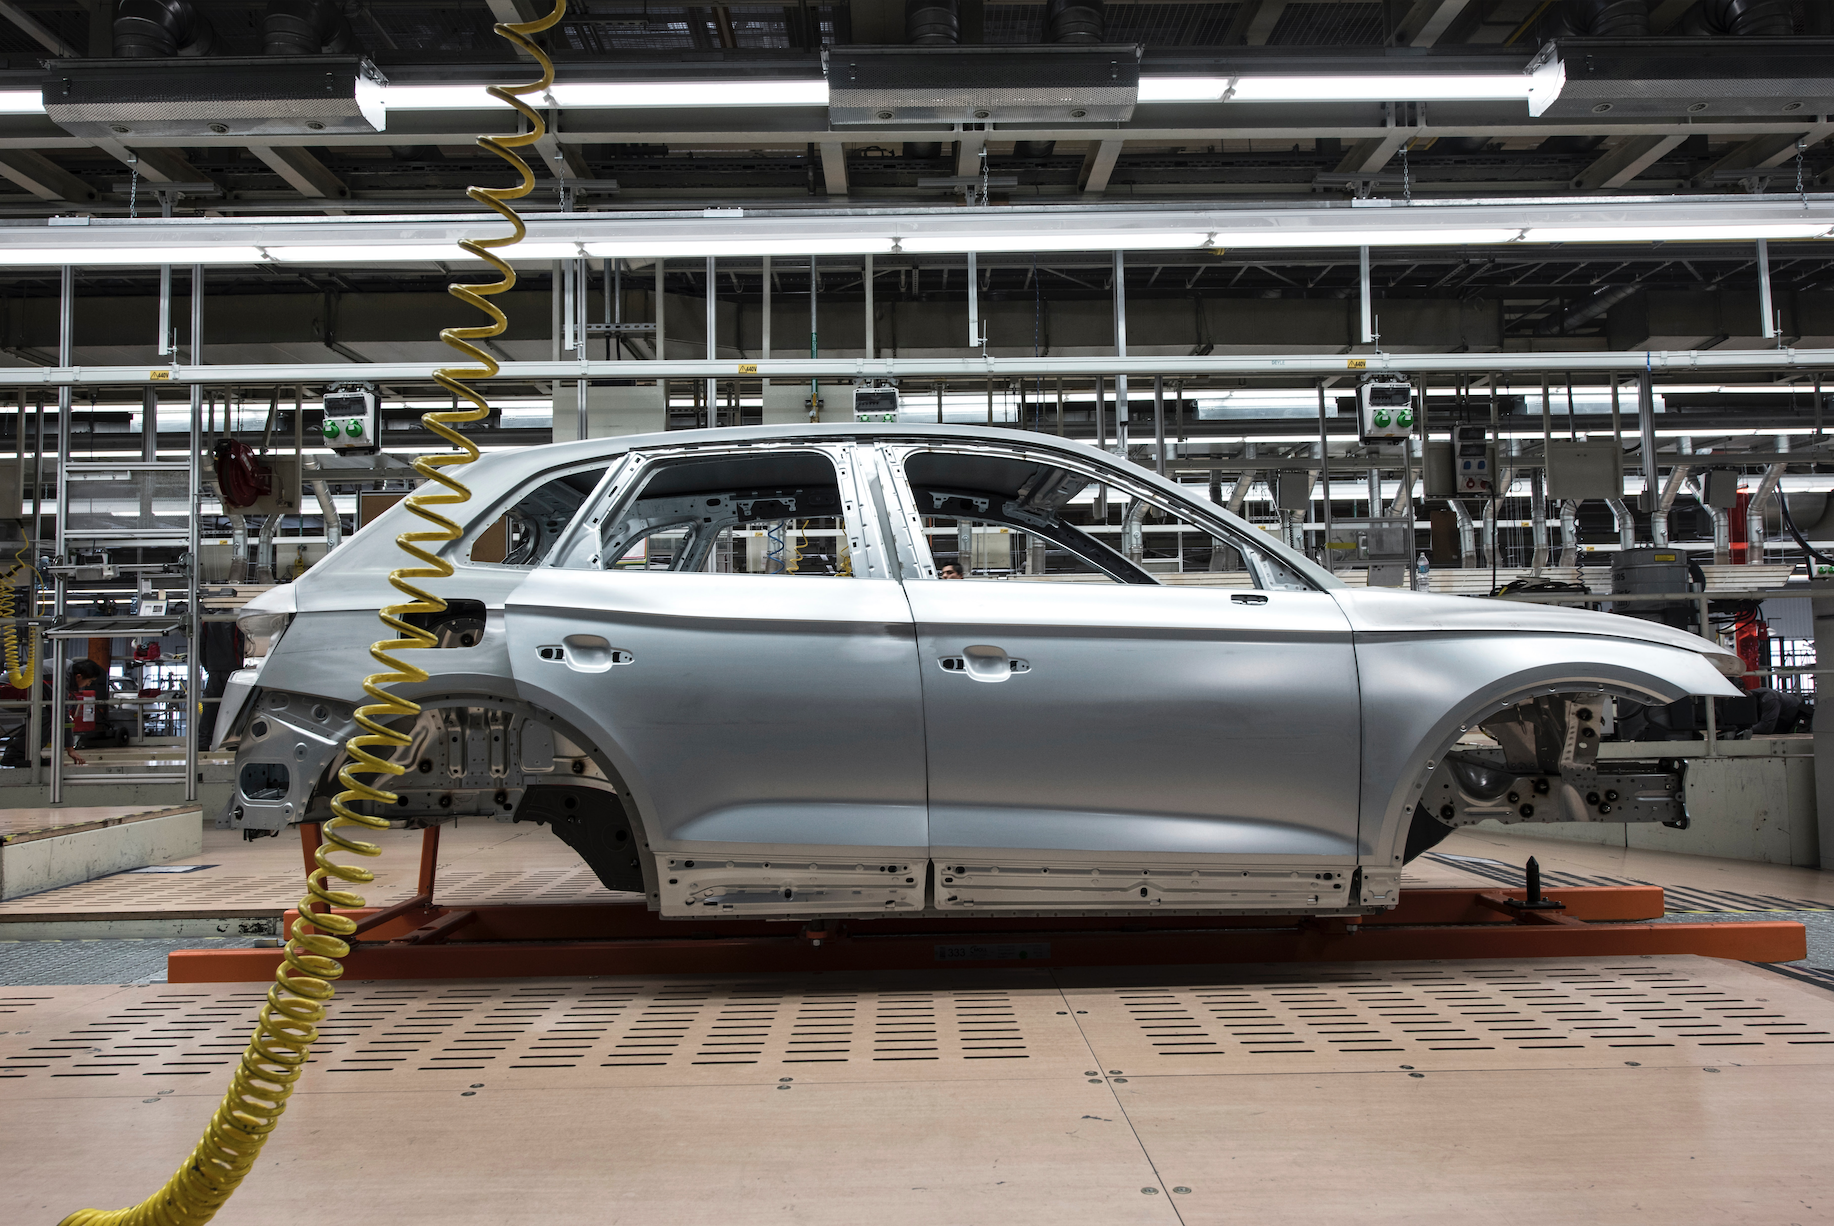
Italian passenger car output decreased significantly year-on-year in June and in the first half of 2022, Kallanish notes from local carmakers’ association Associazione Nazionale Filiera Industria Automobilistica (Anfia) preliminary data.
Production of passenger cars stood at 28,615 units in June, a fall of 18.9% compared to June 2021. Output also fell by 3.7% on-year over the first six months to 239,280 units, against 248,985 units in January-June 2021, Anfia says.
June light commercial vehicle production plummeted 38.7% to 56,250 units, while H1 output dropped by 32% to 121,668 vehicles. Truck production also decreased in June, by 17.8% on-year to 14,779 units, and by 17.1% to 27,860 units in H1.
Total automotive output including heavy-goods vehicles and buses fell by 15.1% on-year in the second quarter to 194,468 vehicles, and by 15.7% to 388,945 units in H1.
Italian passenger car output decreased by 2.1% y-o-y in full-year 2021 to 442,432 units. It stood at 451,718 units in 2020 versus 542,472 units in 2019.
Italy has 23 car production plants. By comparison, Spain has 17 plants, France 31 and Germany 42.
Natalia Capra France


Italian wire rod quietens after July rebound
The Italian wire rod market is becoming quiet as the sector is shutting down for the August break. Prices recovered towards end-July as sales improved over the last two weeks of the month and first days of August.
Sellers who spoke to Kallanish have noticed some return of apparent demand in recent days despite the general level of activity being weaker than in the same period last year. Distributors and drawing mills are now adopting a wait-and-see attitude and all purchasing decisions, even at large buyers, are being put off until September.
Energy prices continue to climb in Italy, eroding producers’ margins, and are seen skyrocketing again in September. Buyers however say they have orders, and some have purchased large quantities of drawing-quality wire rod from North Africa and other regions. At present, imported material is sold at €800-820/tonne ($815-835) cfr Italy for September delivery, but some North African producers are quoting €860-870/t cfr for October delivery, sources say.
Sales prices from local steelmakers remain stable at €870-920/t ex-works for drawing-quality material. Mills are now seeking €920/t ex-works, Kallanish hears.
Natalia Capra France
Benelux scrap prices recover, suppliers target higher levels
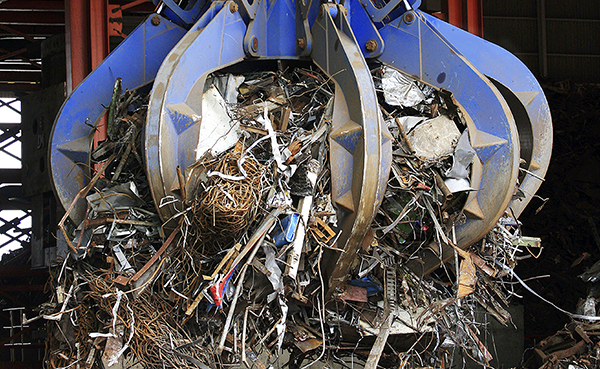
European exporters’ dock prices, which started last week at €280-285/tonne ($286-291) levels, recovered in the second half of the week amid tight supply and the price rise seen in the Turkish scrap market.
Dock prices in the Benelux were seen standing mostly at around €300-305/t ($305-310/t) on Monday.
Amid holidays and suppliers’ higher price expectations, the flow of material remains weak. Given the situation, European suppliers are seen targeting higher prices in Turkey. The number of offers is quite low, however, as most suppliers have backed off from the Turkish market.
A Benelux exporter tells Kallanish: “I have increased my dock price to €305/t this [Monday] morning and could supply only 2,000 tonnes. I think we will have a supply problem even after the holidays. Supply has been tight for a very long time.”
Turkish mills, however, seem reluctant to pay higher prices for scrap amid steel sales that remain insufficient.
On Monday, there was a rumour of a European HMS 1&2 80:20 sale at around $377/t cfr Turkey. This has been confirmed as a sale last week, while the supplier says there are no offers from the EU this week, even at $385/t cfr.
“Some European producers have started inquiring about scrap following their return from the holiday this week. This is likely to result in even more limited supply and will increase the pressure on prices,” says another European scrap exporter.
In India, prices have also increased since last week, mostly due to the price jump in Turkey. Containerised shredded was offered at $480/t cfr levels on Monday.
Burcak Alpman Turkey