


European HRC market remains bullish despite limited real demand
Sentiment in the European hot-rolled coil market remained upbeat on Nov. 10 even though real demand is not recovering and amid concerns related with an increase in domestic production.
Lead times from European mills have increased by a couple of weeks, sources said. However, they claim that this only indicates that automotive companies postponed some deliveries for the first quarter next year and distributors have restocked minimal volumes, while real demand has remained low.
Platts assessed domestic prices for hot-rolled coil in Northwest Europe stable on day at Eur650/mt ex-works Ruhr on Nov. 10.
Deals were heard in the range of Eur650-655/mt ex-works Ruhr, with the majority of transactions reported at Eur650/mt ex-works Ruhr.
Offers and near-term tradable values were heard at Eur680-700/mt ex-works Ruhr.
European steelmakers are expected to keep spot trade limited accepting only higher prices in order to have better position in long-term contracts negotiations. Majority of steelmakers have been aiming for stable prices in contracts for full 2024.
“Mills would rather trade less on spot, but have prices higher to have an argument in contract discussions,” a mill source said.
At least three blast furnaces in Northwest Europe and one in Central Europe are expected to restart production in the coming few months. And market participants have been concerned that the increased availability combined with unchanged real demand would result in price drop.
Platts assessed domestic prices for hot-rolled coil in South Europe down by Eur10/mt on day to Eur640/mt ex-works Italy on Nov. 10.
The assessment was based on tradable values heard at Eur640/mt ex-works Italy and deals reported at Eur650/mt delivered Italy.
Platts is part of S&P Global Commodity Insights.
Author: Maria Tanatar


Italian rerollers increase heavy plate offers
Italian rerollers have increased heavy plate offers in the week to Nov. 10 due to higher costs.
In the European coil market, prices have been bullish supporting the mood change in the plate segment.
Italian mills have been offering heavy plate at Eur750-760/mt ex-works Italy and few deals have been settled at Eur710-740/mt ex-works Italy for the first quarter delivery material.
Platts assessed domestic prices for heavy plate in South Europe up by Eur50/mt on week at Eur725/mt ex-works Italy on Nov. 10.
Although volumes traded at the higher prices have been limited as bigger buyers had settled deals earlier, the rerollers remained firm in their offers and they expect to see further price recovery.
“We drew the line, and we will not sell below certain price,” an Italy-based reroller said. “The next round of slab deals will be settled at higher prices and we have no choice.”
Platts assessed prices for imported slab in South Europe up by $20/mt on week to $600/mt CIF Italy on Nov. 10.
Offers for slab from Asia have been heard at $600/mt CIF Italy and tradable values have been reported at $600-$605/mt CIF Italy.
In Northwest Europe, German mills have been focused on deliveries under long-term and project contracts, their presence in the spot market has remained limited.
Platts assessed domestic prices for heavy plate in Northwest Europe stable on week at Eur790/mt ex-works Ruhr on Nov. 10.
Market participants estimated tradable values at Eur760-800/mt ex-works Ruhr, with majority of data reported at Eur780-800/mt ex-works Ruhr.
A German mill had sold limited volumes of plate at competitive prices in the beginning of the week, but the price was no longer available, market sources said.
Platts is part of S&P Global Commodity Insights.
Author: Maria Tanatar

EUROMETAL at the 16th Blechexpo in Stuttgart
EUROMETAL was present this week at the 16th Blechexpo. This international trade fair for sheet metal processing brought together the main players in the flat steel industry in Stuttgart.
During the visit, the president of EUROMETAL, Fernando Espada, and the General Director, Ricardo Silva, had the opportunity to meet and interact with several members of the federation present at the fair as exhibitors, participants and visitors.
In addition to discovering various news and trends, it was also possible to hear the concerns and challenges faced by some of the service centers and steel traders present at the fair or represented by their national federations.
We took advantage of the fair to also publicize our next Webinar about CBAM on the 20th of November and the Steel Trade Day taking place in Düsseldorf on the 29th and 30th of November.


Producer push for higher HRC prices in Europe hindered by lack of demand
Buying activity in Europe has picked up, however, with some restocking taking place to secure tonnages for first-quarter deliveries in 2024.
The fact that supplies have also been reduced by the production cuts at some steelmakers was also supporting the price rises, sources said.
And lead times at integrated steelmakers have reportedly extended to a minimum of six weeks – up from four-to-six weeks previously.
Most buyers put the workable level at about €640-660 ($684-706) per tonne ex-works, with some transactions in Germany reported within that range on November 9.
Offers from integrated steelmakers were reported at €680-700 per tonne ex-works for January rolling coil, while some mills are considering adding €20-30 per tonne to their offer prices for February.
But some market participants are concerned that the bullish trend will not be sustainable into the first quarter of 2024, because end-user demand is expected to remain low. At the same time, some mills are considering blast-furnace restarts, so HRC availability will increase.
“Salzgitter [is mulling a restart of] its BF A in Q1 2024, and ArcelorMittal’s Bremen BF is expected to come back online in Q4 2023,” a trader source told Fastmarkets.
Fastmarkets calculated its daily steel hot-rolled coil index, domestic, exw Northern Europe, at €650.60 ($695.48) per tonne on November 9, up by €5.47 per tonne from €645.13 per tonne on November 8.
The index was up by €18.97 per tonne week on week and by €30.60 per tonne month on month.
In Southern Europe, Fastmarkets calculated its daily steel hot-rolled coil index, domestic, exw Italy, at €627.92 per tonne on November 9, up by €6.46 per tonne from €621.46 per tonne on November 8.
The Italian index was also up by €12.92 per tonne week on week and up by €22.92 per tonne month on month.
Italian steelmakers were reportedly sold out for December rolling HRC and some temporarily withdrew their offers to reconsider their prices.
Buyers said the tradable level was about €620-630 per tonne ex-works, which is in line with the most recent transactions for December-rolling HRC in Italy, at €635-640 per tonne delivered (equivalent to €620-625 per tonne ex-works), Fastmarkets understands.
Imported HRC remains largely uncompetitive in Europe due to the long lead times and the relatively small gap with European prices.
HRC from Asia was on offer in Europe at €610-620 per tonne CFR to Italy, with most suppliers offering January shipment.
And December-shipment HRC from Turkey was available at €640-650 per tonne CFR to Italy, duty included.
Published by: Julia Bolotova


Prices edge upward in Southern European rebar market; wire rod prices stable
Sources, however, held mixed views regarding price expectations for the remainder of the quarter.
Fastmarkets price assessment for steel reinforcing bar (rebar) domestic, exw Italy was €600-620 ($641-663) per tonne on Wednesday, increasing by €5-10 per tonne from €590-615 per tonne on November 1.
Producers attempted to increase offer prices by around €20 per tonne, but weak demand made the new level unacceptable to buyers and prices remained stable as a result, Fastmarkets heard.
“Producers are trying to increase the price because over the last month they said that they have lost money,” a buyer source said.
“The still mills are offering higher prices this week compared to last week, at around €610-620 per tonne EXW, but I don’t think they are selling much quantity and so the price seems to be stable from last week’s levels,” a second buyer source said.
“Rebar is now at €600-610 per tonne EXW for new offers in the market and it is the intention of mills to raise offer prices to €620-630 per tonne EXW before Christmas holiday closures. However, demand is weaker this week than last week” a third buyer source said.
Some sources held more optimistic outlooks.
“Prices are rising steadily, and clients are buying at new conditions,” a producer source said.
Meanwhile, Fastmarkets’ price assessment for steel reinforcing bar (rebar), domestic, delivered Spain was €590-615 per tonne, stable week on week.
Southern European wire rod
Fastmarkets’ price assessment for steel wire rod (mesh quality) domestic, delivered Southern Europe was €585-600 per tonne on Wednesday, down by €5 per tonne from €590-600 per tonne the week prior.
Prices remained stable in the wire rod market.
Production cuts across European steel mills have altered supply-demand dynamics, sources said.
“While there has been no market recovery or improvement in the economy, there is simply a lack of steel in Europe due to the various production stops at European steel mills. This has increased demand and pushed up prices,” a wire rod producer said.
As a result of import quotas from most countries having been filled, wire rod buyers are more reliant on domestic mills, sources said.
“The most significant import offer came from Turkey, as Turkey still has available quotas to export to Europe. Today it is essentially the only alternative to the European market for Italians. The quotas have blocked further imports from the Far East, Egypt and Algeria. Balkan steel mills today do not have material available for export to Italy due to technical and financial problems,” a wire rod producer source said.
“Many Italian customers, who usually buy most of their material from abroad, in the month of October, and partially also for November, [have] purchased from Italy,” the producer added.
Published by: India-Inés Levy
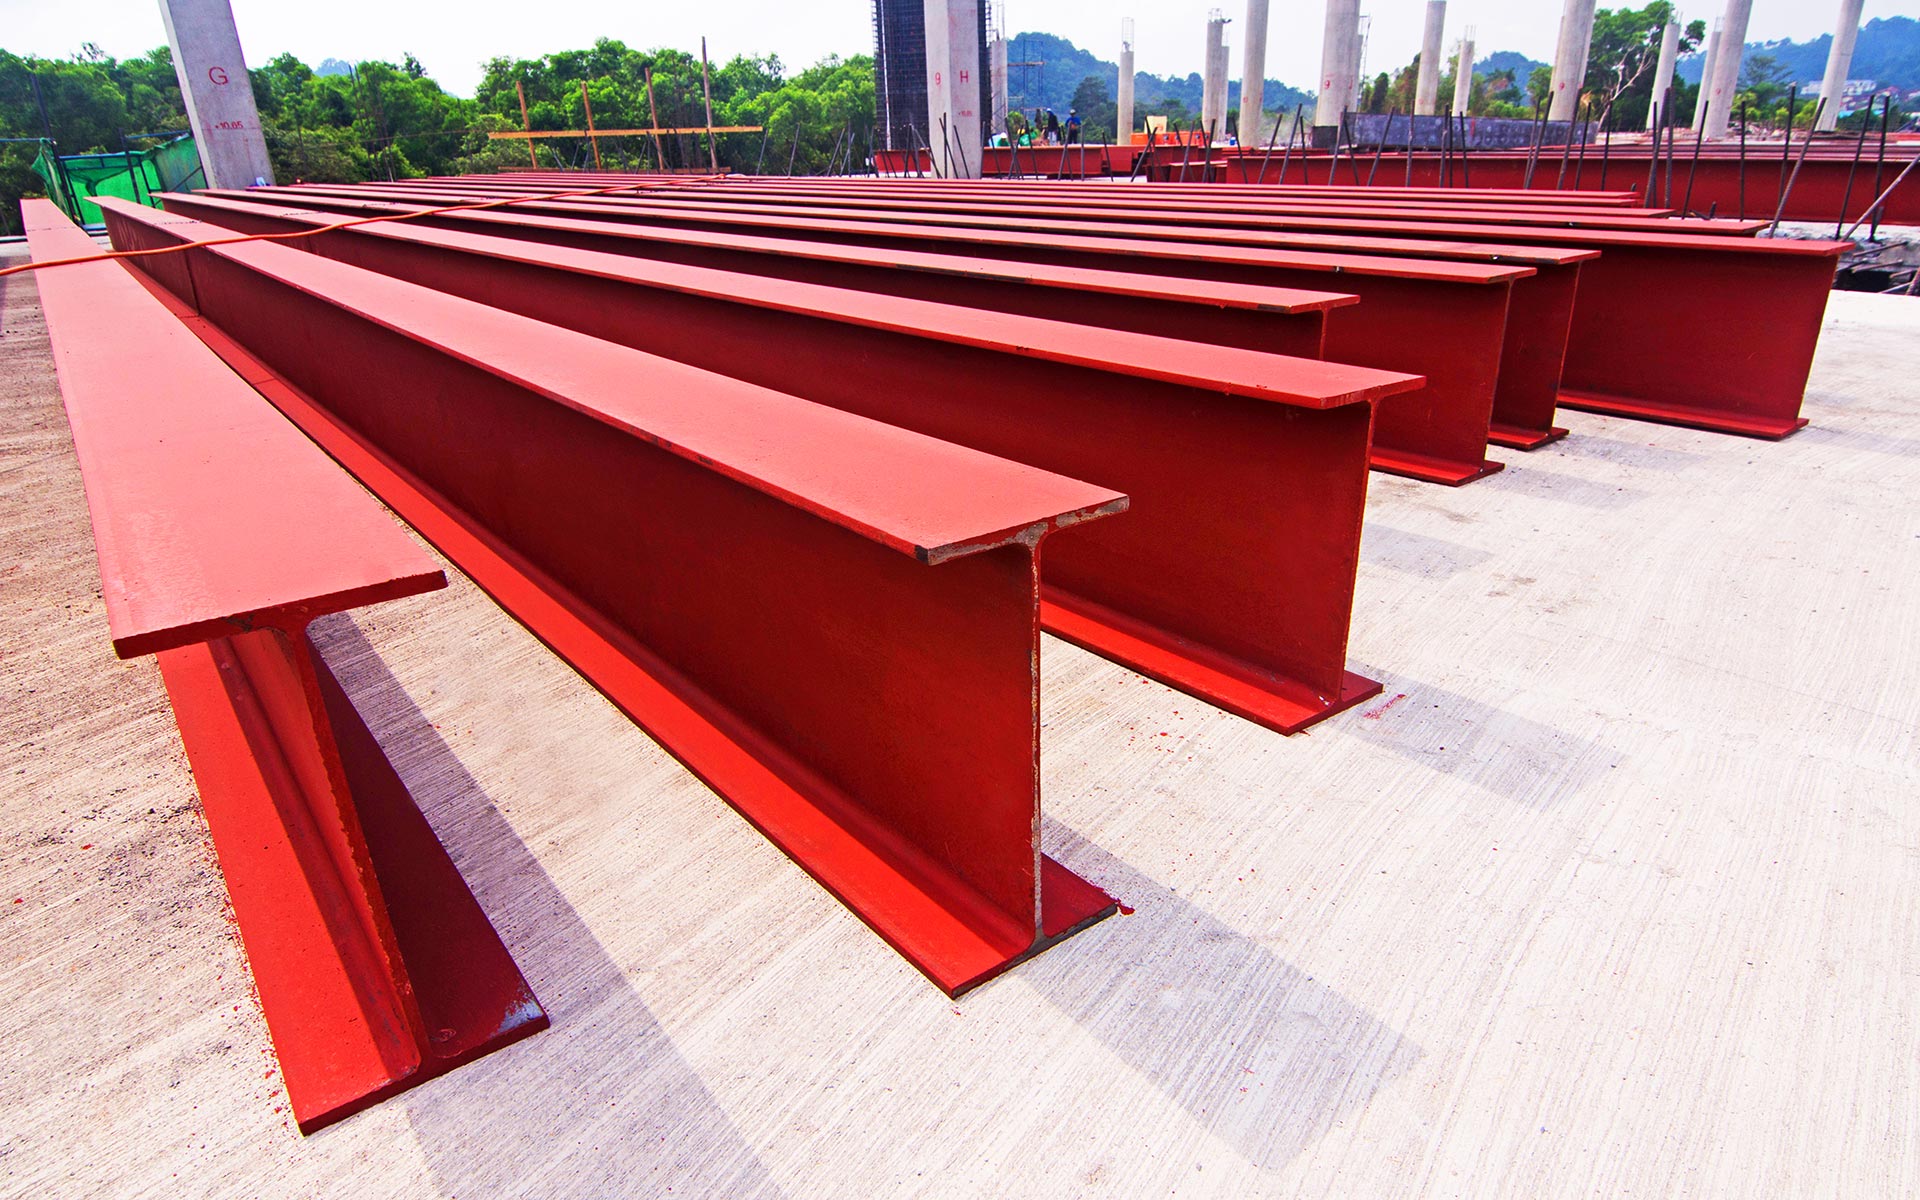
European steel beams market sluggish; prices widen lower
“December rolling is booked in Europe,” said a trader in northern Europe, who expects little purchasing activity in the remainder of 2023.
Fastmarkets heard of offers in a range from €730-750 in the past seven days that were only “partly booked.”
Fastmarkets’ weekly price assessment for steel beams, domestic, delivered Northern Europe was €730-750 ($780-802) per tonne on Wednesday, widening downward from €740-750 per tonne a week earlier.
Similarly, Fastmarkets’ weekly price assessment for steel beams, domestic, delivered Southern Europe was €730-750 per tonne on Wednesday, widening downward week on week from €740-750 per tonne.
Sources have reported production cuts and mill shutdowns in recent weeks while consumption from the construction sector has weakened against a negative macroeconomic backdrop.
Weak demand has also muted the import market.
Talks between industry participants were also said to be taking place at the Blechexpo international sheet metal trade fair, which is taking place over November 7-10.
Scrap costs in Turkey’s bellwether market rose despite poor sales of finished steel.
Fastmarkets’ calculation of its daily index for steel scrap HMS 1&2 (80:20 mix) North Europe origin, cfr Turkey was $373.15 per tonne on Wednesday, up by $15.23 per tonne week on week from $357.93 per tonne.
Published by: Holly Chant