


EU imposes definitive Chinese organic coated steel duties
The European Commission has imposed two separate duties, a definitive anti-dumping duty and definitive countervailing duties, on imports of certain organic coated steel products from China, following expiry reviews, Kallanish notes.
The AD (regulation 2025/1508) and countervailing (regulation 2025/1506) measures cover flat-rolled products of non-alloy or alloy steel, excluding stainless steel, that are painted, varnished, or coated with plastics on at least one side. They exclude sandwich panels used in construction, products with a final zinc-dust coating (containing 70% or more zinc by weight), and those with metallic coatings of chromium or tin.
New Chinese exporters who did not export during the original investigation period (October 2010-September 2011), are unrelated to duty-imposed exporters, and can prove current or imminent exports, may be added at the 13.6% weighted average anti-dumping duty rate applied to cooperating non-sampled companies.
The AD regulation stipulates that if countervailing duties under separate regulation are modified or removed, the anti-dumping duties will be adjusted proportionally, respecting the limits of the dumping or injury margin established per company.
The countervailing regulation allows for a future upward adjustment of these duties if the parallel anti-dumping duties are altered or withdrawn, to ensure combined duty coverage does not fall below the level of injury or dumping margins. In cases where the countervailing duty has been subtracted from the anti-dumping duty, refund claims will trigger a reassessment of the applicable dumping margin.
| Company | Definitive countervailing duty (%) | Definitive anti-dumping duty % |
| Union Steel China | 13.7 | 0 |
| Zhangjiagang Panhua Steel Strip Co., Ltd, Chongqing Wanda Steel Strip Co., Ltd, and Zhangjiagang Free Trade Zone Jiaxinda International Trade Co., Ltd. | 29.7 | 26.1 |
| Zhejiang Huadong Light Steel Building Material Co. Ltd and Hangzhou P.R.P.T. Metal Material Company, Ltd. | 23.8 | 5.9 |
| Angang Steel Company Limited | 26.8 | 16.2 |
| Anyang Iron Steel Co., Ltd. | 26.8 | 0 |
| Baoshan Iron & Steel Co., Ltd. | 26.8 | 0 |
| Baoutou City Jialong Metal Works Co.,Ltd. | 26.8 | 16.2 |
| Changshu Everbright Material Technology Co.,Ltd. | 26.8 | 16.2 |
| Changzhou Changsong Metal Composite Material Co.,Ltd. | 26,.8 | 16.2 |
| Cibao Modern Steel Sheet Jiangsu Co., Ltd. | 26.8 | 0 |
| Inner Mongolia Baotou Steel Union Co.,Ltd. | 26.8 | 16.2 |
| Jiangyin Ninesky Technology Co.,Ltd. | 26.8 | 0 |
| Jiangyin Zhongjiang Prepainted Steel Mfg Co.,Ltd. | 26.8 | 0 |
| Jigang Group Co., Ltd. | 26.8 | 16.2 |
| Maanshan Iron&Steel Company Limited | 26.8 | 16.2 |
| Qingdao Hangang Color Coated Sheet Co., Ltd. | 26.8 | 16.2 |
| Shandong Guanzhou Co., Ltd. | 26.8 | 16.2 |
| Shenzen Sino Master Steel Sheet Co.,Ltd. | 26.8 | 16.2 |
| Tangshan Iron And Steel Group Co.,Ltd. | 26.8 | 16.2 |
| Tianjin Xinyu Color Plate Co.,Ltd. | 26.8 | 16.2 |
| Wuhan Iron And Steel Company Limited | 26.8 | 16.2 |
| Wuxi Zhongcai New Materials Co.,Ltd. | 26.8 | 0 |
| Xinyu Iron And Steel Co.,Ltd. | 26.8 | 0 |
| Zhejiang Tiannu Color Steel Co., Ltd. | 26.8 | 16.2 |
| All other imports originating in the People’s Republic of China | 44.7 | 13.6 |
Source: Official Journal of the European Union
Elina Virchenko Ukraine

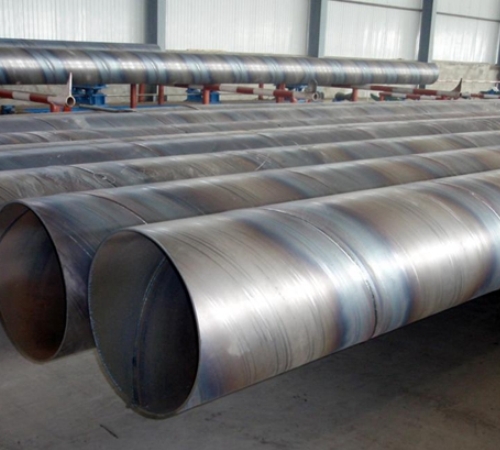
Italian welded tube prices begin to rise
The recent downward trend in Italian welded tube prices is showing signs of reversal, aligning with a broader wave of price increases across coils, derivatives, and other flat steel products.
According to a re-roller who spoke to Kallanish, the market is experiencing a rise in apparent demand, largely driven by growing uncertainty surrounding buyers’ ability to secure material from the import market. This hesitancy stems from evolving trade barriers, including the Carbon Border Adjustment Mechanism (CBAM) and impending safeguard replacement measures. These are prompting many buyers to shift back towards domestic and EU-based sourcing.
As a result, welded tube prices are beginning to tick up and may firm further in the coming weeks as supply tightens and purchasing activity resumes. With demand showing early signs of recovery and import uncertainty, Italian re-rollers are actively reducing welded tube discounts, which had reached 42-43 points in July.
Before the upcoming August production stoppages, they aim to bring discounts down to 40 points. This move reflects an effort to restore margin levels amid rising input costs and strengthening coil prices.
Another welded tube seller notes the urgent need to reach “a sustainable discount level that matches the input cost of increasing hot rolled coils”, driven by market tightening and regulatory pressures such as CBAM.
Last week ArcelorMittal and other EU producers including in Italy increased hot and cold rolled, as well as hot-dipped galvanised coil prices by €20-30/tonne ($23-34) across Europe, effective for new contracts covering the remaining third-quarter delivery slots and October shipments.
The revised base price for HRC is now set at €590/t delivered, using the German market as a reference point for northern Europe. In southern Europe, asking prices are at €580/t base delivered.
Natalia Capra France

Spain’s rebar producers raise prices before maintenance
Spanish rebar prices have risen since mid-July, market sources tell Kallanish.
Traders confirm that rebar mills in Spain increased their prices, driven by the start of scheduled maintenance periods. The rise is slightly above other European markets, taking advantage of the rebound in demand from the construction sector.
“Longs product output is expected to drop in the coming weeks, and producers have raised prices ahead of their planned shutdowns,” says one seller. “Even with high prices, demand remains strong.”
Market sentiment is positive heading into the summer, supported by the recovery of construction activity.
“Activity has picked up in June and July, mainly boosted by public and residential sector works,” a representative from a local construction firm notes. “We’re in a period of strong activity, with more building permits being granted. Private construction projects are also contributing to the sector’s positive momentum.”
Another participant points out that the local market has become more predictable and stable, although a slight price adjustment by the end of this month, of €5-10/tonne ($5.87-11.75/t), would be no surprise.
According to Spanish Chamber of Commerce data, the monthly index for Spanish domestic rebar prices (B-500 SD 12 meter/12mm) increased for a seventh consecutive month in July. The index stood at 198.08, up 1.23% over June. It was also 13% higher year-on-year. The index is based on a value of 100 in 2014.
Current offers for 16mm rebar in Spain are at €373-378/t base. Including €262/t size extras and loading expenses, transaction values are at €635-640/t ex-works.
Todor Kirkov Bulgaria