Balkan steel market at a turning point: Interview on demand, trade and competitiveness
Liberty Steel Balkans Sales Manager Dusan Jovanoski said the Balkan steel market is entering a new era, with trade policies, CBAM, energy costs and decarbonisation increasingly shaping competitive conditions. Jovanoski noted that 2027 will bring new challenges and opportunities, with companies that adapt quickly to changing market conditions gaining a competitive advantage.
“EU and non-EU countries in the Balkan steel market will increasingly diverge”
As trade measures, CBAM, energy costs and decarbonisation investments reshape competitive conditions in the European steel market, Balkan countries are also being directly affected by this transformation. In particular, regulatory differences between EU and non-EU Balkan countries are leading to an increasingly visible divergence in sourcing and purchasing strategies.
Speaking to SteelRadar, Dusan Jovanoski, Liberty Steel’s Sales Manager for the Balkans, assessed current market conditions in North Macedonia and the Balkans, purchasing behaviour, Türkiye’s position in the region and decarbonisation. Jovanoski said he does not expect 2027 to be an easy year for the industry, adding that companies capable of adapting quickly to the new market structure from commercial, operational and technological perspectives will be in a stronger position.
First of all, could you tell us about yourself?
Throughout my 12 years of experience in the steel industry, including roles at ArcelorMittal and Liberty Steel Group, I have had the opportunity to work across different markets and closely follow the structural changes taking place in the European and Balkan steel industries. For the past five years, I have served as Sales Manager for the Balkan region. This combination of commercial and strategic experience has given me a broad perspective on the development of the regional steel market and the challenges faced by producers, traders and customers.
Western Balkans could become an alternative market
How do you assess the current steel market in North Macedonia and the Balkans? What do you see as the main factors currently affecting demand and prices?
Although North Macedonia is a relatively small market, its position within the regional steel industry is more important than its domestic consumption might suggest. The country has important steel producers operating in both flat and long products. Liberty Skopje is a significant producer of coated and cold-rolled flat products, while Makstil is one of the leading producers of quarto plate. Dojran Steel operates in the long products segment.
The presence of these producers makes an important contribution to steel demand and industrial activity in Macedonia. However, due to limited domestic consumption, a significant share of production is exported, making the country highly exposed to developments in the broader Balkan and European markets.
One of the characteristics of the Macedonian market is its relatively open trading environment. Depending on the product and origin, companies can import from third countries without facing the same level of trade restrictions applied in the EU, such as anti-dumping measures or quotas. As a result, suppliers from China, Türkiye, Ukraine and other origins play an important role in the market.
For the time being, this has contributed to relatively stable supply and demand conditions across Macedonia and the wider Western Balkans, including Serbia, Bosnia and Herzegovina, Albania, Kosovo and Montenegro. However, I believe the market is approaching an important turning point.
The new EU steel trade regime, which entered into force on 1 July 2026, introduced an annual duty-free quota of 18.3 million tonnes for covered steel products, while volumes exceeding the quota are subject to a 50% duty. This represents a significant change in Europe’s trading environment.
The implications for the Balkans could be considerable. Suppliers that lose or face restricted access to EU markets will naturally look for alternative markets. Due to its geographical proximity, logistical advantages and relatively open trading environment, the Western Balkans represent a natural alternative market. Türkiye, in particular, is likely to strengthen its presence in the region.
This additional competition could put downward pressure on prices even at a time when certain production, energy and logistics costs continue to rise. As a result, price movements in the Balkans may increasingly diverge from developments in EU markets.
Inventories and speculation influence purchasing behaviour
What changes have you observed in buyers’ purchasing behaviour recently? Are companies restocking, or are they purchasing mainly according to short-term requirements?
Another important development is the difference in purchasing behaviour between EU and non-EU Balkan countries.
The Balkan market is effectively divided between EU member states and non-EU countries, and purchasing patterns are increasingly diverging due to their different regulatory environments. CBAM and the new EU steel quotas have had a particularly strong impact on purchasing decisions in countries such as Greece and Bulgaria, which are important markets for Turkish suppliers.
Ahead of the implementation of CBAM, we saw significant speculative purchasing. Customers with sufficient financial capacity increased their inventories substantially. In some cases, they purchased enough material to cover six to twelve months of projected requirements. A similar situation occurred before the introduction of the new quota system in the third quarter of 2026.
Therefore, apparent demand during certain periods was stronger than underlying consumption would suggest. In reality, part of this increase was driven by inventory accumulation and speculation rather than genuine growth in end-user demand.
This distinction is very important when assessing the market. Higher shipments do not necessarily mean higher consumption. In some cases, demand was simply brought forward as customers sought to secure material ahead of regulatory changes.
Financing is one of the main challenges to decarbonisation
Sustainability and decarbonisation are becoming increasingly important in the European steel industry. How do you think this transformation will affect competitiveness, investment requirements and trade for steel producers and processors in the Balkans?
Decarbonisation will be one of the biggest structural challenges facing the Balkan steel industry over the next decade.
The direction is clear. Traditional blast furnace/BOF production is coming under increasing pressure, while electric arc furnaces (EAF), DRI and other low-carbon technologies are becoming increasingly important. European producers are already undertaking major transformation projects. According to EUROFER’s 2026 industry report, there are 20 EAF projects representing a total capacity of 44.1 million tonnes and 13 DRI projects representing 26.9 million tonnes of capacity for the 2026-2030 period, although some projects remain on hold.
For the Balkans, the main challenge is that the financial capacity of many countries and companies is significantly more limited compared with the major economies of Western Europe. Governments are generally not in a position to support greenfield EAF-DRI investments on the same scale seen in some developed EU markets.
This creates a serious competitiveness issue. Producers in non-EU Balkan countries may face rising costs due to CBAM, quotas, carbon requirements and the broader transition towards low-carbon production, while not having access to the same level of financial support available to EU producers.
At the same time, EU producers are increasingly protected by Europe’s trade policies. The new EU Steel Regulation is clearly designed to protect the European steel industry from the effects of global overcapacity and trade diversion.
Therefore, having a free trade agreement with the EU alone may not be sufficient to guarantee long-term competitiveness. Countries such as North Macedonia and Serbia may have preferential market access, but producers will still need to address fundamental issues such as energy costs, carbon intensity, technology and investment.
Energy is particularly important in this context. The European steel industry continues to identify high and volatile electricity prices as one of the biggest obstacles to industrial competitiveness, electrification and decarbonisation.
For Balkan producers, access to competitively priced energy could become one of the key factors determining which companies remain competitive in European markets.
Türkiye remains among North Macedonia’s strong suppliers
Türkiye is one of North Macedonia’s important steel suppliers. How do you assess the current steel trade between Türkiye and North Macedonia?
Türkiye is already one of North Macedonia’s important trading partners in steel, and I expect this relationship to remain important.
Turkish steel producers have a particularly strong position in hot-rolled coil (HRC), including supplies to tube producers and steel service centres. Their competitiveness is supported by attractive pricing and well-established logistics to the Balkan region.
However, it is important to correctly understand who Turkish steel is competing against. In many cases, the main competitor for Turkish producers is not European producers but imports from China, which can be even more aggressive in terms of pricing.
This is particularly important in Macedonia and other non-EU Balkan markets, where purchasing decisions remain highly price-sensitive. As a result, lower-cost suppliers from China and Türkiye remain in a strong position.
At the same time, domestic producers continue to play an important role. In Macedonia, Liberty Skopje holds an important position in supplying coated products to the local market alongside imported material. This creates a market structure in which domestic production, European supply and competitively priced third-country imports coexist.
Geopolitical tensions affect costs and supply chains
How are wars, political tensions and economic uncertainties around the world affecting the steel industry in North Macedonia and the Balkans?
The geopolitical environment has also become an important factor for the steel industry. Wars, political tensions, sanctions, trade restrictions and economic uncertainty have a direct impact on production costs and supply chains. Energy prices, freight costs, raw material availability and logistics conditions can be affected very quickly by geopolitical developments.
For Balkan producers, this creates an additional competitiveness challenge.
Countries that cannot secure energy at competitive prices may find it increasingly difficult to compete with producers in regions where energy and other input costs are lower.
Therefore, the issue is no longer simply whether demand exists. It is becoming increasingly important whether producers can manufacture and deliver steel at a competitive total cost while meeting increasingly stringent environmental and trade requirements.
“Product availability will be almost as important as price”
Looking ahead to the remainder of 2026 and towards 2027, what are your expectations for steel prices, demand and overall market conditions in North Macedonia and the Balkans?
Looking ahead, I expect the steel market to increasingly diverge between EU and non-EU countries.
In EU markets, I expect prices to receive stronger upward support as a result of the new trade measures, more restricted import opportunities and, hopefully, an improvement in underlying demand. The EU’s latest steel data illustrate how challenging the recent period has been: although European steel demand has started to show a limited recovery, production has fallen to record-low levels while imports have captured an unprecedented share of the market.
However, the situation in non-EU Balkan markets could become much more complex. Producers that lose part of their traditional EU markets may redirect volumes towards neighbouring countries, increasing competition and placing additional pressure on prices. Therefore, price and demand trends may not move in the same direction across the entire region.
Despite this, I expect real demand to improve gradually. Government-supported infrastructure projects are likely to provide an important source of consumption, particularly in countries where construction and infrastructure investment have remained relatively weak in recent years.
Another important development will be how customers adapt to the new EU quota and CBAM environment. I expect buyers’ purchasing strategies to become increasingly sophisticated. We may see restocking increase towards the end of quota periods, followed by very rapid customs clearance and purchasing activity when new quota periods open. In this environment, production reliability and timely delivery will become increasingly important. Product availability will be almost as important as price.
At the same time, some customers will continue sourcing from third countries and accepting the risks associated with quota duties because the price difference between European and imported steel can be extremely high. For certain products and under certain market conditions, the difference can reach EUR 300-400 per tonne. This is a gap that many customers cannot ignore.
The regulatory framework is also still evolving. The EU is reviewing the scope of the new Steel Regulation, with the Commission expected to complete its assessment by the end of 2026. Implementation of the “melt and pour” requirement will add another layer of complexity to international steel supply chains, particularly where raw materials and semi-finished products pass through multiple countries.
CBAM also entered its definitive implementation phase on 1 January 2026. Carbon costs are therefore no longer merely a future regulatory issue but are becoming a tangible commercial factor. In August 2026, the European Commission continued to update technical parameters for implementation, including default values for the definitive period.
“2027 will come with new challanges and opportunites”
Overall, I believe the Balkan steel market is entering a new era. For many years, price, availability and logistics were the main factors determining purchasing decisions. Going forward, trade policies, carbon intensity, quota availability, energy costs and the origin of raw materials will become equally important.
For Balkan producers, the biggest challenge will be maintaining competitiveness while investing in decarbonisation and adapting to an increasingly protectionist and more heavily regulated European market.
For buyers, the key challenge will be balancing price with security of supply and regulatory risk. For producers, success will increasingly depend on operational efficiency, reliable delivery, competitive energy costs, technological investment and the ability to quickly understand and adapt to changing trade rules

Outokumpu: Impact of EU steel measures limited by cost pressures

Voestalpine advances construction of new EAF unit at Donawitz
Austrian steelmaker voestalpine has announced that construction of its new electric arc furnace unit at the Donawitz site is progressing, with key components of the two furnaces, EAF 1 and EAF 2, now installed.
According to the company, the lower and upper furnace vessels and furnace covers have already been installed. Heavy-duty assembly of the rotating towers, including lifting cylinders and electrode support arms for both electric arc furnaces, has also been completed. These components will form the central melting unit of the new production line.
Electric arcs to reach temperatures of up to 15,000°C
Each electric arc furnace will use three large graphite electrodes powered by the three phases of the electrical grid to generate electric arcs reaching temperatures of up to 15,000°C. The resulting energy will be used to melt the feedstock for subsequent steelmaking processes.
The EAFs will primarily use steel scrap, while hot briquetted iron (HBI) will also be used to improve steel quality and maintain a consistent chemical composition. Depending on the required steel grade, lime, dolomite, carbon and alloying elements including chromium, nickel, molybdenum and manganese may also be added during melting.
Work on scrap transfer system progresses
Meanwhile, work on the scrap transfer system is also progressing. Scrap transfer cars will transport material from the scrap yard to the EAF unit, with scrap baskets moving to the furnace hall through an underground conveyor system. The scrap baskets have already been fully assembled and positioned on the transfer cars.
Voestalpine stated that the new EAF unit, comprising the two furnaces, will form the basis for modern and resource-efficient steel production at Donawitz.
Author: SteelOrbis Editorial Team
EUROMETAL warns regulatory gap threatens EU steel-intensive manufacturing
EUROMETAL has warned that a regulatory gap is putting European manufacturers of steel-intensive products at a competitive disadvantage against non-EU suppliers. While imported steel is subject to trade measures and carbon-related costs, finished goods manufactured outside the EU do not necessarily face equivalent obligations when entering the bloc.
The association will bring the issue to the attention of EU policymakers in Brussels on September 7 through its European Convoy for Industrial Competitiveness, calling for a level playing field across the entire manufacturing value chain.
According to EUROMETAL, the imbalance stems from the different treatment applied to steel imports and finished steel-intensive products manufactured outside the EU. Steel entering the European market is subject to quotas, trade measures and carbon costs under the Carbon Border Adjustment Mechanism (CBAM), while finished products from third countries may enter the bloc without facing equivalent trade and carbon-related requirements.
As a result, a European manufacturer producing a steel-based product may face higher regulatory and decarbonization costs than a non-EU competitor exporting the finished product to the European market. EUROMETAL argues that this imbalance weakens the competitiveness of European manufacturing and may encourage companies to relocate production outside the EU.
The association warned that, if the trend continues, it could lead to plant closures and further production relocation, affecting employment, investment, industrial know-how, value creation and demand for European steel. The gradual erosion of Europe’s manufacturing base could also undermine strategic industrial capabilities needed for infrastructure, defence and the green transition.
EUROMETAL is therefore calling for a level playing field across the entire manufacturing value chain, arguing that European industrial policy should prevent regulatory requirements on steel and domestic manufacturing from translating into a competitive advantage for finished products imported from third countries.
The association will take this message to Brussels on September 7, when companies, workers, business associations and other industry representatives from across Europe will participate in the European Convoy for Industrial Competitiveness.
Author: SteelOrbis Editorial Team
EU sets melt-and-pour rules with one-year transition
The European Commission has adopted new melt-and-pour evidence requirements for steel imports covered by the EU Steel Regulation. These require importers from 1 October to provide a Mill Test Certificate (MTC) stating the melt-and-pour country and heat number, Kallanish notes from the Official Journal of the European Union dated 31 August.
If the MTC is missing either of these details, customs authorities may accept complementary evidence containing the missing information. This can include invoices, delivery notes, quality certificates, purchase orders or contracts, supplier declarations, cost accounting and production documents, exporting-country customs documents, commercial correspondence or production descriptions.
During a one-year transition period from 1 October 2026 to 30 September 2027, the same documents may also be accepted as standalone evidence where no MTC can be provided, as long as they contain both the country of melt and pour and the heat number. After 30 September 2027, this standalone-document provision expires.
Where complementary or standalone evidence is submitted, customs authorities must carry out documentary checks.
The country of melt and pour must be declared through TARIC document codes.
Failure to provide appropriate and verifiable evidence will result in the import being rejected.
Author: Elina Virchenko
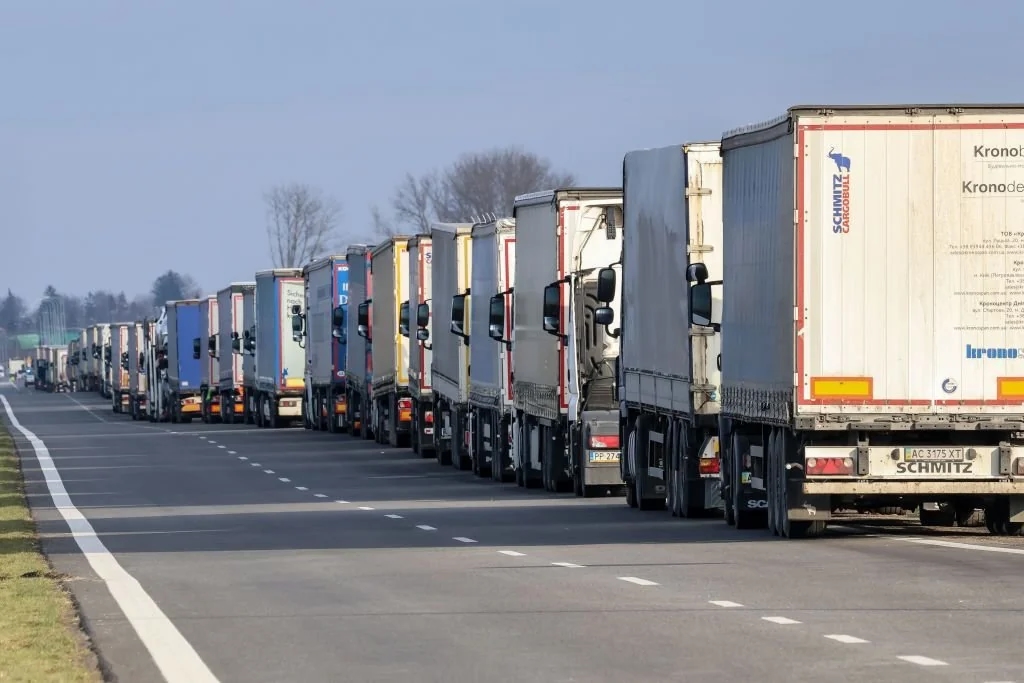
Trucks demonstrate in Brussels to save EU manufacturing
A truck convoy will gather in Brussels on 7 September to raise awareness of the increasing pressure on Europe’s steel and metal value chains.
The rally is organised by distributors association EUROMETAL to emphasise that Europe must preserve the industrial value chains on which its low-emission transition, strategic autonomy, employment and resilience are based. It will assemble representatives of Europe’s steel distribution, processing and downstream manufacturing industries at the event.
“The truck convoy is not a protest against Europe. It is a demonstration for a strong European industrial base, fair competition, climate credibility and secure supply chains,” EUROMETAL says.
The core of the protest is against the omission so far of steel-based imports from the Carbon Border Adjustment Mechanism (CBAM), which is confined to immediate mill products.
Steel-intensive manufactured goods and steel derivatives are increasingly entering the European market without equivalent trade, origin, carbon and regulatory obligations, EUROMETAL notes. This shifts production, jobs and emissions out of Europe while weakening the established domestic industrial base, EUROMETAL warns.
The association has repeatedly pointed out the dangers of this loophole, most recently in early June at Kallanish’s Europe Steel Markets conference in Vienna.
According to a EUROMETAL basis paper, the examined shortlist of critical steel derivatives imports increased from 3.774 million tonnes in 2010 to 8.050mt in 2024. Particularly dynamic growth is visible in rail technology, electrical machinery, automotive components, metal furniture and prefabricated constructions, EUROMETAL says.
The basis paper also highlights the risks of international trade diversion. Without appropriate EU action, Europe risks becoming a destination market for diverted overcapacity and carbon-intensive steel-based products.
“A visible truck convoy in Brussels is therefore necessary to show that this is not an abstract policy debate. It affects real companies, real drivers, real workers and real communities,” EUROMETAL concludes.
Christian Koehl Germany
Tuflesa signs agreement with SMS group to modernize its ERW pipe line
EU clarifies rules for proving the “melt and pour” country for steel imports
Interpipe to increase production at former ArcelorMittal plant in Romania
