


Huta Częstochowa and Hyundai Rotem sign MoU for armor steel supply
Polish steelmaker Huta Częstochowa has signed a memorandum of understanding with South Korean defense manufacturer Hyundai Rotem to assess the potential supply of locally produced armor steel plates for K2PL tanks and other military vehicles.
The agreement establishes a framework for further technical and commercial discussions between the companies regarding the possible use of Huta Częstochowa’s armor steel in Hyundai Rotem’s military vehicle programs.
Companies to assess technical suitability of armor steel
Under the MoU, Hyundai Rotem and Huta Częstochowa will jointly evaluate whether the Polish producer can supply armor steel plates for K2PL tanks, support vehicles and other military platforms. The assessment will include whether the steel products meet the applicable technical and quality requirements.
The agreement forms part of Hyundai Rotem’s efforts to increase the participation of Polish industry in its K2 tank program. Under the second implementing contract, 61 K2PL tanks are scheduled to be manufactured in Poland, while the contract also covers more than 80 specialized support vehicles. Technology transfer and localization are key elements of the program, with Polish manufacturers expected to progressively develop capabilities for the production of hulls, turrets and other major components.
Huta Częstochowa expands role in Polish defense industry
Huta Częstochowa obtained a license from Poland’s Ministry of the Interior and Administration in April this year allowing it to manufacture and trade products and technologies intended for military and police applications. In May, shares in the steelmaker were acquired by Poland’s Military Property Agency and Węglokoks
Huta Częstochowa management board president Adrian Sienicki said the company’s participation in the localization of K2 tank production and maintenance demonstrates its production capabilities and potential to supply Poland’s defense sector.

Former Ilva’s hot-end shutdown revives concerns over Italy’s reliance on steel imports
Italian metals distributors, traders and processors’ association Assofermet has expressed “deep concern” over the potential impact on the domestic steel supply chain following the Milan Court of Appeal’s decision to reject a request to suspend the ruling requiring the shutdown of the hot-end operations at the former Ilva steelworks in Taranto by the end of October.
Following the decision, Acciaierie d’Italia (ADI) plans to begin cooling down its blast furnaces as early as September 16. According to the company’s schedule, the process will start with BF No. 1, which is currently being kept in preheating mode, followed by BF No. 4, which is currently idle, and finally BF No. 2, the only blast furnace currently in operation. According to the technical assessments cited by Assofermet, once the cooling process has started, restarting the blast furnaces would be extremely complex and difficult to sustain from both a technical and economic standpoint.
Assofermet warns of risks to domestic steel capacity and security of supply
Assofermet highlighted the strategic importance of the Taranto site, which is currently Italy’s only integrated steelworks capable of producing primary steel from iron ore. The plant is also at the heart of a broader industrial network, supplying coils and semi-finished products both to the market and for further processing at the company’s facilities in Genoa and Novi Ligure.
The association, and in particular steel distributors, service centers and flat steel pre-processors that have historically sourced material from Taranto, warned that the shutdown of the hot end could lead to a structural reduction in Italy’s steelmaking capacity and increase the country’s reliance on imports. According to Assofermet, the consequences would extend beyond material availability, affecting procurement costs, security of supply and the competitiveness of downstream manufacturers.
The issue is particularly significant against the current European trade backdrop. Assofermet noted that, as of July 1, the new EU steel safeguard regime has significantly reduced available import quotas and raised the duty on out-of-quota volumes to 50 percent. According to the association, a simultaneous reduction in domestic production capacity and more restricted access to non-EU supplies could therefore create significant pressure on steel availability for Italy’s manufacturing sector.
The impact would be particularly relevant for strategic downstream sectors including automotive, household appliances, mechanical engineering, energy and construction, all of which depend on a reliable supply of steel and high-quality steel products.
Former Ilva remains at center of Italy’s industrial debate
As previously reported by SteelOrbis, Federacciai and 14 Italian steel producers had submitted an expression of interest for the former Ilva’s cold rolling facilities, while excluding the hot-end operations from the scope of their proposal. At the same time, Indian steelmaker Jindal had confirmed its interest in acquiring the former Ilva assets as a whole, including the hot-end operations.
Against this backdrop, Assofermet has called on the Italian government to act urgently to identify a credible long-term industrial solution capable of combining health and environmental protection, decarbonization, employment safeguards and continuity of domestic steel production. The association stressed that Italy cannot afford to give up domestic production of high-quality steel at a time when Europe is seeking to strengthen its industrial autonomy and economic security.

SSUK could restart EAF in December amid nationalization plans
The UK government plans to nationalize troubled Speciality Steel UK (SSUK) through a public acquisition, securing the future of another electric-arc furnace (EAF) in the country, the Department for Business, Innovation, Science and Trade said on Monday September 14.
The decision, which comes two months after the UK government nationalized British Steel, follows the conclusion that the preferred bidder was unsuitable for the proposed acquisition.
Without disclosing the preferred bidder’s identity, the government said that detailed due diligence and extensive discussions showed that the proposal lacked “the long-term stability, certainty and value for money that workers, communities and taxpayers deserve.”
Norwegian start-up Blastr was understood to be the preferred bidder, though exclusivity rights in the proposed sale lapsed in June.
“We do not intervene in private companies lightly. But nor can we simply stand aside and allow the future of this company and over 1,300 jobs to be decided by default,” said UK Business Secretary Jonathan Reynolds.
He added the decision would keep options open to determine the best long-term future of SSUK as a specialty steelmaker. Further details, including a timeframe for the proposed acquisition, have not been confirmed.
The company, a division of Liberty Steel – part of Sanjeev Gupta’s GFG Alliance – entered liquidation in August 2025 following longstanding financial challenges under previous ownership, particularly the collapse of its primary lender Greensill Capital in 2021.
SSUK’s assets include an electric-arc furnace with capacity to produce 1.3 million tonnes per year of steel, primarily specialty steel bars, in Rotherham, South Yorkshire. The company also has capacity to produce 300,000 tpy of hot-rolled coil and a range of other grades in Brinsworth, and up to 500,000 tpy of merchant bar in Stocksbridge. The company also owns a fourth site in Wednesbury, in the West Midlands.
Restart could boost domestic steel and scrap markets
Before its idling, SSUK was one of the UK’s major domestic ferrous scrap consumers, and its potential restart has been closely watched by steel and scrap market participants.
UK Steel, the trade body representing the country’s steelmakers and most downstream steel processors, welcomed the government’s move as operations at the South Yorkshire sites are scaled up to become fully operational later this year.
“The Stocksbridge, Bright Bar and Thrybergh rolling mills have been operational throughout the liquidation process and have been ramping up production for hire-work,” the association said. “Funding has also been made available to restart the melting operations, with the electric-arc furnaces well on track for a December restart date.”
“This government is once again stepping up to do what is needed for the UK steel industry,” added UK Steel director-general Gareth Stace, saying it would enable SSUK to take its place at the center of critical UK supply chains.
The steelmaker feeds into areas of critical national security including domestic aerospace, defense and advanced manufacturing, producing steel for aircraft landing gear, helicopter rotors, and artillery casings. It is also a major supplier to the oil and gas, automotive and general engineering sectors, the association said.
“SSUK is a unique and integral component of the UK’s steelmaking capabilities, without which we would be entirely reliant on foreign suppliers for high-value speciality inputs to our critical energy infrastructure and our advanced manufacturing base,” added Roy Rickhuss, general secretary of British trade union Community Trade. “We cannot allow British industrial sovereignty in these areas to be lost.”


Northern European domestic HRC softens; Italy ticks up
European domestic hot-rolled coil prices showed a fragmented trend at the start of the week, with values in Northern Europe retreating under prolonged buyer caution, while the Italian market firmed slightly on confirmed transactions.
In Northern Europe, trading activity remained muted on Monday, with market participants reporting sluggish downstream demand.
“We have absolutely no demand, I think this will not change before the end of the year,” one buyer source said, pointing to persistently weak consumption. “Inflation is very high and activity from customers is very low.”
A seller source agreed that buyer appetite has yet to recover, despite some positive economic indicators in Germany.
“We see on the demand side no major activities on restocking,” the seller told Fastmarkets, adding that “the market is very cautious.”
In terms of workable level, one buyer indicated the market within the range of €730-740 ($847-858) per tonne ex-works.
A second buyer told Fastmarkets workable levels were at €740-750 per tonne ex-works. The same source also reported mill offers between €770-780 per tonne ex-works, which were excluded from the index calculation due to a lack of buying interest at those levels.
A third buyer indicated offer levels at €760 per tonne ex-works. These were also excluded due to a lack of buyer interest.
Meanwhile, a seller source estimated tradable levels within the range of €730-740 per tonne ex-works. They added that a leading European producer was offering material at €750-760 per tonne ex-works. That offer was excluded from the assessment due to a lack of buying interest.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €737.50 per tonne on Monday September 14, down by €7.50 per tonne from €745 per tonne on September 11.
The index was down by €5.00 per tonne week on week, but up by €18.75 per tonne month on month.
In Italy, trading activity showed signs of picking up at the start of the week as buyers returned from the summer break. One buyer reported confirmed transactions taking place within the range of €735-740 per tonne ex-works, with domestic mills already beginning to push offers and price targets higher amid tightening local availability and ongoing supply uncertainties surrounding the Taranto steelworks. The market participant said that mills were offering material at €750 per tonne ex-works, but buyers were showing no interest.
The firmer market sentiment in Italy follows a decision late last week by the Court of Appeal of Milan, which upheld the shutdown order for the hot-end area at the former Ilva works in Taranto by October 28.
Meanwhile, Metinvest’s Ferriera Valsider re-rolling facility has yet to return with commercial HRC offers following its restart. Consequently, procurement options for Italian buyers remain limited, leaving the domestic market at risk of having only a single active coil supplier.
Elsewhere, mill offers were heard at around €720-730 per tonne ex-works for October delivery, against buyer price targets heard closer to €700 per tonne ex-works. Both indications were excluded from the assessment, however, as mills were unwilling to sell at the buyer’s targeted level and no other market participants confirmed viable offers or workable business at those levels.
Fastmarkets’ latest daily steel hot-rolled coil index domestic, exw Italy was calculated at €736.25 per tonne on Monday September 14, up by €1.25 per tonne from €735 per tonne on September 11.
The index was up by €8.75 per tonne week on week and up by €22.50 per tonne month on month.

Megasa to improve energy self-sufficiency in Portugal
Spain’s Megasa, Europe’s fourth-largest long steel supplier, plans to invest more than €300 million ($348.1m) to upgrade its facilities in Portugal. It will focus on modernising the SN Maia and SN Seixal operations, with a shift towards captive renewable energy consumption, Kallanish notes.
The steelmaker is transforming its energy matrix with the installation of photovoltaic solar panels at both sites.
“The project aims to reduce our dependence on the national electricity grid, the volatility of electricity market prices in the wake of conflicts in the Middle East and the changes currently taking place in European energy systems,” the company states.
The group believes the Portuguese government’s extension of compensation for indirect CO₂ costs is crucial to the future of the country’s steel industry, at a time when steel mills across Europe are either at risk of closing or have closed.
“As governments cannot intervene in electricity prices, which are set in the Iberian market, the government’s decision directly improves the competitiveness of electricity-intensive industries, particularly steel,” Megasa emphasises.
The company stresses that energy is its second-largest production cost, after ferrous scrap, with its plants being Portugal’s two largest consumers of electricity.
The Maia and Seixal operations produce wire rod, rebar and welded mesh.


Italian appeal court confirms ADI’s hot end shutdown
Milan’s Court of Appeal has reconfirmed its previous ruling requiring Acciaierie d’Italia (ADI) to shut down the hot end at its Taranto steelworks by 28 October.
The ruling follows the 9 September hearing, when the court took an application by ADI’s special commissioners to suspend the order under advisement. The special commissioners had filed the suspension application following the original ruling of 27 July.
The government is considering taking a share of the future company when it is sold, but only if there is a solid industrial plan, undersecretary to the Prime Minister’s Office Alfredo Mantovano has said. Mantovano was an attendee of a recent meeting in Rome where the central government discussed the situation with the local authorities and the unions.
However, an informed source tells Kallanish the company sale remains elusive and the question about how to feed the cold end area remains unanswered.
CBAM has increased costs of imported slabs, and the European Commission may consider including semi-finished products in the quotas system. The cold end area is also in need of an expensive revamping.
Unions Fim, Fiom and Uilm are urging the government to set a date for an urgent meeting in light of the latest court ruling. “The social bomb must be prevented through both ordinary and extraordinary measures. Workers must be protected,” a union note says.
Authorities remain in talks with Jindal Steel International for the sale of the company while 14 Italian steelmakers have formed a consortium and may submit a binding offer. US investment firm Flacks Group has abandoned the race and may instead submit a new offer for Taranto’s real estate assets.
Following the ruling, Giorgia Meloni told local press a new meeting would be convened in Rome to address ADI’s situation. “We work with what we have and with decisions that are not ours. But we will certainly continue to do our best. There was already a working group in place, which I presume will be reconvened immediately to move forward. This is one of the files on which we are spending the greatest number of hours,” Meloni is reported as saying by Ansa.
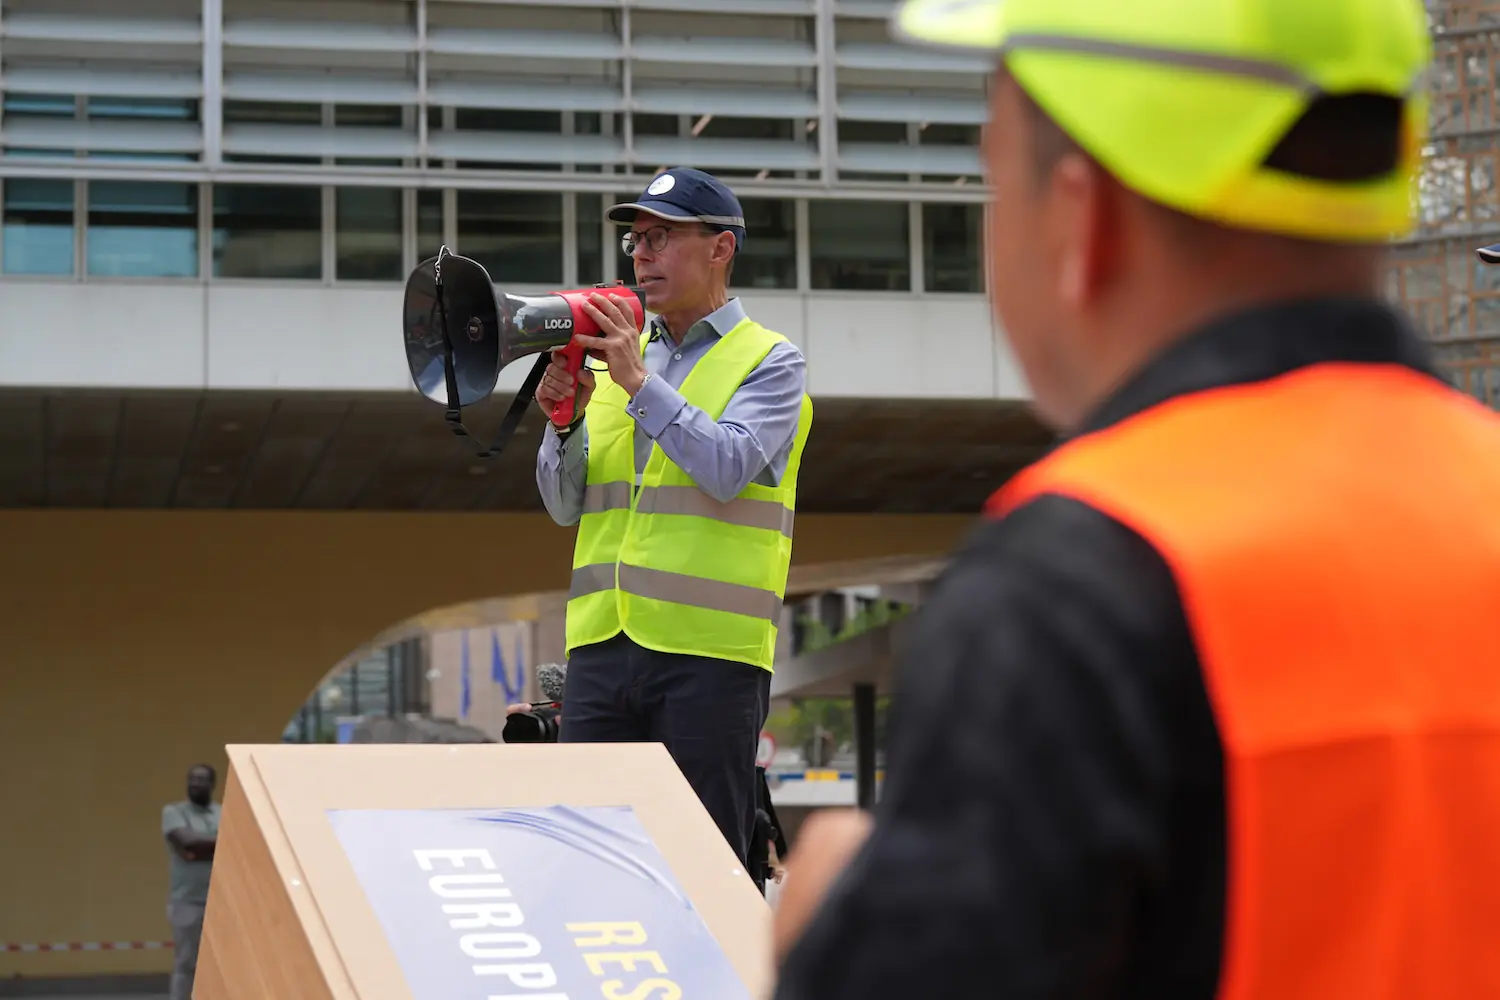
European Parliament adopts position on extending CBAM to downstream steel and aluminium products
The European Parliament has today adopted its position on the extension of the Carbon Border Adjustment Mechanism (CBAM) to downstream steel and aluminium products, marking an important step in recognising that carbon leakage has increasingly shifted beyond primary materials and into manufactured goods.
For several years, EUROMETAL has highlighted the growing imbalance affecting European manufacturers, service centres, distributors and traders, as imported steel- and aluminium-containing products have continued to enter the EU market without being subject to equivalent carbon-related obligations.
The Parliament’s position acknowledges this challenge by supporting a broader application of CBAM to downstream products. While this represents significant progress, EUROMETAL believes that further work is needed to ensure the mechanism effectively delivers a genuine level playing field across the entire European manufacturing value chain.
In its reaction published today, EUROMETAL identifies four key priorities for the next stages of the legislative process:
- Extend CBAM coverage to all relevant steel-intensive and aluminium-intensive products.
- Accelerate implementation to avoid further carbon leakage and industrial relocation.
- Develop an effective solution for European exporters competing in global markets.
- Address the cumulative impact of regulatory costs and trade measures affecting manufacturing competitiveness.
EUROMETAL welcomes the European Parliament’s recognition that carbon leakage increasingly occurs through downstream manufacturing rather than primary materials alone. However, the Federation considers that the current proposal still leaves important product categories outside the scope of CBAM, creating opportunities for circumvention and continuing to expose European manufacturers to unfair competition.
As discussions continue between the European institutions, EUROMETAL will remain actively engaged in advocating for policies that protect the competitiveness of Europe’s manufacturing value chain while supporting the European Union’s climate objectives.
The Federation reiterates that effective climate policy and industrial policy must go hand in hand. Ensuring fair competition across the entire value chain is essential to maintaining manufacturing, investment, innovation and quality jobs in Europe.
Read EUROMETAL’s full reaction to the European Parliament’s position on downstream CBAM here.

Gestamp: Europe must protect automotive value chain amid growing Chinese competition
Spanish automotive components manufacturer Gestamp has warned that the decline of Europe’s automotive industry could have far-reaching consequences for other industrial sectors, including steel, amid increasing competition from Chinese automakers.
Speaking to the Financial Times, Gestamp chairman and founder Francisco Riberas stated that Europe’s automotive industry is facing an existential challenge as Chinese manufacturers strengthen their position in electric vehicles and European vehicle production continues to decline. According to Riberas, European vehicle production has fallen by 20-25 percent since 2017, when global automotive output peaked.
Automotive industry supports broader European industrial base
Riberas stressed that the automotive industry acts as an anchor for several other European industries, warning that losing automotive production could result in the erosion of Europe’s broader industrial base. European automotive manufacturing currently accounts for approximately seven percent of the region’s GDP and supports nearly 14 million jobs. While Riberas said Europe should welcome investments by Chinese automakers, he stressed that such investments need to generate local production and employment throughout the supply chain. According to him, Chinese automakers currently producing vehicles in Europe still source most of their components from China, while Gestamp has only a limited number of contracts with Chinese automakers operating in Europe.
Riberas stated that it is therefore essential for Chinese manufacturers to increasingly source locally produced components, warning that merely assembling vehicles in Europe using imported Chinese components would undermine the European automotive value chain. He noted that traditionally every job at a European vehicle manufacturing plant has supported three jobs in the region’s automotive component industry. The Gestamp chairman also pointed to differences in financing conditions, arguing that European automotive companies face disadvantages compared to Chinese competitors, which he said have access to significantly more favorable financing.
Gestamp supports EU Industrial Accelerator Act
In this context, Riberas expressed support for the EU’s proposed Industrial Accelerator Act (IAA), describing defensive measures as necessary to provide European industry with time to improve its competitiveness. The proposed legislation includes a 70 percent local content threshold for automotive components for investments seeking access to subsidies or public contracts, while also providing for greater scrutiny of Chinese foreign direct investments exceeding €100 million in certain strategic sectors.
At the same time, Riberas stressed that protective measures alone would not be sufficient. He called for a broader European strategy for the automotive industry, including increased investment in technology, digitalization and artificial intelligence to improve competitiveness.
Author: SteelOrbis Editorial Team


European Parliament votes on strengthening CBAM for steel-intensive products
Today, the European Parliament is scheduled to vote on amendments to the Carbon Border Adjustment Mechanism (CBAM), including proposals aimed at extending its scope to additional steel-intensive products.
Ahead of the vote, the European Steel Association (EUROFER) called on Members of the European Parliament (MEPs) to address what it describes as remaining loopholes in the current CBAM framework.
According to EUROFER, while imported steel is subject to carbon-related obligations under the CBAM, many products manufactured from steel remain outside its scope. The association argues that this creates an uneven competitive environment, allowing imported manufactured products to enter the EU market without facing equivalent carbon costs.
EUROFER supports amendments adopted by the European Parliament’s Committee on Industry, Research and Energy (ITRE) that would extend CBAM coverage to additional steel-intensive products.
Commenting ahead of the vote, Axel Eggert, Director General of EUROFER, stated:
“Europe’s steelmakers are investing billions to produce cleaner steel, but they cannot make that transition without a level playing field. MEPs have the opportunity to strengthen CBAM so that investing in low-carbon steel production in Europe makes economic sense.”
In addition to extending CBAM to more steel-intensive products, the European Parliament is also considering amendments relating to stainless steel production. These include proposals to account for emissions associated with ferro-nickel and nickel pig iron used in imported stainless steel, as well as measures intended to close potential loopholes linked to inward processing arrangements.
The outcome of today’s vote will contribute to shaping the future evolution of the CBAM framework as the European Union continues to balance climate objectives with industrial competitiveness.
