


European domestic HRC prices broadly stable despite reported modest demand
European domestic hot-rolled coil (HRC) prices were largely unchanged on October 20 despite reported low trading activity, which was attributed to high customer stocks.
Supply disruptions in Southern Europe, reduced attractiveness of imports and rising energy costs are the key factors helping local mills to hold prices and even pushing them to seek price hikes.
“Demand is not great but I think the weakness is exaggerated,” a buyer from Northern Europe said, adding that “stocks may be healthy now but a lot of that is due to front loading of imports”.
He also said that mills are getting more aggressive in trying to lift the spot market, supported by the fact that they are now negotiating their positions for the first half of 2027 for long-term contracts.
“Also energy is a massive problem at the moment. I do not think people appreciate the cost pressure impact of that enough,” the buyer added.
Market participants provided indications of tradeable levels for HRC in Northern Europe within the range of €740-750 ($830-841) per tonne ex-works on October 20.
Fastmarkets’ daily steel hot-rolled coil index, domestic, exw Northern Europe, was calculated at €747.5 per tonne on October 20, down by €1.25 per tonne day on day from €748.75 per tonne on October 19.
The index was up by €1.25 per tonne week on week and up by €10 per tonne month on month.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €740.83 per tonne on October 20, down by €1.05 per tonne from €741.88 per tonne on October 19.
The index was up by €3.86 per tonne week on week and up by €10.08 per tonne month on month.
The Italian market was also quiet, with no major sales heard during the day, and estimates of tradeable levels were in line with Northern Europe at €740-750 per tonne ex-works.
The market was waiting for news from the Euroblech fair, which is taking place on October 20-23 this week in Hanover.


European coil mills signal annual contract hikes
Mills have issued the first signals to buyers regarding the upcoming talks for long-term coil supply contracts for 2027.
The prices will certainly be higher than they were for the 2026 contracts, with sources suggesting a three figure rise.
The current price of hot-rolled coil from northwestern European integrated mills is around €750/tonne ex-works ($842/t). This is substantially above that of October 2025, when it had had just climbed above €600/t and did not reach more than €620/t in transactions until the end of the year.
Little surprise, mills find that “three-digit improvements from 2026 annual contract levels are appropriate,” one mill manager reveals to Kallanish.
“Most annual contracts this year have not reflected the anticipated price hikes in 2026. They must now make up for that, and also reflect the increase of input costs,” he adds.
Similar signals have been received by various players on the buying end. “You hear €100/t more from all sides,” one observer says.
Another source at a re-roller says he hears indications in the mid-two-digit range. But even a €100/t hike would still not fully reflect the surge on the spot market, especially since many anticipate a gentle continued upward trend going forward
On the spot prices, a manger of a processor company finds that “mills have an enormous tailwind and are very confident.”
He is sure that “prices will definitely not fall back”.
In fact, the observer notes that +€100 applies only to the first half year. “For the second half, some have mentioned a four-digit price,” he says.
This week will see the Euroblech trade fair in Hanover, Germany, take place. According to the re-roller’s manager, Euroblech “takes place too early for concrete talks.” Against that, a buyer of an automotive supplier company confirms that “we will have our first talks [at the fair] on Wednesday.”

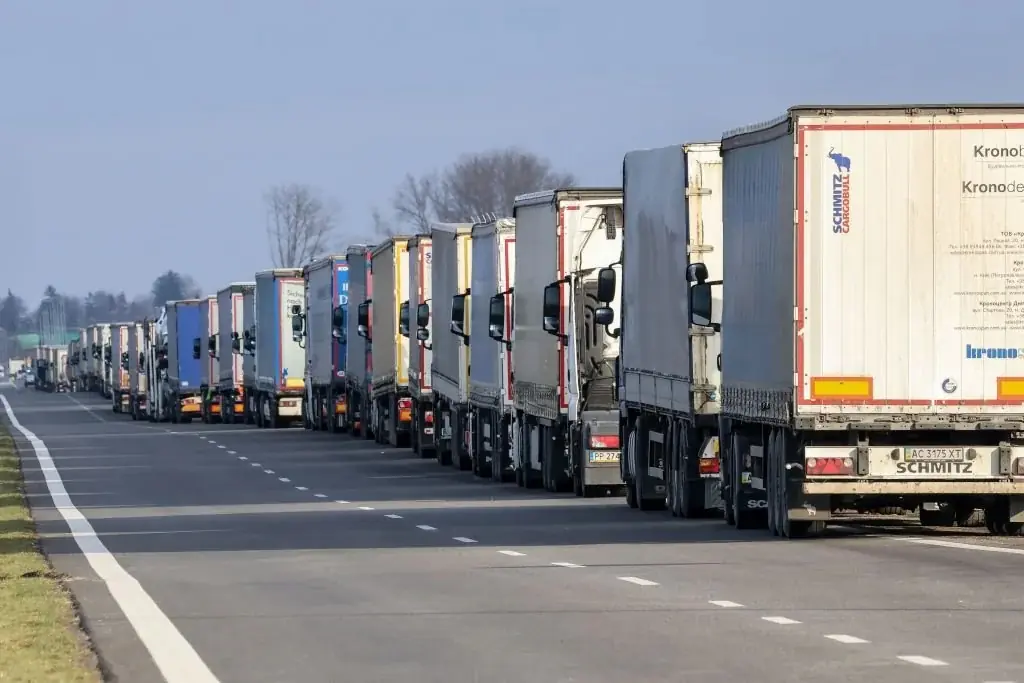
Strikes and protests in southern Italy put logistics at risk, uncertainty persists over former Ilva
Italy is currently experiencing severe disruptions linked to truck driver strikes, which are putting pressure on the distribution of goods and fuel.
The risks could also extend to the steel industry, affecting delivery schedules, vehicle availability and the cost of material delivered to customers. These difficulties are compounded by production uncertainty at the former Ilva plant in Taranto, where the strike ended on October 16, although discussions between the government and trade unions appear to be continuing.
Logistics crisis compounded by industrial difficulties
Logistic difficulties are not a new issue for European steel market participants, which have been complaining for several months about delays, vehicle shortages, inadequate roads and infrastructure, and high costs. In Italy, discontent has resulted in strikes, protests and road blockades, mainly concentrated in the southern part of the country. This is not a nationwide mobilization, but rather a series of local stoppages, actions by independent committees and individual picket lines.
According to local media reports, the Sicilian Truck Drivers’ Committee called for vehicles to be stopped from October 16 until October 20, announcing that its members would not move their vehicles at Sicily’s ports. “The trucks and heavy vehicles belonging to members of the Sicilian Truck Drivers’ Committee are stationary at ports, where they are not unloading ships, nor delivering at company yards,” Rai News reported.
Numerous picket lines have also been set up at the entrances to major roads and highways in Calabria, Puglia and Campania.
Protests over high fuel prices and cost pressure
High fuel prices are one of the explicit reasons for the protests. According to Rai News, diesel costs for truck drivers have reportedly risen by €0.35/L compared to February this year.
Furthermore, the transportation of goods, including fuel itself, has become increasingly difficult due to the protests, with numerous gas stations in southern Italy running out of fuel. The strikes by former Ilva workers have also contributed to this situation, as their protest actions included blocking the state road near the entrance of Italian multinational energy company Eni’s Taranto refinery until October 16.
Former Ilva: reasons for the dispute and status of the plants
On October 12, the main Italian trade unions began a mobilization involving employees of Acciaierie d’Italia (former Ilva), as well as contractors and service workers. The following day, they called a further 48-hour strike due to the lack of adequate responses from the government. Then, on October 15, Uilm, the Italian Metalworkers’ Union, confirmed that a meeting had been scheduled at Chigi Palace, the seat of the council of ministers, for October 27, calling for guarantees regarding employment, environmental protection and industrial operations, as well as a clear decarbonization strategy.
As already reported by SteelOrbis, the Milan Court of Appeal ordered the shutdown of the hot-end facilities at the Taranto plant at the end of July citing public health concerns. However, according to reports today, when the hearing scheduled by the Court of Cassation on the matter took place, the Prosecutor General’s Office at the Court of Cassation only partially accepted the appeals filed by Acciaierie d’Italia in Amministrazione Straordinaria (ADI in AS) and will announce its final decision on the shutdown at a later date.
Meanwhile, the former Ilva plants in Novi Ligure and Genoa may continue production. The strike by workers at the Genoa plant, which also involved a blockade at Genoa Airport, ended yesterday, October 19, following confirmation of the aforementioned meeting at Chigi Palace on October 27.
Potential impact on steel deliveries and supplies
Although the logistics disruptions are well documented, their precise impact on the steel industry has yet to be assessed. So far, no specific blockages of steel cargoes, delays or order cancellations attributable to the protests have been reported.
Nevertheless, three main areas of risk can be identified:
- Less predictable deliveries. Picket lines and blocked access routes may result in missed loading and unloading appointments, requiring deliveries to be rescheduled even when material is available.
- Disruptions to supplies. For scrap, semi-finished products and finished steel products transported by road, route interruptions may create a gap between the physical availability of material and its actual availability at the customer’s premises.
- Higher costs per trip. Waiting times, diversions, vehicle repositioning and refueling difficulties may increase logistics costs per metric ton delivered.
For distributors and service centers, vulnerability mainly depends on usable inventory levels and the possibility of replacing a delivery. In addition, higher transportation costs may be reflected in prices delivered to customers without necessarily affecting ex-works prices.
Short-term outlook
In the short term, the normalization of the scenario will depend on the effective removal of the picket lines, the restoration of fuel supplies and the implementation of government commitments. As for the former Ilva, the key developments will be the outcome of the proceedings of the Supreme Court of Cassation in Milan and the October 27 discussions on the company’s industrial and employment prospects.
For steel market participants, the main risks are reduced reliability of delivery times and upward pressure on the cost of material actually received. However, it is still too early to identify a possible widespread increase in prices linked to these issues.

European steel and downstream industries call for comprehensive EU CBAM expansion
European industry representatives and trade unions have issued a joint statement calling on the European Parliament, Council of the EU and European Commission to agree on the broadest possible extension of the EU’s Carbon Border Adjustment Mechanism (CBAM) to downstream products during ongoing trilogue negotiations.
The signatories include the European Federation of Steel, Tubes and Metals Distribution & Trade (EUROMETAL), Electromechanics Synergy Network, European Steel Tube Association (ESTA), European Non-Integrated Wire Rod Processors Association (EUNIRPA), European Steel Association (EUROFER), European Federation of National Forging Associations (EUROFORGE), European Confederation of Associations of Manufacturers of Insulated Wires and Cables (Europacable), European Aluminium, European Federation of Steel Wire Rope Industries (EWRIS), Federation of the European Cookware, Cutlery and Housewares Industries (FEC), Metal Packaging Europe, Steel for Packaging Europe and industriAll European Trade Union.
EU ETS free allowance phaseout raises concerns over carbon leakage
According to the statement, extending CBAM coverage is necessary to protect European industrial value chains, investments and employment against carbon leakage and competition from imported products that are not subject to equivalent carbon costs.
The signatories warned that European manufacturers face increasing carbon costs throughout steel- and aluminum-intensive value chains, while competing finished and semi-finished products imported from third countries may continue to enter the EU market without bearing comparable costs.
These risks will become more pronounced as free emissions allowances under the EU Emissions Trading System (ETS) are gradually phased out. Broader CBAM coverage would help address differences in carbon costs between European manufacturers and competing imports.
Downstream steel and aluminum sectors face import competition
Several downstream sectors exposed to competition from carbon-intensive imports include energy, automotive and other mobility applications, machinery, construction, packaging, clean technologies and defense. Other affected sectors include household appliances, cookware, cutlery, catering equipment, hand tools and other metal products.
Products included within CBAM’s scope would benefit from more balanced competitive conditions, while products excluded from the mechanism could face greater risks of import substitution and production relocation to countries with lower carbon costs. The organizations therefore called on EU policymakers to build on the positions adopted by the European Parliament and Council and ensure comprehensive coverage of downstream products in the final agreement. They also urged the EU institutions to prioritize European industrial production, investment and employment, emphasizing their importance for the region’s economic security, industrial competitiveness and climate transition.