


German onshore wind power projects lag behind
A total of 551 onshore wind turbines with 2,403 megawatts of installed capacity were erected in Germany in 2022. While this is an increase of 25% over the previous year, the additions remain too low to meet the federal government’s targets, say German wind energy federation Bundesverband WindEnergie (BWE) and mechanical engineering association VDMA.
“The figures remain disappointing for the fifth year in a row. They are symptomatic of the political mismanagement of the last federal government,” says Hermann Albers, president of BWE. “We now need a ramp-up of projects as quickly as possible – this would be an urgently needed positive industrial policy signal for the entire supply chain in Germany and Europe,” adds Dennis Rendschmidt, managing director at VDMA Power Systems.
Besides delays in permissions to build, there were also considerable problems last year with the transport of onshore wind turbines from the production sites to installation sites. This is an echo of a familiar problem for players in the steel value chain.
Wind power is a relevant consumer sector for makers of electrical sheet for turbines, and of plate for the towers. A manager of a plate distributor expresses concern that the wind power expansion is not gaining sufficient momentum. According to him, some 1,000 units are waiting for permission to be built, mostly from local authorities. “With 1,000 tonnes or more per tower, this is quite a figure that we lose out on,” he tells Kallanish.
Christian Koehl Germany

European CRC, HDG prices increase
Cold rolled and hot-dipped galvanised coil prices are surging in European contracts by some €50/tonne ($53) compared to January, Kallanish notes.
Prices are currently higher in Eastern European countries. One mill in Romania is implementing maintenance stoppages, while the void left by Dunaferr idling production in Hungary is being felt. Producers in Western and southern Europe are supplying Eastern Europe, where demand is strong and prices for HDG are at €950-980/tonne base delivered and €10/t less for CRC.
In Italy, Spain, Germany and France, there is a larger number of offers and slightly lower prices than in Eastern Europe. Here, values for HDG are at €920-930/t base delivered and €10/t less for CRC, sources suggest.
Italian lead times now stretch to April, with producers not quoting yet for May allocations. Sources forecast values to continue to hike in Europe slowly but gradually. Italian and Spanish demand is slightly slower this week as buyers purchased significantly in January. However, no competitive imports and high hot rolled coil prices will contribute to sustaining the market.
Natalia Capra France

Northwest European plate prices rise steadily
The rebound in northwest European plate prices that began at the end of 2022 is continuing – not in leaps, but steadily, according to market sources.
Both north and south of the Alps, the ex-works offer price for standard grade S355 plate has reached or surpassed the mark of €1,000/tonne ($1,075). This may not yet actually be paid domestically in Italy, but is heard in some transactions in Germany. “We did have deals for €20 above €1,000,” a mill source tells Kallanish. He concedes that some orders may have been driven by pressure to meet project deadlines, and have so far been an exception.
Elevated prices may become frequent soon, though, buy-side sources believe. “We are preparing for €1,050, and do not exclude €1,100 further ahead,” a manager of a northern German stockholder says. He says a buying spree kicked in just before Christmas and continued into January.
The mill source confirms: “We had all hands on deck with long work days, and it was like that at all mills, but in the last week activity quietened down.” Interestingly, the mill source is less sure about price hikes than buyers. “Mills certainly go for €1,000+, but it remains to be seen if they get it all the time,” he opines. He also notes the big integrated players are trying to push lead times into May but, at the moment, most sources see April delivery as still possible. The first quarter, however, is all closed now, players are sure.
Christian Koehl Germany
ArcelorMittal upbeat on 2023 market prospects; advances decarb, growth strategies
Despite registering a fourth-quarter 2022 operating loss and a $1.03 billion impairment from its Ukraine assets, ArcelorMittal CEO Aditya Mittal said Feb. 9 that in 2022 the steelmaker made “clear progress” on its strategic decarbonization and growth priorities and was upbeat on expectations for improved market prospects for 2023.
“Overall the worst is behind us…we have a constructive outlook for 2023,” Mittal told analysts on a conference call to discuss full-year and Q4 2022 financial results. “We expect that, in Q1 and ahead, the business will perform better: we see good developments on the real demand side.”
ArcelorMittal registered an operating loss of $306 million in Q4, down from an operating profit of $4.56 billion for the same period in 2021. For 2022, operating profits fell to $10.27 billion from $16.97 billion a year earlier.
Sales revenue for the year grew to $79.84 billion from $76.57 billion in 2021, because of a spate of high prices as markets reacted to fears of tightness in certain products in the weeks following Russia’s Feb. 24 invasion of Ukraine before falling back.
Order books now up
The company expects overall orders to grow 5-6% this year, on the back of stronger markets, particularly in Brazil and NAFTA, where the company is expanding production. This would exceed expectations for overall apparent global steel demand growth of some 2%-3% this year.
While the headwinds of an unresolved situation in Ukraine and tightening monetary conditions globally continue to pose challenges, the direct impact of high energy prices has eased, with energy prices notably lower than in periods of 2022, it said.
“Energy costs in Europe continue to come down and normalize and this is helpful for order books, we expect orders to increase in all segments in Q1,” CFO Genuino Christino said on the call. “Prices have started to move up quite significantly so this looks good for Q2, and we expect costs to continue to come down: we won’t see such an impact from costs in the coming year… we’re cautiously optimistic.”
Platts assessed domestic prices for hot-rolled coil in Northwest Europe at Eur765/mt EXW Ruhr Feb. 8, up Eur5, amid positive sentiment on reports of mills’ strengthening order books.
Steel product destocking, which dominated markets in Q4, is no longer such a problem, Christino said.
“It’s hard to say the destock is over but it’s certainly less severe than in Q4,” the CFO told analysts. “Europe’s not so bad… in terms of real demand we were close to breakeven at the end of the year in Europe, even slightly positive.”
The intensity of the last quarter’s destocking was greater in Europe than in the US and was also more intense in flat products than in long products or tubular goods, Christino said.
In the auto industry, a key flat products consumer, second-half 2022 was “relatively good” in Europe, after a “very bad” H1, with a similar production improvement seen in NAFTA, the CFO said. “We will continue to see progress: we’re looking at a range of 5% increase in auto production in 2023.”
Furnace capacity “available”
In Europe, where ArcelorMittal took some blast furnaces offline last year amid weak demand, the company now intends to bring production back in response to improvements seen in order books, according to the executives.
“In Q4, we had some furnaces brought down for maintenance and now they’re up and running,” Mittal said. “We only have one small furnace in Dunkirk which is down and is near the end of its life which we may or may not bring back….. all the other capacity remains available for the group,” Mittal told the analysts.
In Ukraine, ArcelorMittal is currently operating at around 15-20% capacity at its Kryviy Rih steelworks and at 20-25% capacity at its iron ore mines in the country, the executives said.
The focus is to maintain the integrated Ukraine assets operational so that they still have the opportunity to produce in the future and participate in the country’s reconstruction, they said.
Strategic projects
Some of ArcelorMittal’s new projects combine both decarbonization and growth as the company progresses with plans to reduce the carbon intensity of its global production by 25% by 2030. Last year, it acquired a hot briquetted iron plant in Texas to provide metallics for low-carbon steelmaking, inaugurated a carbon capture and re-use project in Belgium, acquired four European scrap companies, boosted capacity at its major joint venture Indian steelmaking operation, acquired the CSP steel slab mill in Brazil and started ramping up a new 2.5 million mt/year hot strip mill in Mexico, among other projects.
It has received approval for a decarbonization project in Canada and is awaiting approvals for four decarbonization projects in the European Union, expected to be granted within a few months, Mittal said.
The company is meanwhile “quite pleased with the evolution” of its hot strip mill project in Mexico, which is currently running at a 50% run rate and should eventually provide up to $250 million worth of additional EBITDA, Mittal said.
— Diana Kinch


German energy ministry advisers warn about overreliance on carbon CfDs
Overreliance on carbon Contracts for Difference to drive industrial decarbonization risks creating a subsidy-dependent culture, according to a Feb. 8 report by the economic advisory council to Germany’s energy ministry, or BMWK.
Berlin plans to use carbon or climate CfDs to bridge the gap between market returns and the cost of energy transition projects.
“Climate CfDs could lead to a significant overfunding and hamper competition and the development of new technologies,” Klaus Schmidt, the head of the council, said.
He has recommended only limited use of the instruments, focused on pilot projects and issued through competitive tenders.
The state would fund the gas between market prices, specifically EU carbon allowances, and required project costs for 15 years in industries where decarbonization technologies such as hydrogen are not yet profitable with a focus on steel, cement, and ammonia.
Analysts at S&P Global forecast EUAs to average around Eur78/mt in 2023, down 4% on the 2022 average price, which was up 52% from 2021.
Decarbonization projects in hard-to-abate sectors like steel would require a higher carbon price to become viable, hence the need to bridge the gap.
The report also recommends defining new markets for green products through tradable guarantees of origin, with green steel used as an example.
According to media reports, energy minister Robert Habeck wants to see a double-digit billion euro sum funding a carbon CfD system.
The coalition government is also working on an updated national hydrogen strategy, which first proposed climate CfDs, to reflect new climate targets.
— Andreas Franke
Hungary’s Dunaferr steel mill remains idled amid lack of materials
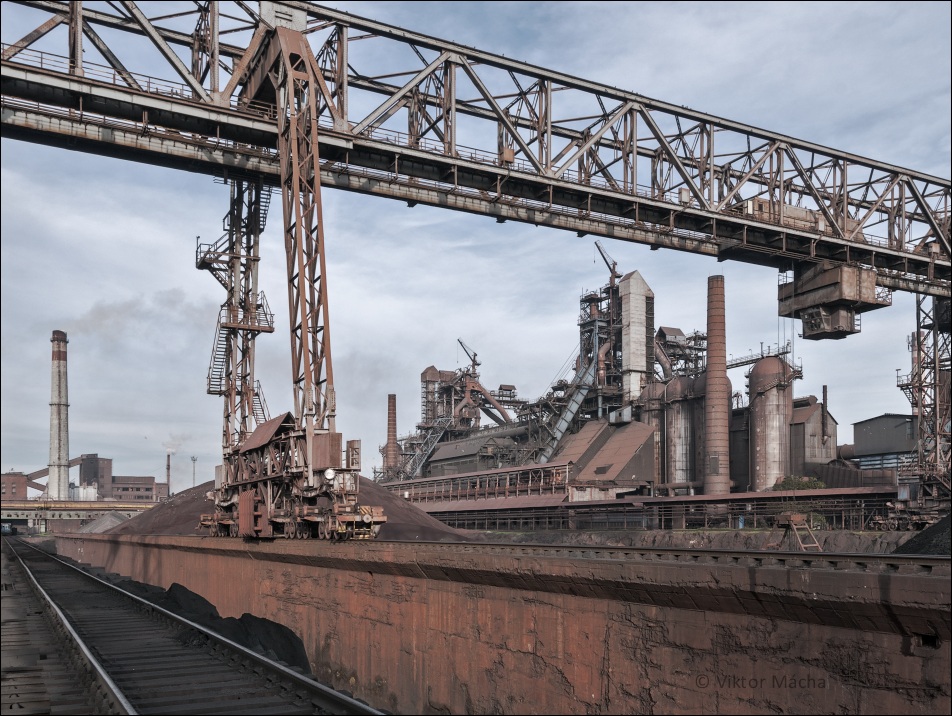
Hungary’s sole flat steel producer Dunaferr has so far this month been unable to restart output, as had been planned, due to a lack of raw materials, market sources told S&P Global Commodity Insights Feb. 9.
At the start of this month market sources had told S&P Global Commodity Insights that the steelmaker was looking to restart, using slab from Romanian steel producer Liberty Galati, which belongs to UK-registered Liberty Steel Group.
But market sources said this week that, so far, the Romanian company has only provided limited volumes of coking coal to maintain operation of coke batteries, with no deliveries of iron ore or other raw material made.
Liberty Steel, which has previously been named by market sources as a potential buyer of the Hungarian steelworks, declined to comment Feb. 9.
Dunaferr wasn’t immediately available for comment.
A municipal court in Dunaujvaros ordered the liquidation of Dunaferr in December and appointed a temporary administrator, with the steelworks previously idled since the third quarter.
“Main raw materials — in the amount necessary for stable and continuous operation of the blast furnace and steel shop — have not yet been received, and there is a very low probability that it will be received in the coming days,” one Central European source close to the mill said.
The Dunaferr plant’s two idled blast furnaces have a total capacity of 1.2 million mt/year.
One market source said that Liberty Steel was planning to ship limited volumes of hot-rolled coil from its mill in Romania for downstream processing at Dunaferr, although this couldn’t be confirmed with the company.
At the beginning of February, Hungarian Prime Minister Viktor Orban announced that the government would pay the wages of Dunaferr’s workers for the next six months, with a sum of Forint 16 billion ($45.4 million) earmarked for this. During the six-month period, the government said it expects a new owner to be found for the plant.
Ukraine’s Metinvest has previously said it would also be interested in buying Dunaferr.
“We have been one of the main suppliers of raw materials for Dunaferr plant over the past few years,” a spokesperson for Metinvest told S&P Global. “If these deliveries continue, it will allow us to resume operations at our mining and processing sites in Kriviy Rih.”
The spokesperson said that the company remains interested in purchasing Dunaferr, adding that this was communicated to the government during a recent visit by the company to the Hungarian Ministry of Economic Development.
Metinvest said that it hoped for a fair and transparent tender for the sale of Dunaferr, but that it was too early to be more specific about the process.
— Maria Tanatar, Ekaterina Bouckley
Reduced consumption, falling prices dent ArcelorMittal Europe’s results in Q4 2022; modest recovery expected for 2023
A sharp decline in apparent steel demand amid significant destocking during the fourth quarter of 2022 caused ArcelorMittal’s European business to record an operating loss in the three-month period, but a modest recovery is expected in 2023, the steelmaker said on Thursday February 9.
Key steel market developments
Fundamentals in the European steel market remained challenging during the December quarter of 2022, with steel prices plummeting amid a contraction in demand, according to market sources.
The war in Ukraine flustered the European steel market and caused a wave of a panic-buying in February-March 2022, with prices for flat and long steel reaching new historical peaks and breaking records set in the 2021 European summer.
That, however, resulted in massive overstocking, so hot-rolled coil prices began falling from April 2022 until the year-end due to the toxic combination of slowing end-user demand and this oversupply.
For example, Fastmarkets’ calculation of its daily steel hot-rolled coil index domestic, exw Northern Europe averaged €657.19 ($705.20) in the fourth quarter of 2022, down by €140.95 per tonne from €798.14 per tonne in the previous quarter and down by €317.89 per tonne from €975.08 per tonne in the fourth quarter 2021.
Steel prices declined at a faster rate than those for raw materials during the fourth quarter of 2022, leading to shrinking spreads and squeezed margins at steelmakers, according to ArcelorMittal.
European buyers had been trying to reduce their stock levels throughout the second half of 2022, with a peak of the destocking cycle occurring in the fourth quarter, market participants said.
Overall, apparent steel consumption in Europe declined by 7-7.5% in 2022, according to ArcelorMittal.
Impact to ArcelorMittal
During the December quarter of 2022, ArcelorMittal Europe recorded an 18.07% decline in steel shipments, to 6.8 million tonnes, compared with 8.3 million tonnes in the corresponding period of 2021.
Crude steel production at company’s European mills also dropped as a result of output cuts announced during the quarter to balance the oversupplied market.
Notably, crude steel output at ArcelorMittal Europe amounted to 6.9 million tonnes in the fourth quarter of 2022 compared with 8.6 million tonnes in the same period in 2021.
ArcelorMittal Europe’s sales dropped by 16% in October-December 2022, to $10.08 billion, compared with $12.08 billion in the corresponding period of 2021. This was the result of both reduced shipments and lower steel prices.
And finally, ArcelorMittal Europe recorded an operating loss of $10 million in the final quarter of 2022, compared with an operating income of $158 million in third quarter 2022 and $1.9 billion in the fourth quarter 2021.
Outlook for 2023
While the company expects real steel demand to decline marginally in Europe in 2023, apparent steel consumption is expected to show a moderate year-on-year growth of 0.5-2.5%.
Indeed, market conditions started showing early signs of improvement in January 2023 with a restocking drive supportive price rises in flat steel sector, ArcelorMittal said.
Fastmarkets’ calculation of its daily steel hot-rolled coil index domestic, exw Northern Europe averaged €720.36 per tonne in January 2023, up by €77.63 per tonne from €642.73 per tonne in December 2022.
Also, energy prices have reduced significantly from multi-year highs observed in the second half of 2022, alleviating the pressure on margins.
“As we look ahead, evidence suggests that the customer destock we saw in the second half of 2022 has peaked, hence providing support to apparent steel consumption and steel spreads. Although geopolitical uncertainty remains high, we remain confident in the strength and resilience of ArcelorMittal, and in our ability to successfully execute our strategy of growth, decarbonization and sustainable returns through all aspects of the cycle,” Aditya Mittal, ArcelorMittal’s chief executive officer, said.
Published by: Julia Bolotova

Turkey ferrous: Force majeure declared
Turkish scrap import prices were flat on Friday as at least one Iskenderun mill declared force majeure in response to the state of emergency declared in southern Turkey following the deadly earthquake on 6 February.
In an official notice, Bastug Metalurji stated that contracts that have been signed and/or are about to be signed are now subject to force majeure conditions. It said that “our obligations to perform under the contract have been suspended/extended accordingly.”
Other Iskenderun mills have been heard to declare force majeure but no official documentation confirming this was has been seen by Argus.
Steelmakers had to wait for the Presidential Decree of a State of Emergency to be passed through the national assembly to become law and be officially gazetted before declaring force majeure.
Iskenderun mills likely have no choice other than to go down this route primarily because of the inability to load or discharge steel and scrap cargoes at a time when there is little manpower available and support infrastructure at the port of Iskenderun remains disrupted.
After a declaration of force majeure, scrap sellers will tell shipowners that they do not have to pay demurrage costs for vessels that are sailing and unable to be discharged. Because there is a force majeure situation vis-à-vis their customer, they are protected and the discharge conditions have to be extended. Vessel owners will then have to claim insurance for the costs of vessels that have to remain seaborne for longer than the contract conditions.
Some market participants said that there is an obligation for both seller and buyer to try to mitigate the damages but that the likelihood of cargoes being re-directed to other buyers was slim. It is also not in the interest of Iskenderun buyers to re-direct cargoes when most of those cargoes traded at lower prices than today’s market level.
At least 11 deep-sea cargoes are understood to be seaborne and destined for Iskenderun. Five are of European-origin, four are of UK-origin, one is of US-origin and the other is of Baltic-origin.
The declaration of force majeure also means that steel shipments will not be loaded, at least in the short-term, and protects any steel seller from being sued for not performing the contract/shipment. Most steel shipments scheduled will have been traded at lower prices than today’s market price range.
Most market participants in China expect construction steel demand to improve further next week and data released today by the People’s Bank of China provided some solid support. New bank loans in January were more than three times the numbers of December, much higher than expected. New bank loans stood at YN4.9tn ($720bn) in January, indicating how the central bank is looking to stimulate economic recovery after the easing of COVID restrictions.
The Argus daily HMS 1/2 80:20 cfr Turkey steel scrap assessment was flat at $427/t cfr on Friday.
The Argus daily HMS 1/2 80:20 cif Turkey (short-sea) steel scrap assessment was flat at $407.50/t cif on Friday.
By Alex Reynolds


Europe scrambles for Asian HRC after Turkey earthquakes disrupt supplies
European hot-rolled coil (HRC) buyers are scrambling to purchase Asian cargoes, with a rebound in demand hit by disruption to supplies from Turkey following this week’s earthquakes there.Indian, Vietnamese and South Korean steelmakers have reported healthy inquiries from European buyers, with a major Indian steelmaker already concluding transactions at around $800 per tonne CFR Antwerp and Vietnamese steelmakers booking quantities at $680-685 per tonne FOB.
An Australian producer sold HRC into Italy at $750 per tonne CFR, while HRC from a major South Korean steelmaker was sold in Southern Europe at €750 ($804.79) per tonne CFR, sources told Fastmarkets.
“South Korean steelmakers are likely to aim for $720 per tonne FOB to Europe, if they have excess supplies for the spot markets,” according to a seller source dealing with a major South Korean steelmaker.
Taiwanese and Indonesian HRC were also heard to have been sold into Europe at €760 per tonne CFR Southern Europe.
European buyers had already been buying HRC in the spot import market due to reduced supplies in the region, partly caused by low operating rates at European steelmakers in the fourth quarter of 2022.
Vietnam’s decision to divert domestic HRC supplies to Europe has also squeezed local buyers there, who are now having to import HRC from China to make up for supply shortfalls.
“Buyers [in Vietnam] are accepting prices of $670-685 per tonne CFR now because of the reduced quantities available from local producers,” a trader source in Vietnam told Fastmarkets on Thursday.
Market participants expect spot prices to continue increasing in the near term, even though many Vietnamese buyers have fulfilled their import demands with Chinese Q195 HRC cargoes in the two weeks after the Lunar New Year.
“Prices may even go as high as $700 per tonne cfr Vietnam,” a seller source close to a major Vietnamese blast-furnace-based producer said.
Market participants expect the next offers from major Vietnamese producer Formosa Ha Tinh Steel Corp to be higher in the middle of the month, especially as the latest offer price from domestic competitor Hoa Phat Group was only at $650-655 per tonne CIF for domestic buyers.
Indian steelmakers are also bullish on spot prices, mainly because domestic demand has been strong.
“I won’t sell much into Europe because local demand from the infrastructure sector is good,” a seller source close to a major Indian steelmaker said.
Other Indian steelmakers are now aiming to sell at more than $800 per tonne CFR, an increase of $20 per tonne on the previous transactions, which were heard at $780 per tonne CFR Europe.
Indirect benefits for China
With short supplies forcing Vietnamese buyers to accept higher import prices, China-origin HRC – which is subject to hefty anti-dumping duties in Europe – is expected to see higher export prices and continuing trading, market participants said.
Fastmarkets calculated its steel hot-rolled coil index export, fob main port China at $625 per tonne on February 9, up by $5 per tonne from the previous day.
HRC exports from China – the largest steel-producing country in the world – have been active since December last year, mainly due to changes to the exchange rates, lower freight rates, price gaps between different markets and low inventories at distributors and end users, a trader in eastern China said.
Several traders said that HRC export trading had seemingly weakened, compared with the period before the Lunar New Year holiday, but traders agreed that the earthquake in Turkey had caused a supply shortage that was likely to help Chinese export trading regain some momentum.
Southeast Asian countries and Turkey are transshipment ports for Chinese steel flowing into Europe and Africa, traders said.
“High energy costs and sanctions on Russia have already increased European demand for Asia-origin steel. Now that demand is set to increase after the devastating earthquake that has disrupted transportation in Turkey,” a trader in northern China said.
Countries in the Association of Southeast Asian Nations (ASEAN) remain the top destination for Chinese steel exports, while Turkey has also been one of the major buyers.
More than 2.74 million tonnes of Chinese HRC were exported to Vietnam in 2022, accounting for nearly 27% of the total exports of this flat steel product from China, making it the biggest buyer of Chinese HRC exports, according to Fastmarkets’ calculations based on data from China’s General Administration of Customs.
Customs data also shows that the volume to Turkey imported 616,694 tonnes, or 6% of China’s total HRC exports, in 2022, putting it in fifth place.
Published by: Paul Lim, Zihuan Pan
EU CBAM puts African installed power capacity at risk: Anglo American
The EU’s introduction of its planned carbon border adjustment mechanism risks derailing the expansion of installed power capacity across the developing world, Anglo American CEO of Global Bulk Commodities Themba Mkhwanazi told the Investing in African Mining Indaba in Cape Town Feb 8.
Members of the European Parliament reached a provisional agreement with the European Council in December on a law to establish the new carbon fee.
Under the rule, companies importing select products “including iron, steel, and some items made of the two metals” will be required to buy certificates that represent the difference between the carbon price paid in the country of production and the carbon price in countries participating in the EU emissions trading system.
Once finalized, the policy will go into effect in October, beginning with a transition period.
According to Mkhwanazi, the implementation of CBAM in its existing form would slow the roll-out of installed power capacity throughout the African continent as metal and mining companies halted or delayed investments in projects and adjacent infrastructure in light of the new tariffs associated with importing emissions-intensive products to the EU.
“There must be an acceptance that there is an energy transition pathway that does not got directly from fossil fuel to green energy,” he said, adding that the decarbonization of Anglo’s steel operations would be less direct and would involve the use of abatement technologies.
Despite its progress in decarbonizing its steel operations, Mkhwanazi noted that Anglo’s African operations would continue to rely on the traditional blast furnace with the company using hydrogen produced from natural gas and carbon sequestration to minimize its carbon emissions footprint and achieve emission reduction objectives.
Although adding hydrogen into blast furnaces can reduce carbon emissions, that does not offer carbon-neutral steel production because regular coking coal is still a necessary reductant agent in the blast furnace.
In its current form, CBAM does not make allowances for products produced outside the EU using emissions abatement methods, such as carbon sequestration or the use of hydrogen in steelmaking.
“The EU regulations put at risk our installed capacity in South Africa and the developing world which is very much based on fossil fuels,” he said.
Net-zero emissions by 2040
According to Mkhwanazi, Anglo is continuing to decarbonize its African steel value chains with the company targeting a 30% reduction in group carbon emissions by 2030 and net-zero emissions across all operations by 2040.
Last July, Anglo said it was partnering with EDF Renewables to develop 3-5GW of clean generation capacity in South Africa, to meet the companies operational power requirements and support the local electricity supply systems.
The mining of Africa’s mineral resources must be achieved in a responsible way in harmony with the needs of society and the natural environment, Mkhwanazi said.
“We must do this in a way that create enduring value and a decent lift for all.”
— Euan Sadden