


Europe’s steel hollow sections market suffering from energy-cost uncertainty, trader says
Prices for hollow steel sections in Northern Europe remained unchanged but the market in Southern Europe narrowed downward in the week to Wednesday October 5, due to limited trading.Fastmarkets’ weekly price assessment for steel sections (medium), domestic, delivered Northern Europe, was €1,020-1,050 ($1,012-1,041) per tonne on Wednesday, stable week on week.
Sources told Fastmarkets that stockholders were busy trying to clear imported steel products under this year’s fourth-quarter EU steel safeguard quota allowance.
“There are not so many inquiries at the moment, and no sales [in which] to reduce or increase the price due to low demand,” a producer said.
But sources in Southern Europe said that, despite the low consumption, demand for sections was not dead and that production was still running at full capacity at some mills.
“We are pushing on with production and using quite a lot of energy,” the producer said. “Clearly, there are higher costs and, for the moment, we are trying to manage, but we will see [how the situation develops] in the coming months.”
Fastmarkets’ weekly price assessment for steel sections (medium), domestic, delivered Southern Europe, was €970-1,020 per tonne on Wednesday, narrowing downward by €30 per tonne week on week from €970-1,050 per tonne.
Market participants expected construction-sector consumption of steel products to remain weak until next year, despite the European Council approving emergency measures on September 30.
The measures, intended to ease the burden of rising energy costs fueled by Russia’s unprovoked invasion of Ukraine in February, included a voluntary overall reduction target of 10% of gross electricity consumption, and a mandatory reduction target of 5% of electricity consumption during peak hours.
The council also approved a cap on market revenues at €180 per MWh for “inframarginal” technologies such as renewable and nuclear energy producers, a windfall levy on fossil-fuel companies, and additional powers for member states to temporarily set a price for the supply of electricity to small and medium-sized enterprises.
The regulation was scheduled to come into force early this month.
Some EU member states have also pledged independent support for energy-intensive industries, with the Italian government approving its “Aiuti Ter” decree which will offer heavy industry companies a 40% tax rebate at the end of 2022.
The German government announced a €200 billion support package for businesses and households, while France and Italy have pledged subsidies of €67 billion and €68 billion respectively.
But sources told Fastmarkets that they did not think any short-term measures would improve construction consumption due to there being long lead times for projects.
The August forecast by European steel association Eurofer predicted that apparent steel consumption would recover in 2023, following a third annual recession in the past four years.
“But the overall evolution of steel demand remains subject to high uncertainty, which is likely to continue to undermine demand from steel-using sectors,” Eurofer said in its third-quarter report.
Traders said that mills needed more clarity on energy costs so they could calculate whether to reduce or shut down production.
“The market is suffering at the moment because it is unclear what will happen – no one knows for the moment,” a trader said.
Meanwhile, traders said that the market for the product’s feedstock, hot-rolled coil, was muted due to sluggish demand.
Fastmarkets’ daily calculation of its steel hot-rolled coil index, domestic, exw Northern Europe, was €740 per tonne on Wednesday, down by €22.50 per tonne from €762.50 per tonne a week earlier.
Published by: Holly Chant


Voestalpine defines sustainable and digital research for €200m
Voestalpine has budgeted some €196 million ($193m) for research and development (R&D) in the current business year (April 2022-March 2023).
Research priorities include digitalising the production processes, developing innovative products, and converting to climate-neutral steel production, Kallanish hears from the Austrian company.
It says it is heavily researching digital simulation methods and processes that will prepare and support the transformation of steel production. For example, one project is assessing the potential for recycling by-products into the production process and developing technologies for a circular economy to ensure climate-neutral steel production in the future.
On the product side, the group is developing new digital and smart technologies such as “intelligent” cold-rolled steel strip. For tailormade functional steel, conductor tracks for the required sensors are integrated into a special high-quality coating layer. Intelligent sensors also ensure continuous monitoring in smart turnout systems. The development focus is to make sure the system detects and reports impending failures early on.
“The use of artificial intelligence is constantly opening up new technological opportunities for both production and products,” says R&D head Franz Androsch.
Worldwide, voestalpine has over 740 employees working in R&D in more than 80 companies. It cooperates with around 100 scientific partners, and also cultivates strong development partnerships with key customers.
Christian Koehl Germany

German fabricators see orders declining
Production at Germany’s steel-using industries dropped in the second quarter – the first period marked by the war in Ukraine, and more recent order intake figures suggest low activity going forward.
In the second quarter, companies produced 2.1% less than in the first quarter, and 2.7% less year-on-year, according to industry federation WSM. The first half-year in total saw orders decline by 1.5%. At the MBI Stahltag conference last week, WSM managing director Christian Vietmeyer presented the latest figures for July, which showed further drops for most sectors of the industry.
Wire products as well as surface coated and heat-treated products were down by more than 8% y-o-y, very likely because of their higher consumption of costly natural gas. Many other segments saw drops of between 2% and 6%. A positive exemption occurred on cold-rolled narrow strip, which was up 3%, and for pipes, which were up by 1.5%, probably owing to orders for domestic infrastructure, Kallanish heard from Vietmeyer.
The negative gap becomes much wider when looking at the order intake of the month as well as seven-month period, which was down in the two-digit percentage range for most products. However, the figures compete with the base effect of a strong summer in 2021, when many companies caught up on the lull of 2020. A recent outlier is the arms industry, which in the first seven months saw orders rise by as much as 207%. Notably, July itself brought a y-o-y drop for that sector, too, by 15%, in spite of the ongoing war in Eastern Europe.
Christian Koehl Germany
EC clears Germany’s €1 billion Salzgitter decarbonisation aid
The European Commission (EC) has approved Germany’s €1 billion ($992 million) state aid measure to help steelmaker Salzgitter implement green hydrogen into its production processes, Kallanish reports.
The approval on 4 October clears the way for €700m in federal support and €300m for state support. The direct grants will support the construction of an electrolyser, a direct reduction plant and an electric arc furnace for the first stage of development of Salzgitter’s SALCOS project.
The on-site, 100-megawatt electrolyser will produce roughly 9,000 tonnes/year of green hydrogen, which will be used as feedstock in the DRI plant to produce sponge iron. Salzgitter, which has already committed €723m to this initial stage of the project, expects to commission the 1.9 million t/y crude steel production capacity by late 2025.
The three-phase project is designed to include two DRI plants and three EAFs to replace blast furnaces and converters by 2033. When fully operational, this new hydrogen route to steelmaking is planned to cut emissions by 95% or 8m t/y of CO2.
“This [measure] will contribute to the greening of a very energy-intensive and hard-to-abate sector while reducing Germany’s dependence on imported fossil fuels,” comments EC vice-president Margrethe Vestager.
The EC says the aid has an incentive effect “as the beneficiary would not carry out investments in the steel process decarbonisation project without the public support”. It adds that the aid’s positive effects outweigh any potential distortion of competition and trade in the EU, and that the company will return part of the aid received to Germany if the project is “very successful and generates extra revenues”.
Aperam to use temporary layoffs to reduce output
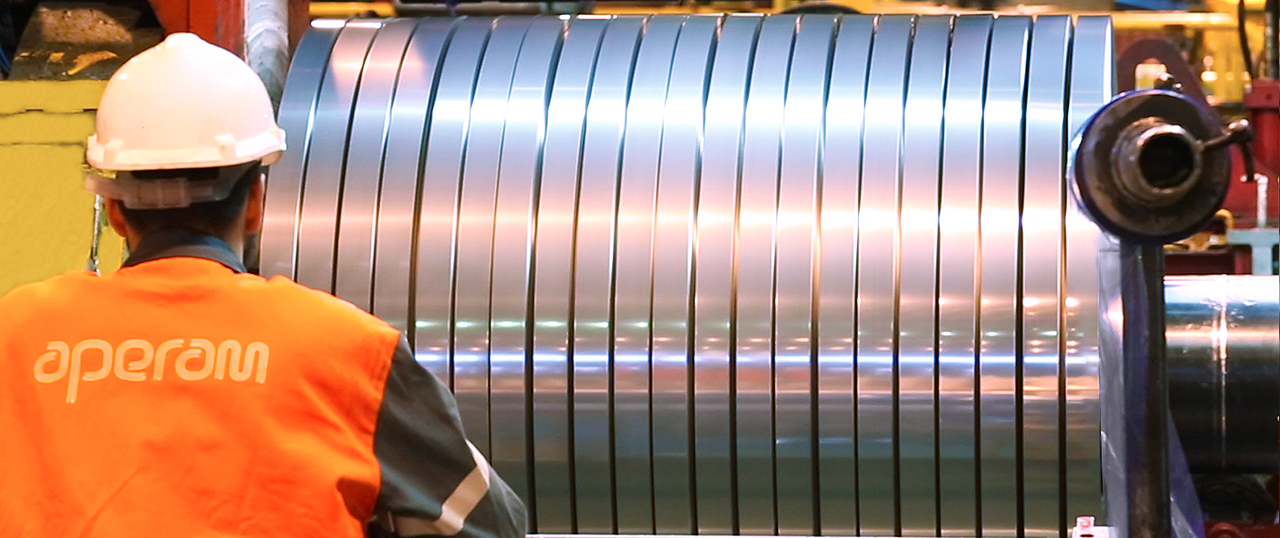
Aperam is expected to make use of a new Belgian law on temporary layoffs to reduce output further during October and November, Kallanish notes.
At its mill in Genk, the company is reported to be applying for a full closure of one week at the end of October, supported by a new temporary layoff scheme designed for energy-intensive industries.
The mill already reduced output during the summer, extending the usual August closure into September, due to high energy costs and market uncertainty. Output at the mill is expected to resume fully in October, before the week-long stoppage at the end of the month.
Emanuele Norsa Italy
EU re-rollers seen struggling to replace Russian slab
The new, eighth round of EU sanctions on Russia encompasses, according to some reports, semi-finished steel, which could spell major problems for some European slab re-rollers, as Russian semis cannot easily be replaced for some applications, Kallanish notes.
Although the sanctions package was approved on Wednesday, details are expected to be published only on Thursday. It is however reported to include steel products, meaning semis are likely to be affected. It nevertheless appears some countries may be spared from the ban on importing Russian slab for two years.
A group of European re-rollers recently wrote to the European Commission, in the wake of speculation, widely publicised by some agencies, that slab will indeed be sanctioned. They poignantly answered the question of why Russian slab imports were not sanctioned in the first place (see Kallanish passim).
“The lack of supply for re-rollers would hamper the EU’s ability to build [among others] new wind installations and improve energy independence, while the semi-finished steel products [slabs, billets, and blooms] would be immediately redirected to other regions and with a 1% share of steel semis in total Russian exports, the potential ban would not have any tangible impact on Russia,” the letter says.
European steelmakers appear to have been lobbying the EC to include slab and billet in the list of sanctioned products, “using political arguments in what is essentially an economic and competitive issue”, the re-rollers went on. The re-rollers “help balance the demand and supply of finished steel producers”. As a sector, they account for 8% of total EU flat steel output and provide more than 30,000 jobs in the EU, according to the group.
With so much at stake, it is widely assumed that replacing Russian slab would be easy with the array of established as well as new, opportunistic suppliers currently operating in the market. To an extent, it is possible to replace slab supplied to re-rollers producing hot rolled coil with European material, depending on the level of finished product pricing in the region.
Reports this week of European slab exports, as a solution to low demand and HRC prices in the EU, suggest this supply could also find its way to the bloc’s re-rollers. But the heavy plate business, painstakingly created by cooperation between European and Russian counterparties in the last 20 years, is most at stake, market observers note.
Russia’s NLMK, the only non-sanctioned Russian slab producer, runs three plate mills in the EU: DanSteel (Denmark), Verona (Italy) and Clabecq (Belgium), to the aggregate nameplate capacity of around 1.75 million tonnes/year. Its model of re-rolling a lower-priced, precision produced slab in a higher paying market such as Europe is now under threat of collapse, amid Russia’s invasion of Ukraine and consequent sanctions.
Most vulnerable in the equation is DanSteel, which requires specialised slab with certain surface and chemical characteristics, currently unattainable in the merchant market.
NLMK has in fact been looking at alternative slab supplies for over a decade in order to reduce costs further, but the search has always encountered two main problems: economics and supply reliability.
“Even if [they] found a producer that could supply the appropriate quality, there would always be an issue of can this supplier guarantee certain volume, at certain prices, and for a certain length of time without changing them. The answer would always be no,” one former industry executive says.
As the supply pool expanded recently amid global modernisation efforts, some Chinese slab was tried, but it was only approved by some mills, due to quality. Brazilian supply would work on quality but is currently hinged on the US market, and, seeing only occasional sales to the eastern hemisphere, this would affect its pricing policy significantly. There is also supply from Asia, especially now when the Asian steel market is seeing negative growth, but “this supply is incidental, and while it may serve as an occasional supplier, it is hard to rely on a [long-term] basis,” a source observes.
South Korean slab quality is well known in the global market, and it could also replace some of the more intricate slab quality requirements, apart from oil and gas pipe applications and shipbuilding.
“There could be new supply alliances forged, but it cannot be accomplished immediately; some time will be needed to achieve this,” a former slab trader concludes.

EU HRC market quiet as participants look toward Euroblech fair
European hot-rolled coil prices held stable Oct. 5, with market activity still muted given buyer resistance to restocking.
Offers in the Northern European market were heard at Eur730-740/mt ex-works Ruhr and Eur750/mt delivered Ruhr. Market participants saw tradable value in a range of Eur700-740/mt ex-works Ruhr and Northern Europe, with levels approaching Eur700/mt ex-works increasingly heard in the low-demand market.
The latest deals were reported by a distributor source at Eur765/mt delivered Germany, the equivalent of Eur730/mt ex-works Ruhr.
As such, Platts assessed hot-rolled coil in Northwest Europe stable Oct. 5 at Eur730/mt ex-works Ruhr.
Some positivity was heard in the market for the near term, given the approach of the Euroblech fair later this month, with many looking to the event for the settlement of longer-term contracts and the opportunity to bring some clarity to prevalent uncertainties in the market.
“I think most are waiting for the fair now,” a mill source said. “The whole industry is reducing output, so demand and supply will eventually align.”
Indeed, recent price increases attempted in the market were to an extent premised on reduced supply and availability of coil, with one distribution source expecting further cuts given mills could still offer five- to six-week lead times.
“For this quarter we attempted higher prices, which was largely costs driven, but unfortunately this has to be supported by demand which has dried up,” a second mill source said. “Distributors are looking forward at their inventories, and we will see a degree of recovery, but not to 2021 levels.”
In the Southern market, multiple sources reported a preference from Italian mills to stop production rather than cutting prices, in contrast to Northern European mill strategies.
“[Northern] mills are hungry and looking for orders,” a distributor source said. “But in Italy they’ve followed a different strategy — stopping production over discounting volumes. Their offer levels just aren’t realistic, though.”
Platts assessed HRC stable at Eur725/mt ex-works Italy due to a lack of transactional activity to realize the higher offer levels, heard at Eur760-780/mt ex-works Italy.
Platts is part of S&P Global Commodity Insights.
— Benjamin Steven, Maria Tanatar


Volvo EV sales more than double on year in Jan-Sept, hybrid sales fall
Automaker Volvo Cars sold 128,575 rechargeable vehicles in the first nine months of 2022, down 2.7% year on year, it said Oct. 4.
The total included 32,369 full electric vehicles, or EVs, up 110% year on year, while plug-in hybrid sales dropped 17.5% to 96,206 units.
“Overall underlying demand for the company’s cars remains robust, especially for its recharge range of pure electric and plug-in hybrid cars,” Volvo said.
Total vehicles sales for the January-September period were 428,987 units, down 19% year on year.
In Europe, Volvo’s largest market, 81,314 rechargeable vehicles were sold over the nine-month period, down 11.6% year on year, including 20,574 EVs, up 108.2% year on year, and 60,740 plug-in hybrid sales, down 26%.
Total vehicle sales in Europe for January-September fell 25% to 166,016 units, sales in China dropped 11% to 117,744 vehicles and sales in the US decreased 24% to 72,216 units.
In China, rechargeable vehicles sales for the period rose 15% year on year to 8,251 units, including 1,945 EVs, up 321% year on year, and 6,306 hybrids, down 5.9%.
Volvo’s rechargeable vehicle sales in the US also climbed 21% year on year to19,415 units, including 4,265 EVs, down 3.5%, and 15,150 hybrids, up 31%.
Increased demand for EVs has driven up battery metal prices, with Platts seaborne lithium carbonate and lithium hydroxide assessments surging 120% and 149%, respectively, since the start of 2022 to $74,500/mt CIF North Asia and $79,000/mt CIF North Asia as of Oct. 3, S&P Global Commodity Insights data showed.
— Jacqueline Holman
EC approves Eur1 billion to support Salzgitter efforts to decarbonize steel production
The European Commission said Oct. 4 that it had approved under EU state aid rules a Eur1 billion ($997 million) funding measure to sustain Germany-based steelmaker Salzgitter’s efforts to decarbonize its steel production using hydrogen.
As reported in a separate release by Salzgitter Oct. 4, the approval will secure financing for the first development stage of the company’s Salcos program, to be implemented by the end of 2025. Salcos aims, in three stages between now and 2033, to switch steelmaking in Salzgitter entirely to low-CO2 crude steel production, replacing fossil fuels such as iron ore.
Platts assessed 62% Fe Iron Ore Index at $95.50/dmt CFR North China Oct. 4, down 20.1% since the start of 2022. The 62% Fe Iron Ore Index was at $95.50/dmt CFR North China Oct. 4, up 20 cents/dmt from Oct. 3, according to Platts assessment. Platts is part of S&P Global Commodity Insights.
Salzgitter’s current annual CO2 emissions of around 8 million mt are expected to be reduced by as much as 95% when the new production systems are fully in place.
The EC aid, which will take the form of a direct grant, will be used to replace one blast furnace at the company’s site in Salzgitter, Lower Saxony, with a direct reduction plant and electric arc furnace producing 1.9 million mt/year of green steel. The measure will also be used to build a 100 MW electrolyzer, which will produce around 9,000 mt of renewable hydrogen per year that will be used as feedstock in the direct reduction plant.
The electrolyzer, the direct reduction plant and the electric arc furnace are expected to start operating in 2026.
“This will contribute to the greening of a very energy-intensive and hard-to-abate sector while reducing Germany’s dependence on imported fossil fuels,” EC Executive Vice President Margrethe Vestager, in charge of competition policy, said. “This is a good example of how our state aid framework enables member states to help the EU’s energy-intensive sectors tackle the challenges of greening.”
— Annalisa Villa

Turkish-origin rebar imports awaiting allocation exceed country-specific quota: EC
Turkish-origin rebar import volumes awaiting allocation at the European ports already exceeded country specific quota, according to European Commission data.
According to the EC data, released late Oct. 3, the 100,425 mt of Turkish-origin rebar was awaiting allocation on that day. The EC has a total October-December import quota for Turkish-origin rebar of 90,856 mt.
“It could be worse as far as I know,” one European buyer said Oct. 4. “Romania and Bulgaria are not yet included in that allocation so it can easily be 10,000-20,000 mt on top of that,” the source told S&P Global Commodity Insights, adding that 25% safeguard duties would be applied on all exceeding volumes evenly.
“It’s an individual decision to keep volumes at the port [to avoid safeguard duties],” the source said, adding that if buyers decided to wait for the next quota period to received shipments and store them at the ports, there would possibly be a three-month financing cost incurred and even then, there would be no guarantee that the quota would not exceed next quarter.
Platts’ assessment of Turkish exported rebar was stable at $682.50/mt FOB on Oct. 3, according to S&P Global Commodity Insights data. Turkish mills were currently offering rebars at elevated levels around $690-$720/mt FOB amid high energy costs while sources reported weak demand.
“For the Q1 2023 quota, it’s too early for EU buyers to buy [Turkish rebar] – EU demand is not active as they are consuming their stocks and postponing purchases, but when demand returns Turkey remains the best alternative due to the short lead time,” a Turkish trader said.
Approximately 56,323 mt of imported rebars from other countries subjected to safeguard measures remained out of a quota tally of approximately 132,668 mt, while 76,345 mt was awaiting allocation.
One distributor source in the Benelux region noted that the gap between Turkish imported rebar levels and domestic rebar prices played a significant part in buyers seeking rebars from Turkey, however, no significant import activity was seen for flat steel products in the European market.
Indian HRC steel import quotas
Indian hot-rolled steel imports into Europe dominated the market over the last few quota periods, however, according to EC data published Oct. 3, the market saw low activity for Indian-origin flat steel imports.
For hot-rolled coils, no volumes were awaiting allocation on Oct. 3, out of a country specific quota of 287,227 mt. For the July-September period, 82,226 mt of the allocated quota, remained out of the country specific quota of 287,227 mt. For April-June period, 11,163 mt remained out of a total quota of 314,545 mt.
Some sources noted that the export duties introduced by Indian government in May might have hampered the import volumes for Indian-origin flat steel into Europe. On May 21, the Indian government announced plans, effective May 22, to increase export duties on some iron ore and steel products, including hot-rolled, cold-rolled and coated coils.
“Indeed, the main factors are the then-new export duties and the preference to export boron-added material. Adding boron means the CE mark is lost which excludes all EU service centers for Indian origin purchasing,” an Antwerp-based trader told S&P Global.
“India is also claiming to have a decent domestic market which would limit motivation to compete with lower import levels from other Asian mills such as in Korea, especially under the current export duty,” the source added.
Approximately 22,535 mt of the total October-December quota of 179,365 mt for South Korea-origin HRC was awaiting allocation on Oct. 3.
For Turkey-origin HRC, 9,210 mt of total quota of 452,373 was awaiting allocation as of Oct. 3, according to EC data.
Platts assessed Northwest European hot-rolled coil stable at Eur730/mt ex-works Ruhr on Oct. 3.
— Rabia Arif, Benjamin Steven, Viral Shah