


Polish distributor’s earnings soar, foresees higher mill costs
Bowim saw consolidated sales fall 3% on-year in the first quarter to 127,588 tonnes, but earnings surged. The Polish distributor foresees rising costs for mills that will translate to higher prices for end-users, not all of which will be able to accept.
Revenue surged 29% to PLN 404.1 million ($110.5m). The continuation in Q1 of demand and favourable market conditions that started in Q4 2020, coupled with restricted supply, meant distributors with sufficient finances and ability to react to customer requirements were able to report strong earnings, Bowim says.
Costs grew by only 15.5%, slower than revenue. This helped net profit soar to PLN 32.05m from PLN 2.27m a year earlier.
The expected stabilisation in prices in the first quarter did not occur, with values still rising and reaching new historic highs, the firm points out. A major reason for this is that capacities have been slow to come back online following last year’s idling, while some capacities, such as ArcelorMittal’s Krakow blast furnace, will not return at all.
“The forecasts indicate European steel buyers will need to be ready to accept higher steel costs, also due to the transformation of production processes (furnaces fuelled by hydrogen, which is neutral in terms of CO2 emissions),” Bowim observes in a report seen by Kallanish. Poland is particularly affected due to its dependence on thermal coal, which is becoming increasingly expensive to consume in the EU. These costs are likely to rise further in 2021, the distributor adds.
Although the Covid-19 pandemic has impacted demand in some end-use sectors, there is simultaneously a significant restriction in supply. “European mills have not coped with orders in recent months and are not able to satisfy demand,” Bowim observes. The Covid-19 impact will also be seen in public infrastructure investments in Poland. “The situation is additionally complicated by a level of price increases not seen for years, which raises the question of whether the construction industry will be in a position to accept these prices.”
Adam Smith Germany


Oryx opens new scrap yard in Spain
Oryx Stainless España has opened a new scrap yard in Vilanova i la Geltrú, near Barcelona, it tells Kallanish. The new operation is located in an area with direct access to key customers and high material availability due to significant manufacturing hubs.
The company is 100% owned by the Oryx Stainless Group, one of the leading international processors of stainless steel scrap.
“Oryx Stainless has been active in the Iberian stainless steel scrap market for some years already,” says Oryx España managing director Jorge Rodriguez Cameselle. “Our team is very much looking forward to expanding the relationship with our suppliers and offer a new alternative to the existing buyers in the Spanish market.”
The expansion of the Spanish operation is the next key step in the group’s strategy of becoming a close regional partner of existing and new suppliers, it says.
“We are happy to further intensify our relationship with our business partners in southern Europe,” says Oryx Stainless Group chief executive Tobias Kämmer. “Oryx Stainless España is committed to the Group’s ESG policy and will contribute to the supply of first class secondary raw materials to secure a green and clean production of stainless steel by significantly reducing its CO2 footprint.”
Todor Kirkov Bulgaria
Thyssenkrupp develops steel for electric car noise reduction
A sandwich material proprietary to thyssenkrupp Steel is particularly suitable for noise reduction in electric vehicle construction, Kallanish hears from the company.
Although electric motors are quieter than conventional combustion engines, electric powertrains generate noise inside the electric vehicle that people find unpleasant. Thyssenkrupp Steel claims its material named “Bondal” significantly reduces the noise emission of the so-called inverter, which causes high-frequency sound emitted via the cover of the inverter housing. This noise cannot be satisfactorily solved currently with conventional materials, tk Steel explains.
It describes Bondal as a steel-polymer-steel composite with two steel sheets are bonded into a laminate under high contact pressure by a thin, adhesive polymer layer. The material is particularly well suited for components which are excited to vibrate, it says.
Tk Steel notes it is about to convert one of its Bochum plants into a centre of excellence for e-mobility over the next few years. In the field of non-grain-oriented electrical steel it has invested in a new double reversing mill and a new annealing and isolating line. This will make it possible to produce thinner and stronger grades, which are the basis for more powerful electric motors.
Christian Koehl Germany

Italian coil, derivatives seen increasing after safeguard announcement
The looming EU safeguard announcement is beginning to discourage buyers from purchasing from the import market. Following the expected safeguard extension, sources believe prices for European coil and its derivatives, such as sheet and tube, will start climbing again.
EU safeguard measures are expected to be extended for one year from the beginning of July. According to rumours, the measures could be extended for a period of one year with an increase of tax-free quotas by 5% compared to current volumes (see Kallanish 19 May).
Continued shortages and strong demand, particularly from other European countries, are being reported for Italian hot rolled coil this week, market participants tell Kallanish.
Domestic HRC spot contracts remain stable on last week at a high €1,100-1,180/tonne ($1,340-1,437) base ex-works. Most contracts are however hovering at the low point of the range. Lead times span from the end of July till October and tonnages allocated for spot purchases remain limited.
Cold rolled coil and hot-dipped galvanised coil contracts are also stable compared to last week, but values can go up significantly if customers are ready to pay more for quick delivery. Contracts for both products are at €1,250-1,360/t base ex-works, sources suggest.
While competitive import offers from Asian countries have slowed domestic demand, European buyers are purchasing high volumes of HRC in Italy where service centres and end-users are putting off their purchases. HRC offers from Japan and India have been heard at €1,000-1,020/t cfr and €1,080-1,090/t cfr respectively. Some offers for CRC from India have also been reported at €1,200-1,220/t cfr, sources say.
Natalia Capra France

Uncertainty remains in EU coil import market
The European coil import market continues to be affected by uncertainty, mainly linked with the wait for a final decision on safeguard measures beyond the end of June.
In Italy traders are reporting that some Indian hot rolled coil could be competitive at as low as €900/tonne ($1,097) cfr. Buyers are however already considering the need to apply the 25% safeguard duty due to the fact large tonnages have already been ordered for delivery in the third and fourth quarters.
From Asia some HRC offers were heard at above €1,000/t cfr southern Europe, while Turkish suppliers remain uncompetitive at the moment, Kallanish notes.
For cold rolled coil, Indian sources are offering at €1,190-1,200/t cfr southern Europe. “I have sold Chinese material at the same level, inclusive of anti-dumping duty,” a trader comments.
While many buyers are waiting to understand the decision on safeguard measures, in Italy further uncertainty is also created by the future of the former Ilva mill in Taranto. Future judicial developments there could impact output from September onwards, a source observes.
According to the latest numbers from the official European Commission database, very few duty-free safeguard allocation for coils are still available until the end of June.
Emanuele Norsa Italy
EU, US set deadline to end tariffs related to Section 232: report
The EU and US have set a deadline to end punitive tariffs related to the US Section 232 tariffs as President Joe Biden is set to meet with European officials in Brussels next week, Reuters reported June 9, citing a draft communique.
The seven-page draft seen by Reuters commits to ending a long-running dispute over subsidies to aircraft makers before July 11 and sets a Dec. 1 deadline to end punitive tariffs related to the Section 232 tariffs on steel and aluminum, it reported.
Steel industry sources told Reuters the language may be aimed at retaliatory tariffs on both sides such as those on whiskey and motorbikes, not necessarily the underlying 25% US tariffs on steel and 10% on aluminum, it said.
The EU in May temporarily suspended the application of “rebalancing” duties originally scheduled to be charged on imports of some US products effective June 1, with the European Commission stating the suspension was in the “spirit” of cooperation between the two “strategic partners.”
The EC introduced rebalancing duties in June 2018, initially targeting a list of products worth Eur2.8 billion, which were scheduled to target a further Eur3.6 billion worth of trade as from June 1, 2021. It is this “second tranche” of rebalancing measures that has now been suspended.
— Justine Coyne


Steelmaker Voestalpine to convert three blast furnaces to EAFs by 2030
Austrian steelmaker Voestalpine will convert two blast furnaces at its Linz site and one at its Donawitz site to electric arc furnace based steel production by 2030 in a bid to reduce carbon emissions by 30%, the company told S&P Global Platts June 9.
At its press call June 9 on the steelmaker’s full-year results (April 2020-March 2021), CEO Herbert Eibensteiner said the company has applied for funding of its “greentec steel” project and that once funding is given, further steps can be unveiled. The company noted that it aims to achieve climate-neutral steelmaking by 2050 using both green electricity and green hydrogen.
When asked by Platts for more details of the project, a company spokesperson told Platts that the blast furnaces to be converted are the smaller furnaces at the Linz and Donawitz sites but that the project is dependent on sufficient accessible renewable energy at competitive prices.
The company said that Voestalpine can provide low carbon steel already and said that it is seeing increasingly more inquiries from customers.
The flat steel mill in Linz is running at full capacity now following the restart of one blast furnace in September. Order books at the steel division are currently at the end of this year amid the market’s steel shortage.
Steel market recovery from mid-2020
Voestalpine saw strong financial results for the business year 2020-21, though they were still impacted from the company’s Q1 (April-June 2020) when the first wave of coronavirus led to demand slumps.
Voestalpine said that, though steel shortages persist, partially resulting from a quick rebound in car production from mid-2020, the company also sees some drop in auto demand as the automotive industry had to curtail production due to the semiconductor shortage recently.
“The unexpectedly strong rebound in demand triggered delivery bottlenecks in the semiconductor industry, with the result that automotive production had to be curtailed a bit during the business year’s final months owing to the lack of electronic parts. Demand for high-quality steel in vehicle production remained very high nonetheless,” said Voestalpine.
The steel division saw revenues decrease by 7.7% year on year to Eur4.2 billion for the full business year 2020/2021 with Q3 and Q4 being strong months as the steel market recovered from mid-year 2020.
The new stainless steel plant in Kapfenberg is expected to become fully operational mid-2022.
The company also expects that if the steel shortage continues, which led steel prices across Europe spiral to record-highs this year, more import material will be coming to Europe. The daily Platts assessment for hot-rolled coil stood at Eur1145/mt EXW Ruhr, continuing on all-time highs since March this year. The assessment was at its lowest point in June 2020 at Eur395/mt EXW Ruhr.
“We expect the current upward trend of the broad economy to continue at least until the end of calendar year 2021. The massive economic stimulus packages in the EU and the US should support the economy also in the medium term,” Voestalpine said.
— Laura Varriale
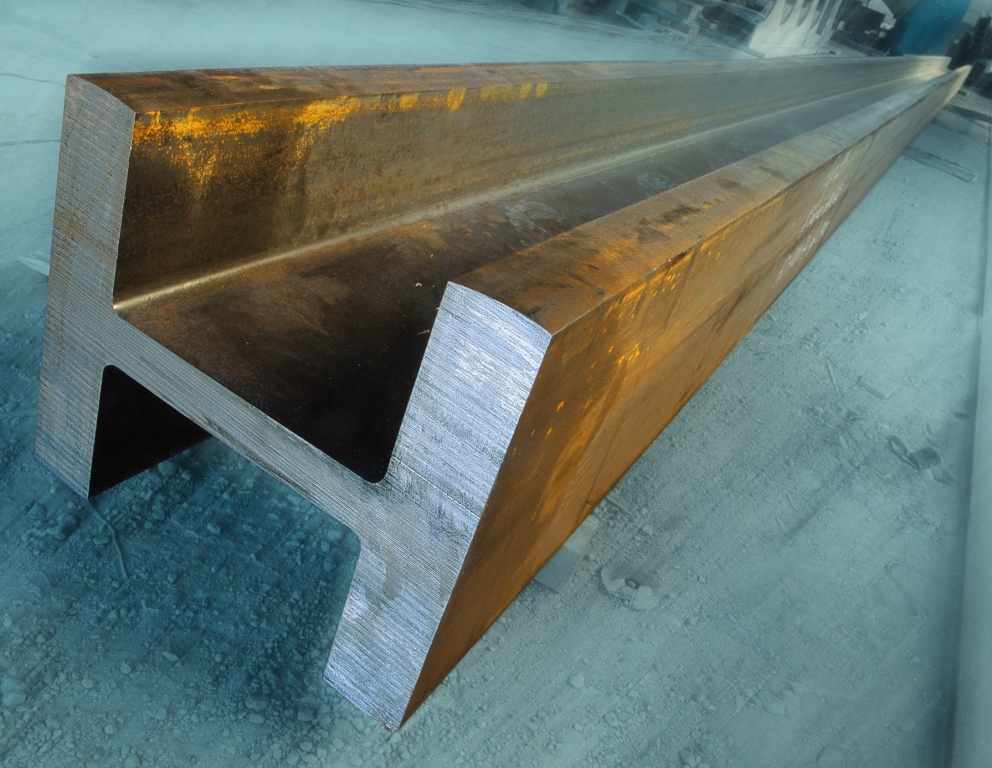
EU steel sections prices keep rising amid limited supply
European domestic steel sections prices continued to gain in the week to June 9 amid limited supply, market sources told S&P Global Platts.
S&P Global Platts European medium sections price (category 1, S235 JR) was assessed at Eur960/mt delivered June 9, up Eur10/mt week on week.
One European mill source noted mill offer and deal values at Eur970/mt delivered, as the mill aimed to achieve Eur1,000/mt delivered by the end of the week. Strong demand and limited supply is helping mills push prices higher, the source told Platts, adding that other mills are already offering at Eur1,000/mt delivered. Offers are for July production with deliveries expected in the second half of July.
However, “German mills have very little material left to sell in July and they are offering August production and at above Eur1,000 for category 1. Prices in Germany are higher, but Italy is getting close to Germany’s levels,” he told Platts.
One distributor source in the Benelux region also reiterated strong demand as prices for long steel products continued to rise during the week.
“The more the mills increase their prices, the more they sell. Prices are increasing on a weekly basis. I am hearing [that the trend] is not going to stop. Orderbooks are full, so I don’t see any change in prices till September,” he told Platts.
The source also emphasized that the German market is pushing overall prices for long steel products in Northwest Europe higher. The source put a tradable value for medium sections (category 1, S235 JR) at Eur950/mt delivered Benelux.
— Rabia Arif, Staff
European HDG market stabilizing as automotive demand softens
The European HDG market was stable June 9, with customers now acting more cautiously as prices have now reached their peak, with more buyers are weary of sitting on overpriced stock. Mills were still having production difficulties amid working through large backlogs and contending with imminent maintenance periods, sources told S&P Global Platts.
Automotive manufacturers were heard to be producing less due to the ongoing semiconductor and microchip shortages, with many previously agreed volumes now being allocated to other buyers in desperate need of material. The softening in demand from auto has been welcomed by some, who are now able to receive material for as early as December, compared to the usual Q4 lead times of January 2021.
One German distributor was confident there would be no automotive shutdown, with the semiconductor supply issues expected to be resolved by next year.
“There will still be a need to restock, but the semiconductor issue will be finalized, until next year I don’t think they’ll shut plants down,” the distributor said. “We still see standstills at Ford, Audi for the summer, but we’ve heard the 16 largest producers for cars had the best results ever in the first quarter of 2021, so they’re not suffering.”
The same source stressed that supply shortages were not only evident on coils, but across the entire supply chain, particularly for packaging materials like wood, paper, and plastics.
“We are short on all material, wood, paper for packaging. What’s going to be the situation for the whole supply chain in the second half of the year?” the source said.
Discussions for new procurement were now heard to be going ahead for January-February.
“We have time because tonnage for this year is already booked, and there is no real volume for trading. Everyone is waiting for custom clearances at the port, and we’ll see mills coming out with volume for next year,” the same distributor said.
In Italy, a distributor source added that he was also treading cautiously with original equipment manufacturers due to the incredibly high prices for HDG in Europe.
“It’s just a matter of which level the final OEM is able to except. The price level is so high and there is now a huge gap in prices between the USA and the EU.”
Despite the current slowdown in auto demand, the source said he was certain that producers would return from September onwards with requests, spelling a “good Q4.”
— Amanda Flint

Arvedi approaching full capacity output, seeking carbon neutrality: sources
Arvedi, Italy’s second largest steelmaker, is set to produce 3.6-3.8 million mt of hot-rolled coils this year, close to its installed capacity, a source close to the company told S&P Global Platts.
Arvedi has two electric arc furnaces (EAFs) at its headquarters mill in Cremona. The No. 1 furnace has 1.4 million mt/year of crude steel capacity and the No. 2 furnace was upgraded and expanded last year to increase its capacity to 2.6 million mt/year.
Demand for flat-rolled steel coils in Europe is booming with buyers struggling to find material at prices that are at their historical peak. Hot-rolled coils, ex-works Ruhr, moved from Eur665/mt at the end of last year to Eur1145/mt June 9 while hot-dip-galvanized sheet moved from Eur750/mt to Eur1300/mt.
In the same time frame HRC prices in Italy moved up by Eur472/mt ex-works, while HDG went up Eur550/mt, according to S&P Global Platts data.
Arvedi, which uses scrap for its production, is also planning further investments at its mill in Servola (Trieste). At the beginning of the year the company secured a Eur240 million “green loan” guaranteed by SACE, the Italian Export Credit Agency specialized in supporting the growth and development of businesses and the national economy in compliance with the EU’s environmental targets.
As reported by Platts, the investment is planned for the green conversion of steel mills in Trieste and Cremona. In Cremona the company has already used part of the money to upgrade EAF No. 2, while in Trieste it has plans to use Eur86 million for the construction of new sheet galvanizing and painting capacity.
The source told Platts on June 9 that the company has ordered the galvanizing and painting installations from Danieli, which will also construct an extra galvanizing line and a plant that will produce hydrogen to feed re-heating furnaces using photovoltaic electric energy.
The two galvanized lines will have capacity to produce 600,000 mt/year of finished products while the pre-painted/color coating line will be able to produce 150,000-200,000 mt/year.
Arvedi shut two blast furnaces at Servola, although only one was operational, producing 400,000 mt/year of pig iron. After the Servola shutdown, the former Ilva, now known now as Acciaierie d’Italia, is the only Italian steel producer that has blast furnaces.
Arvedi did not respond to a Platts request for comment before the editorial deadline. Danieli confirmed that contracts for one galvanizing and one color-coating line have been awarded so far and did not provide further details.
— Annalisa Villa