


Partanum Consulting joins EUROMETAL as associate member
Partanum Consulting GmbH will become an associate member of EUROMETAL as of January 2022.
CEO of Partanum Consulting is Friedhelm Wagner, a former Managing Director of Klöckner Global Sourcing GmbH (a subsidiary of Klöckner & Co SE) and former member of Management Board of ThyssenKrupp Schulte.
Friedhelm Wagner is since 45 years active in steel trading and steel distribution on national and international level:
- active since year 2013 in procurement and sales of specific raw materials for steel production;
- specialised in Steel Procurement & Sales of 2nd choice/declassified carbon steel flat & long products in cooperation with a German company responsible for purchase & sales;

- cooperation with a German company for the implementation of Energy Efficiency in the light of Co2 reduction processes for Steel Service centre, Steel mills & Steel – Distribution companies and a general and specific cost optimization program.
- cooperation with a German company for coaching of sales- people based on Total Quality Selling (TQS) which is the method hat considers the entire sales process from the receipt of an inquiry, or the first acquisition contact, up to the final sale including price negotiation & -adjustment processes.
HDG market participants uncertain about strong auto comeback in Q1
European hot-dipped galvanized steel prices softened Dec 22 as the market contended with hand-backs from automotive manufacturers amid the semiconductor shortage and the uncertainty of prices in the new year. Sentiment remained mixed about how quickly automotive demand would return in Q1, with some on the buy side still apprehensive to book if lower prices could be on the horizon, sources told S&P Global Platts.
A German distributor said mills were still trying to lock in key business by handing out discounts and added he did not consider the return of automotive demand to be a strong point for the new year.
“Mills are really under pressure to fill order books,” the distributor said. “For auto, it’s not the problem of microchips — it’s a problem of our future. Auto will never come back to their own strengths before this crisis because more countries are ruling that electric vehicles will be the future. They won’t need the same amount of steel; demand will go down.”
In the Italian market, a service center source was still skeptical about the strong return of the auto industry in Q1, despite chatter that major car manufacturer Stellantis was looking to restart production in the near term.
“No movement in automotive, no strong demand,” he said. “Stellantis are starting to allocate production, but not sure if this is the case.”
Others were more optimistic about a bounce-back, with some sources expecting a strong rebound in automotive demand and prices in Q1.
A European mill source said his forecast for Q1 was mostly focused on securing March orders with a “much better view” on automotive demand. The source confirmed that several OEMs had already announced more working shifts because of an easing in the shortage of auto components.
“Stellantis announced microchip and semiconductor issue is better for them,” the mill source said. “January is already better and am expecting peak demand.”
The source added that last week at a conference, a car manufacturer confirmed the restart of night shifts after Jan. 3 because of more availability of components.
“Auto has been low during the last quarter and it hit the mills — auto represents 20% of total production,” the same source said,
“Should they shut down completely or make discounts? That happened, but it’s over now,” the source said, highlighting bullish expectations for 2022.
— Amanda Flint

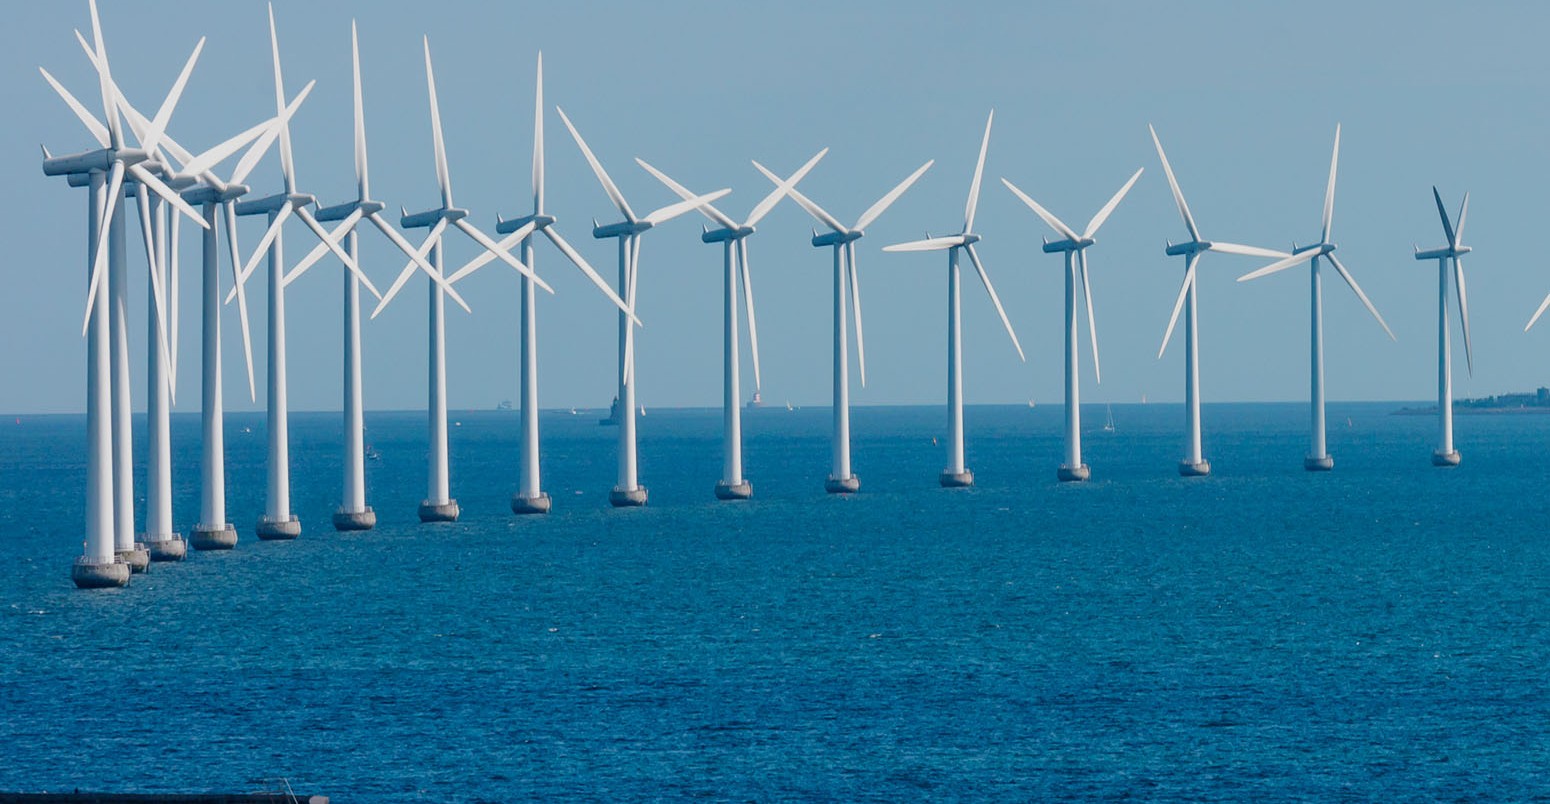
Tata Steel UK supplies sections for Dogger Bank wind farm
Tata Steel, which has steelmaking operations in the Netherlands and the UK and manufacturing plants across Europe, said Dec. 22 its UK-made steel is being used to create the world’s largest offshore wind farm, Dogger Bank, 130 km (81 miles) off the northeast coast of England in the North Sea.
Steel made in Tata Steel’s Port Talbot plant and processed into hollow sections at the company’s Corby and Hartlepool sites, all in the UK, is now being fabricated by one of the thousands of contract companies engaged building the first two phases of the Dogger Bank wind farm.
Tata Steel is supplying about 250 tons of steel per wind turbine. To endure the North Sea environment, this is made of the fully normalized hot finished hollow sections of EN 10210, designed to perform in the most arduous conditions. These hollow sections are going into the access platform and associated steelwork — the connection between the wind tower foundation and the jacket above.
Dogger Bank’s first two phases were reported to use 190 13MW offshore wind turbines, but the steelmaker has not specified whether its steel will be used in all of them.
“Huge amounts of steel will be needed to help the UK achieve its net-zero goals — to build everything from renewable energy and low-CO2 transportation to hydrogen production and distribution,” said Sandip Biswas, chairman of Tata Steel UK.
Based on the expected need for carbon capture, utilization and storage and hydrogen infrastructure, this additional demand for steel is likely to run into more than a million tons by 2050, according to industry estimates.
— Ekaterina Bouckley

Global output slows further in November
Crude steel production in the 64 countries reporting to the World Steel Association (worldsteel) fell for a fourth consecutive month in November, by 9.9% on-year to 143.3 million tonnes. This was again the result of China, despite US and EU output growing, Kallanish notes.
On an on-month basis, global output was down 2%.
Chinese crude steel output slumped 22% on-year in November to 69.3mt. Indian, Japanese and South Korean production however rose 2.2%, 10.7% and 2.7% respectively to 9.83mt, 8.04mt and 5.92mt. Vietnamese output grew 6.7% to 1.91mt.
EU27 production grew 3.7% in November to 12.92mt, despite German output inching down 0.3% to 3.37mt. Italian output rose 6.3% to 2.18mt, while French growth was only 0.1% to 1.15mt, but Spanish production dropped 2.2% to 1.15mt.
Turkish production grew 6.1% to 3.42mt.
US production growth remained strong, rising 13.8% to 7.17mt in November, while Brazilian output grew 2.5% to 3.09mt.
CIS production is estimated to have risen 5.8% to 8.78mt, with Russian output estimated up 9% to 6.45mt and Ukrainian production confirmed down 0.2% to 1.73mt.
Global crude steel production in January-November nevertheless still rose 4.5% on-year to 1.75 billion tonnes, but slowed from 5.9% growth after ten months.
Adam Smith Germany


Vitkovice Steel appoints new chief executive
Vitkovice Steel has appointed chief financial officer Radek Strouhal as chairman and chief executive effective 1 January, replacing Dmitrij Ščuka who will leave the company after over ten years.
“The change in the company’s board of directors will not have any significant effect on the company’s day-to-day operations,” Strouhal says in a note seen by Kallanish. “We will continue to focus on our long-term priorities, in particular the quality of our products and services, and strengthening competitiveness.”
The Czech plate mill has bounced back into profit after several loss-making years, posting a CZK 25 million ($1.1m) net profit in the nine months through September. This was supported by strong steel demand and production efficiency improvement. The firm said the outlook was also positive despite rising utility prices.
Last year Vitkovice posted a CZK 267m loss. This was still better than previous years. The previous time the firm posted annual profit was in 2017 but this was due purely to high exchange rate profit from revaluation of shareholder loans. Before that, the firm last registered profit in 2008.
Vitkovice has a 755,000 tonnes/year capacity plate mill and seldom-used 170,000 t/y heavy sections mill. The firm switched to sourcing merchant slab when it shut down its 950,000 t/y electric arc furnace-based meltshop in 2015.
Adam Smith Germany
Liberty Czestochowa’s new strategy eyes 85,000t monthly shipments
Liberty Czestochowa is aiming to reach 85,000 tonnes/month of plate shipments by end-2022, Liberty Steel Group’s new chief executive, Greensteel EMEA, Toker Ozcan, said during his first visit to the Polish plant this month.
The target is part of Czestochowa’s new “55-65-85” strategy, which will initially target shipments of 55,000 t/m by April 2022. This will be supported by a revamp of the plate mill in 2022, which will include upgrades to both cutting lines, as well as by streamlining logistics and improving the loading of plate. Also part of the new strategy will be the recruitment and training of new production workers.
“The goal of Liberty is to produce Greensteel, using modern technology, so that we can achieve carbon neutrality by 2030,” Ozcan said. “It is clear to me, having visited the Huta, that the team here are already working hard to achieve that goal. I believe Czestochowa has great potential if we can continue to improve our production.”
Last month Czestochowa resumed producing prefabricated steel products after a break of over a year due to the plant’s previous financial issues (see Kallanish passim). In August the firm said it plans to increase overall production to 1 million tonnes/year and boost its workforce after increasing output to the plant’s highest monthly levels since 2017.
Liberty took over the lease of the 700,000 t/y EAF and 1.2 million t/y heavy plate capacity Huta Czestochowa from Sunningwell International last December. It then completed the acquisition of the Polish plant at the end of May after being the only bidder in January’s sale tender.
Adam Smith Germany
German stockholders return to ‘normality’ in third quarter
For Germany’s stockholding distributors, “normality kicked in” going towards September, their association, BDS, states in its review of the first nine months of the year.
By September, members had caught up from a low level of inventories throughout the entire first half-year, which was marked by good sales. A look at inventories suggests sales could have been even higher if supplies of steel had been too. This applies especially to all strip products, says BDS head of research Jörg Feger.
At the end of June, inventories totalled 1.92 million tonnes, 10% lower than one year earlier. September was then the first month in which the level was up on the corresponding time in 2020, by 3% at 2.16mt.
Sales in the third quarter came to 2.63mt, which was only slightly more than in Q3 2020. From January through September, sales totalled 8.24mt. Expressed in days of shipments, stocks during the first half were less than 60 days. By September, they stood at 72, which BDS considers still low.
Since then, the picture has apparently changed, with particularly high inventories observed at flat steel service centres, Kallanish hears from market sources. In the latest figures by EUROMETAL, the European stockholders association, strip mill products shipments fell 12% in October year-on-year. The same drop occurred in the long products segment. Stock volumes of long and other products stood at 79 days of shipments in October, compared with 66 days in October 2020, EUROMETAL says.
Christian Koehl Germany

Federacciai demands prime minister meeting to tackle energy
Federacciai has asked Italian Prime Minister Mario Draghi for an urgent meeting to address the issue of rising electricity and gas costs that are strongly impacting steel producers, the national steelmakers’ association confirms.
“The situation of our sector today is very critical, so much so that several companies are at risk of closure,” association president Alessandro Banzato says in a document sent to Kallanish. “If we do not intervene immediately to try to mitigate an energy cost that is now unsustainable, not only for families but also and above all for companies, the great risk is that many will stop producing and that we will not be able to achieve the recovery … It is therefore urgent that Draghi opens a discussion table to find effective and suitable solutions in the shortest possible time to solve or at least contain this problem.”
Italian steel trade association Assofermet previously asked the government to come up with urgent measures to combat the skyrocketing increases in costs of electricity and gas (see Kallanish passim). In a letter to authorities, it said there is an evident need to conceive structural measures to allow companies to plan for the future on a solid basis.
Natalia Capra France
Full inventories hurt northwest European service centres
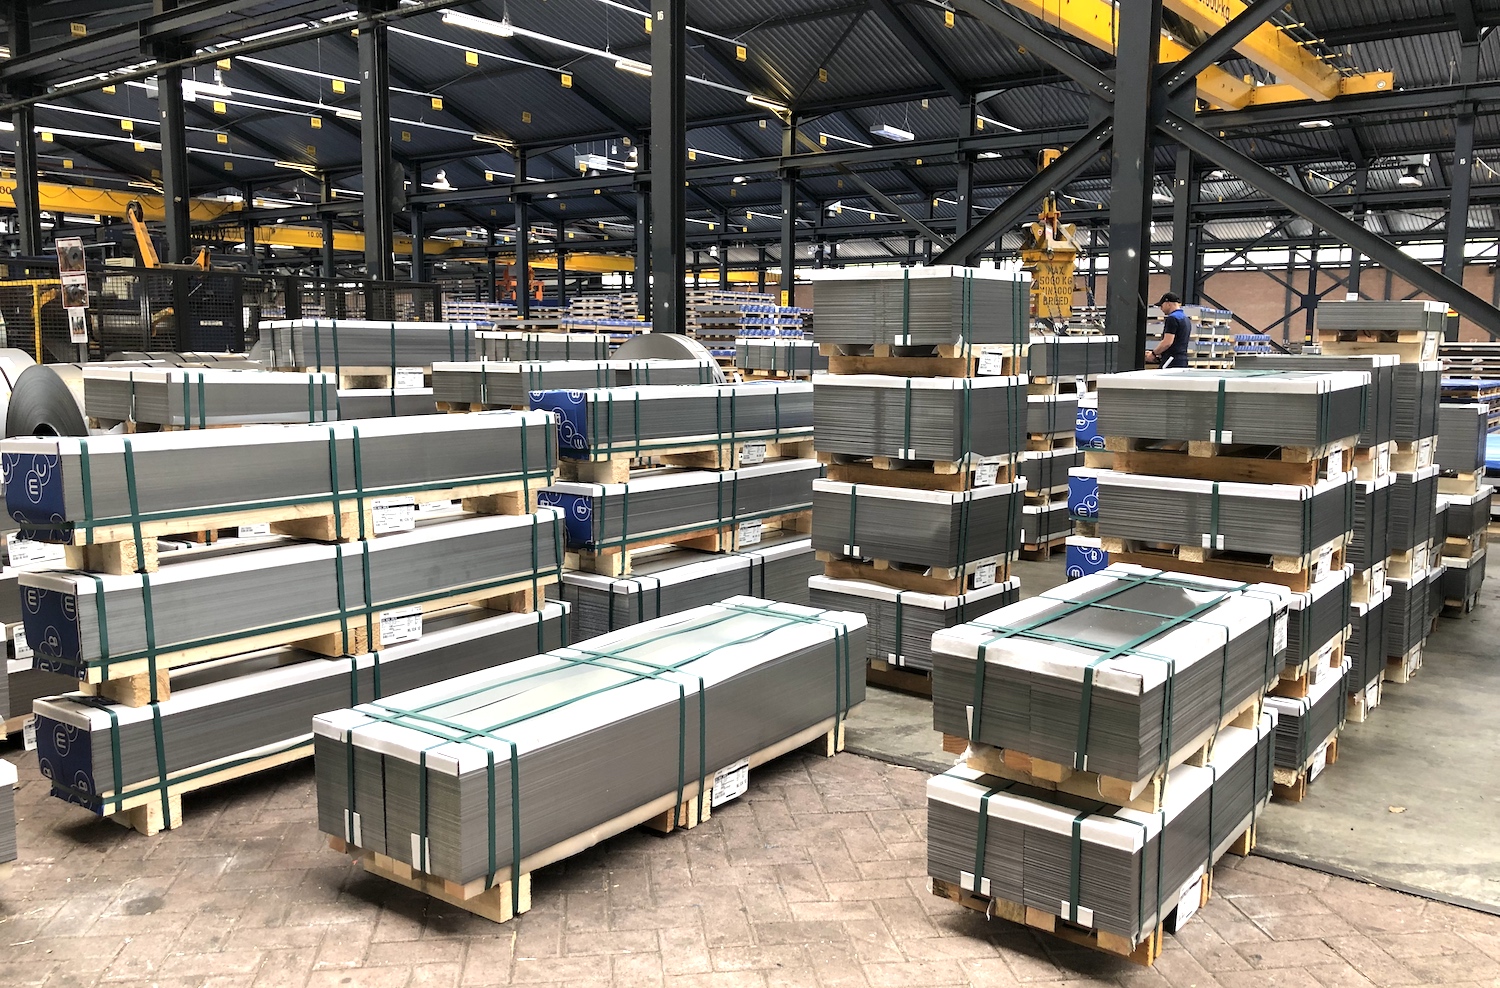
High stock levels are putting northwest European steel distributors, especially coil service centres (SSCs), in an awkward position on the intake as well as on the selling side.
They have little ambition to fill a full house with even more material, which makes them bad customers for mills upstream these days. If they do buy, it is only at low prices. But they are keeping discreet about it as they want to maintain the image of higher prices to their customers downstream.
“SSCs have plentiful material in their inventories which they bought at peak prices, so of course they try to get a good euro for it,” an observer from a regional mill tells Kallanish. According to European distributors’ association Eurometal, stocks at steel service centres in the EU expressed in days of shipments reached 63 days in October, up from 57 days in October 2020.
German SSCs have stood out from the crowd recently, citing relatively high prices from mills and denying that hot rolled coil can be had for less than €970/tonne ($1,097). This contrasts to transactions of €930 cited by a German multi-purpose distribution group. A Dutch service centre manager even sees the low end at €900, on the assumption that prices in the Benelux tend to be below those in Germany.
An explanation for this spread comes from a buyer of an automotive supplier, who doubts SSCs are all truthful with the figures they cite. “Their statements are diplomatic. They have their houses fuller than ever, and do not want to sell the expensive material too cheaply. For them, it is legitimate to make the market believe that mills’ prices are still close to their peaks,” he comments.
Christian Koehl Germany
Italian beam producers stop sales
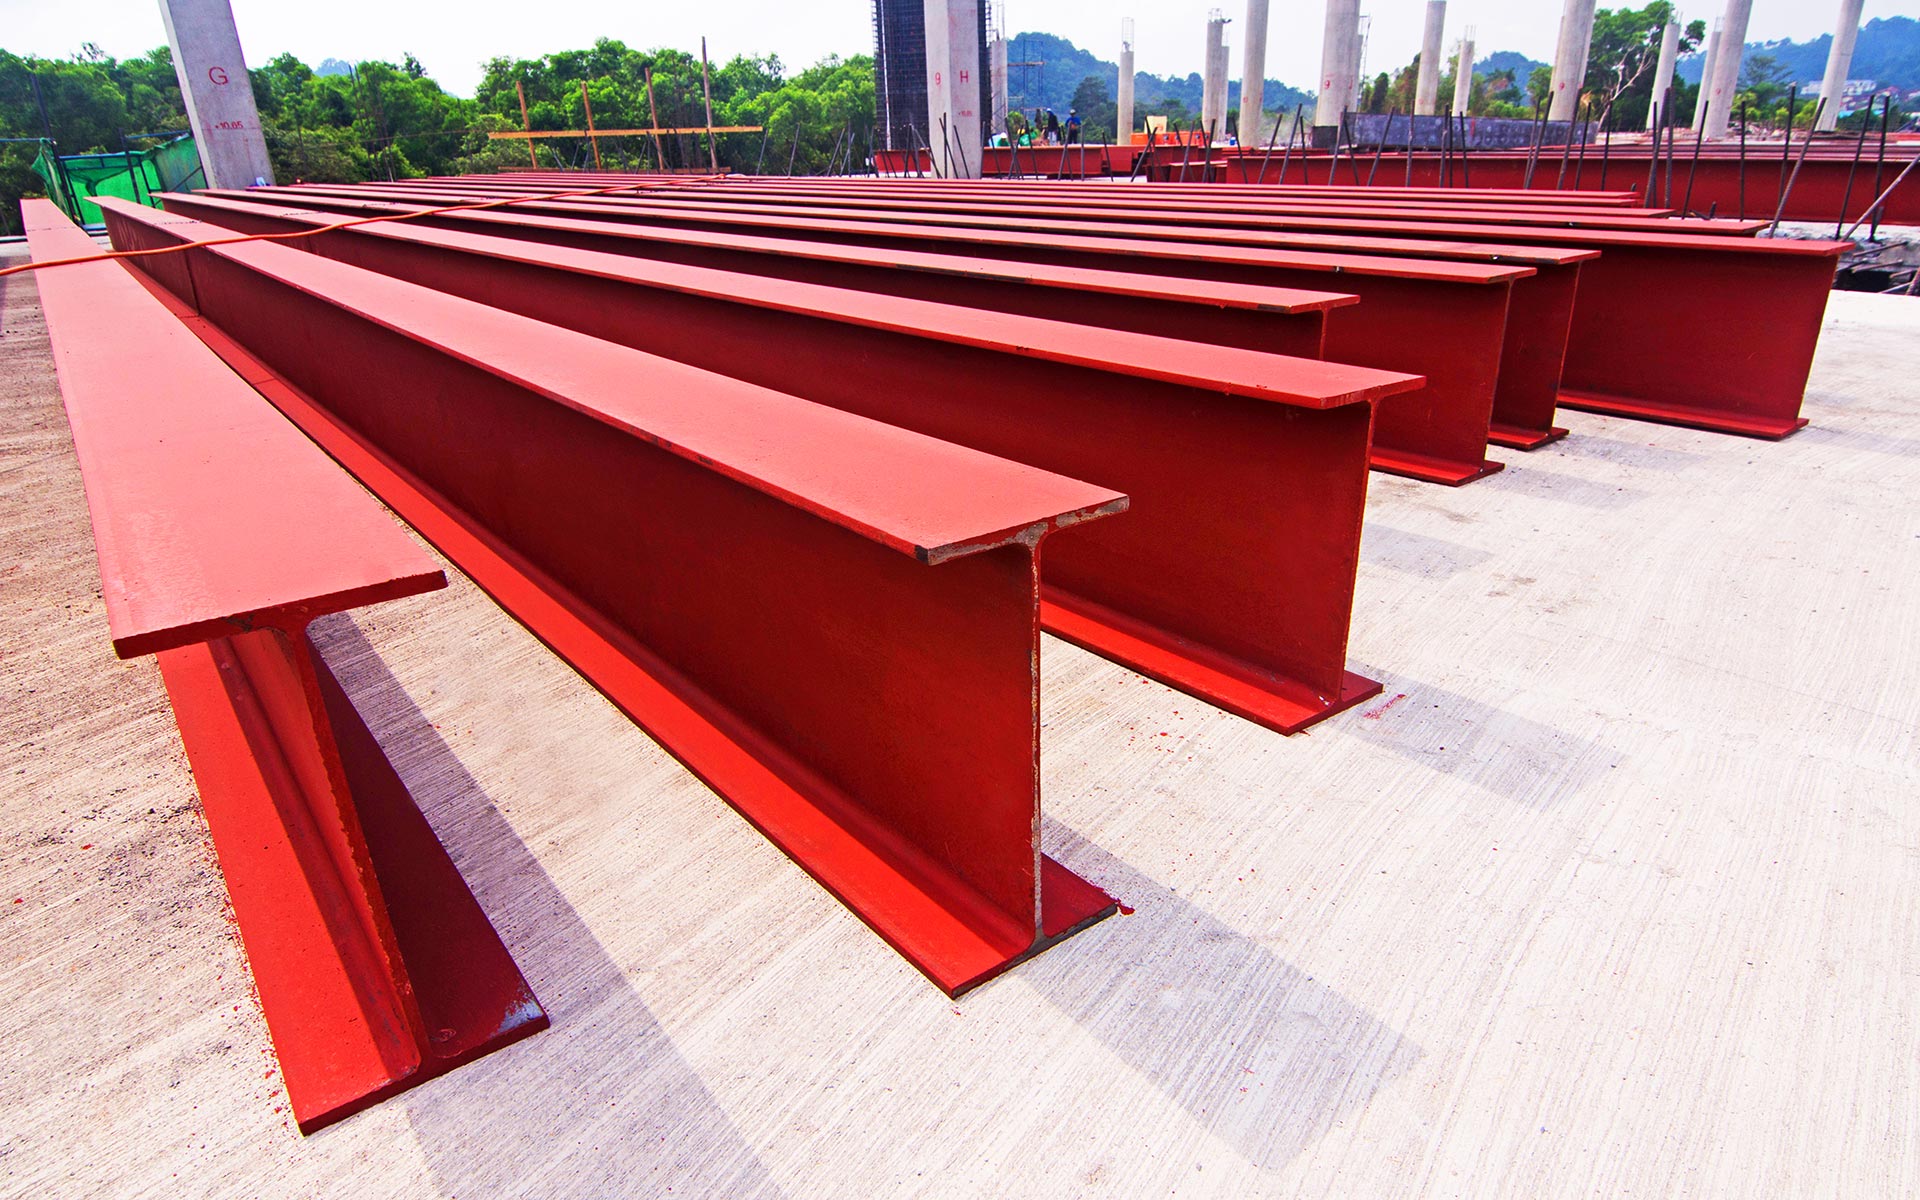
Italian sections producers and their distribution branches are stopping sales this week, in line with other long products makers in Italy (see separate article). Sources believe steelmakers will return to quoting from 10 January after the Christmas holiday break, Kallanish hears.
The leading producer in the market is also idling production for three weeks starting this week.
Prices for the first category of sections remain stable compared to the beginning of the month in a market that seems to be already on holiday. Large service centres have this week continued to implement high discounts to get rid of stock. December purchases by distributors of long products are said to have been rather weak.
Prices for the first category of beam remain at €570-580/tonne ($642-653) base ex-works. Including €380-390/t average size extras, domestic beams start at €950-960/t ex-works. Values increase by €20/t for each subsequent category, sources suggest.
Meanwhile, merchant bar prices also remain stable at €470-500/t base ex-works. Including size extras, values stand at €890-910/t ex-works.
Natalia Capra France