Cost prevents military equipment scrapping: Ukraine scrap association
The cost of turning a tank or armoured vehicle into ferrous scrap for steelmaking is prohibitive, according to Ukrainian scrap metal association UAVtormet.
“It is necessary to carry out a number of costly operations, which may exceed the price of the generated raw material,” it claims.
The association also expressed doubts about the assertion that the weight of all destroyed Russian equipment that can be melted down for scrap is 85,000 tonnes, Kallanish notes.
According to UAVtormet, this figure is much lower, since part of the captured military equipment – some 20-40% – is being restored, repaired and dismantled for spare parts.
The association also considers it impossible under martial law to remelt tank armour into plates for bulletproof vests. “The chemical composition of the armoured steel of tanks and the steel used for the production of body armour plates is somewhat similar,” it says. “For the manufacture of armoured plates, it is necessary to smelt steel, produce rolled products, heat treat them, cut plates from rolled products. Unfortunately, in wartime conditions, such a process cannot be ensured.”
Earlier, UAVtormet said it is studying the rollout of equipment to process military hardware into ferrous scrap amid Russia’s invasion of Ukraine (see Kallanish passim).
According to Forbes, the Ukrainian military has turned 5,000 Russian military vehicles into a pile of 85,000t of scrap, worth $45 million.
Before the war, national steel association Ukrmetallurgprom predicted Ukrainian steelmakers will consume about 3.84 million tonnes of ferrous scrap in 2022. Metinvest estimated its need for scrap this year at about 1.9mt.
In January-March, Ukrainian enterprises reduced procurement of ferrous scrap by 40.2% on-year to 556,500t amid the war.
Svetoslav Abrossimov Bulgaria

Marcegaglia updates stainless tubes price list
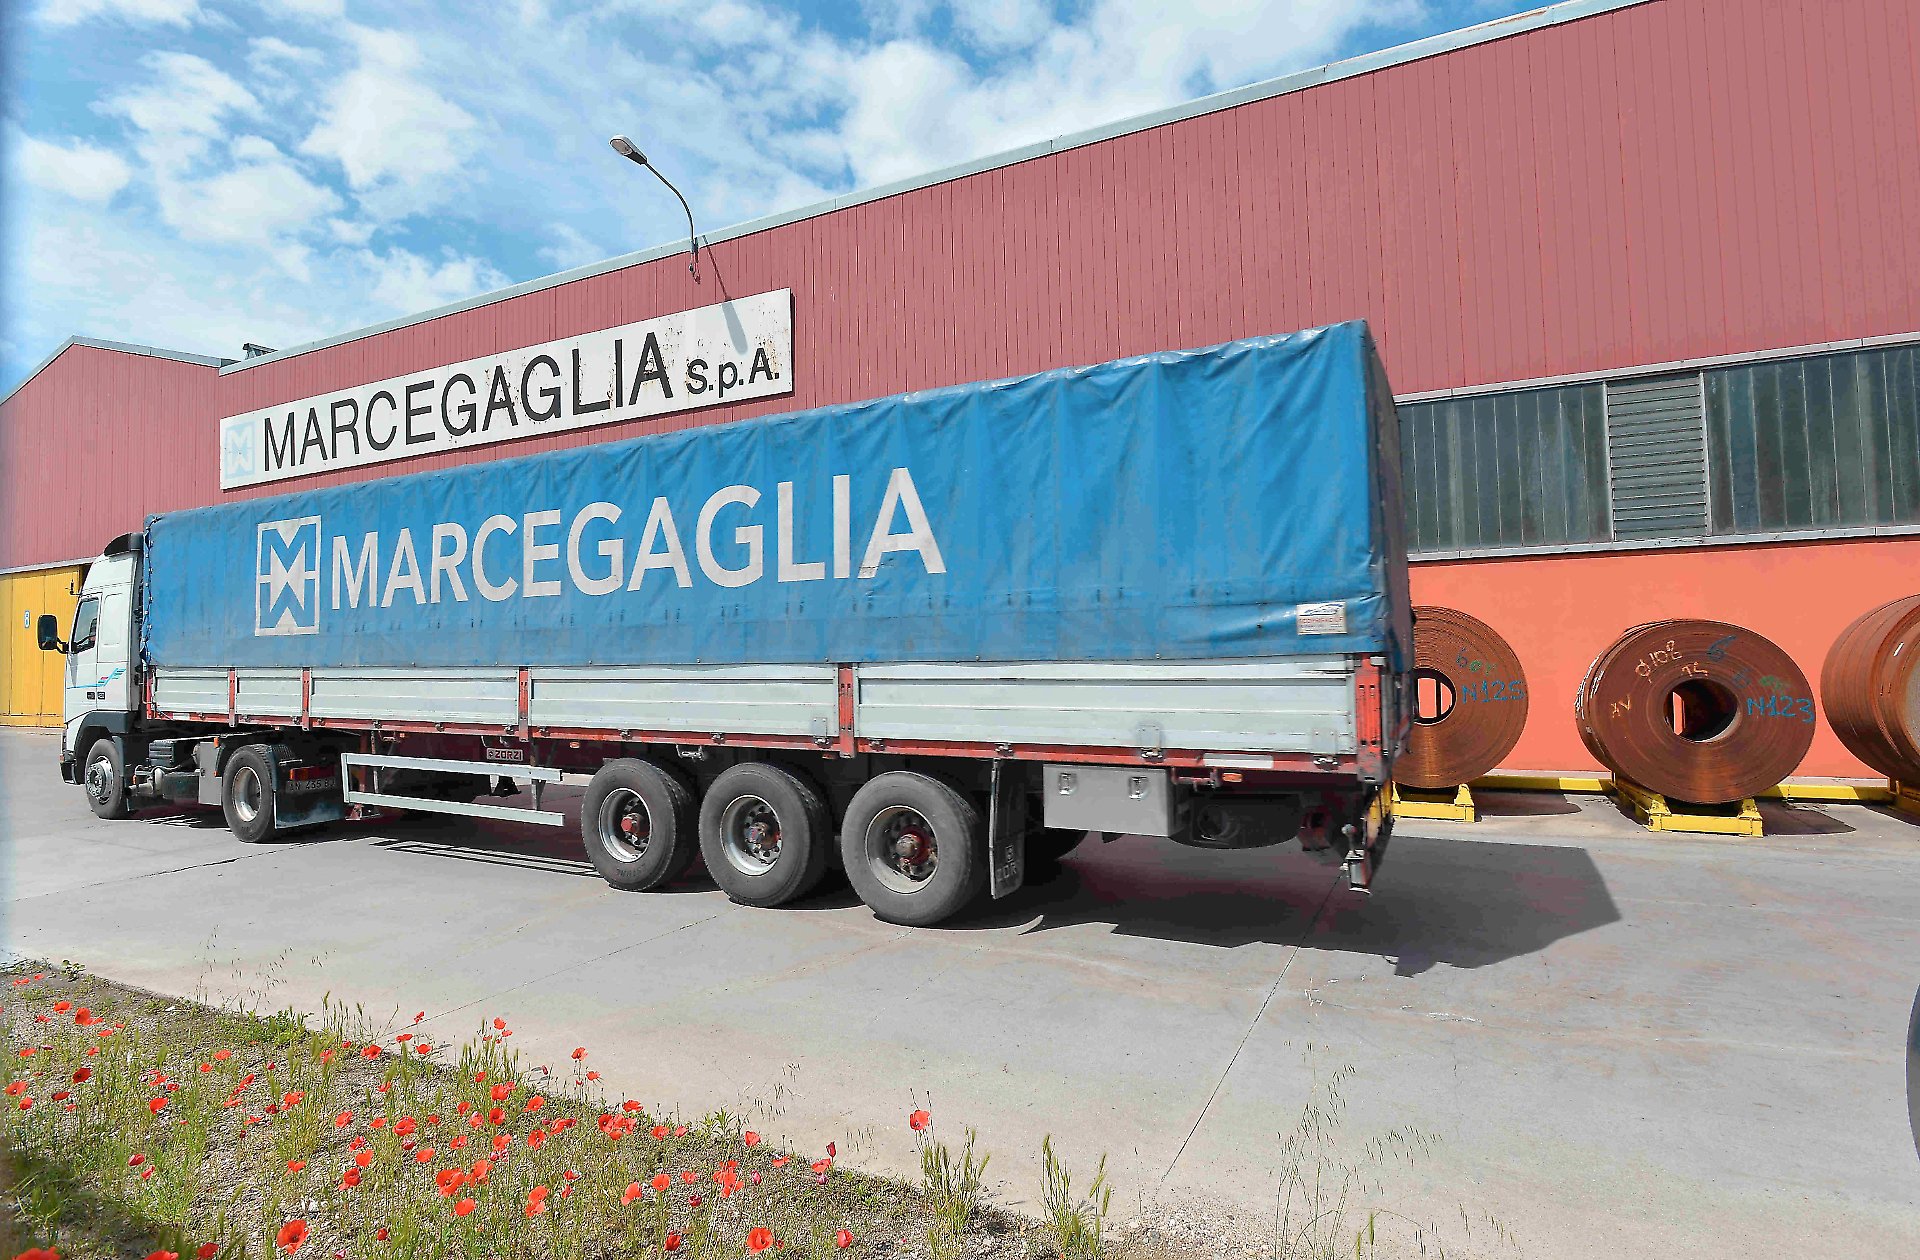
Italian re-roller Marcegaglia is updating its stainless steel welded tube price list, increasing values in line with hiking processing costs, and skyrocketing prices of coil and other raw materials, Kallanish learns from the company.
The new price list will be effective from 2 May and will only involve decoration stainless tubes. Prices will increase particularly for the lower thicknesses, for which processing costs continue to rise.
“The new price list has become necessary due to the increase in production and processing costs, also with regard to polishing, mirror polishing and packaging of materials. The costs of the raw material and the new thicknesses price gap were also taken into consideration,” says Marcegaglia specialties purchasing & sales director Egidio Bini.
Prices of European stainless steel hot and cold rolled coil, and coil derivatives are increasing due to skyrocketing alloy surcharges in Europe.
Outokumpu has increased its surcharges for May. The new figure for grade 304 (1.4301) is €3,844/tonne ($4,049), up from €3,251/t in April. According to the formula applied by all steelmakers to calculate coil prices, €3,844/t will be added to the base price of €1,600/t. This gives a new value for CRC of over €5,400/t delivered, a price considered unacceptable by many buyers.
Aperam has also increased alloy surcharges again for May, by over €400/t on average versus April. The surcharge for grade 304 (1.4301) has gone up from €3,282/t in April to €3,656/t, effective 1 May (see Kallanish passim).
Natalia Capra France

Polish market normalises, concerned over supply/demand gap: conference
The gap between increasing Polish steel consumption and stagnant domestic production is widening, at a time when the massive looming energy transition will require more steel for projects in Poland, according to Polish Steel Association (HIPH) president Stefan Dzienniak.
ArcelorMittal’s Krakow hot-end, shut down for good in 2020, was the first victim of competition from countries beyond Poland’s eastern borders. When demand rebounded strongly in 2021 after the initial Covid-19 pandemic shock, the required domestic supply was therefore not there to meet it, Dzienniak said at this week’s European Economic Congress in Katowice monitored by Kallanish.
Polish apparent steel consumption reached 15.3 million tonnes in 2021, double the tonnage of 2004, but crude steel output remained at the 2004 level of 8.45mt.
In 2021, Poland imported 4.23mt of steel from outside the EU, up 42% on-year. Much of this came from Russia, Ukraine and Belarus. The Russian invasion of Ukraine therefore spurred panic in the Polish market last month, reflecting in surging prices. This was exacerbated by record-high raw material prices since 2021, and surging electricity costs, Dzienniak added.
The output/consumption gap shows Poland is still dependent on imports and will need to fill the gap left by absent CIS supply following the outbreak of war in Ukraine, said Polish Union of Steel Distributors (PUDS) chief executive Iwona Dybal. The market situation had been normalising following the panic seen in March, but Russia’s decision to cut gas supply to Poland and Bulgaria has now created fresh uncertainty, she added.
Other participants agreed the market has calmed following the initial shock of the Russian invasion. “The ground was cut from under our feet in March,” said Stalprofil ceo Henryk Orczykowski. Mills sometimes cancelled orders, sometimes abruptly raised prices, he added.
Cognor ceo Przemyslaw Sztuczkowski responded by saying there was a small pause in offering but that the firm always honours its contracts. “We have steel to sell, it’s waiting in the warehouse; please order and we will deliver straight away,” he commented.
Adam Smith Germany

Europe HRC prices down on lack of demand, oversupply
European hot-rolled coil prices fell on Thursday April 28 with market participants becoming increasingly convinced that the market was due for a significant move downward, sources told Fastmarkets. Fastmarkets calculated its daily steel HRC index, domestic, exw Northern Europe, at €1,270.56 ($1,345.59) per tonne on April 28, down by €28.61 per tonne from €1,299.17 per tonne on Wednesday.
While several mills were heard to be offering HRC at €1,300 per tonne exw, some offers were said to be as low as €1,280 per tonne exw. Even so, most buyers were looking to pay closer to €1,200 per tonne exw.
Fastmarkets calculated its corresponding daily steel HRC index, domestic, exw Italy, at €1,216.67 per tonne on Thursday, down by €19.33 per tonne from €1,236.00 per tonne on April 27.
The index was based on offers at €1,250 per tonne exw and bids and estimates at €1,200 per tonne exw.
Trading remained thin in both regions, with buyers adopting a wait-and-see approach. End-user demand was slow and inventory levels were high enough to give buyers flexibility regarding purchases.
“There have been no deals [recently] because we have no need to buy anything,” a Northern European distributor told Fastmarkets. “Stocks are so high, we don’t have to buy anything for the next two or three weeks at least.”
While some end-markets were expected to show better demand from the second half of May onward, the outlook for the key automotive industry was not bright, with some now predicting that it would not revive until the end of the year at the earliest. The sector was being constrained by a shortage of microchips and other components, the latter mainly due to the consequences of Russia’s invasion of Ukraine.
In addition to slowing underlying consumption, buyers were also aware that mills were under pressure to reduce prices, and this expectation was adding to the lack of prompt buying interest.
Conversely, uncertainty over the cost of energy and raw materials, particularly in the wake of Russia halting gas supplies to Poland and Bulgaria this week, may damp mills’ willingness to reduce prices, sources warned.
Nevertheless, mills were faced with an oversupply problem, and buy-side sources suggested that they were seeking options to clear this without lowering domestic prices.
One distributor reported rumors of mills having slowed production rates, while anther mooted the idea that mills could look to export material, albeit at prices substantially lower than domestic levels. High freight rates would put even more pressure on prices, however.
Competitively priced imports were providing buyers with yet another option, although long lead times made this an impractical alternative.
Material from Japan, South Korea and Taiwan was reported to be available at €1,000-1,050 per tonne cfr Italy, but with September delivery times. This compared with early in the third-quarter for domestic material.
Offers from India were heard at €1,000-1,030 per tonne cfr Northern Europe.
Published by: Ross Yeo
Volvo Q1 sales fall 20% on-year as supply chain constraints continue
Automaker Volvo sold 148,295 vehicles in the first quarter of 2022, down 20% year on year, and produced 169,000 units, down 9%, as supply chain constraints continued, although these had slowly started to ease, it said April 28.
However, it said that it had been hit by a shortage of a specific component, which was expected to impact second quarter production.
“Volvo Cars considers this a temporary set-back and expect the supply chains to improve in the second half of the year,” it said, adding that it expected marginal growth in sales volumes for the full year 2022, compared to 2021, although uncertainty remained high.
The majority of total sales went to Europe at 65,200 units, down 26% on the year, while China sales dropped 21% to 35,700 units and sales in the US fell 16% to 22,800 units.
Of the total vehicles sold in Q1, 11,700 were battery electric vehicles, which was a share of 8%, up from 6% in the fourth quarter of 2021, supported by strong demand and the prioritization of EVs during the ongoing supply restraints.
This also compared to only 3,600 BEVs sold in Q1 2021.
“That share will continue to grow as we increase our annual production capacity of fully electric cars to 150,000 units after summer,” Volvo said, adding that it forecast high growth for full-year 2022 sales of BEVs.
Increased demand for EVs has been one factor boosting battery raw material prices, with S&P Global Commodity Insights’ seaborne lithium carbonate and lithium hydroxide assessments up 120.4% and 152.4%, respectively, since the start of 2022 to $74,500/mt CIF North Asia and $80,000/mt CIF North Asia on April 27.
Volvo’s total recharge vehicle sales totaled 49,800 units in Q1 2022, up 6% year on year, and at a 34% share of total sales.
It said Norway, Brazil and Thailand became the first markets to reach 100% sales of recharge cars, including BEVs and plug-in EVs, in Q1, with Volvo aiming to direct its development and marketing efforts to recharge cars and its focus is on full EVs.
The company aims to sell 1.2 million vehicles/year by 2025, of which 50% should be BEVs.
Volvo also aims to reduce the CO2 life-cycle footprint of each car by 40% by 2025 and said this was progressing according to plan, with Q1 CO2 emissions 13.4% lower compared with 2018.
“The strategic direction remains clear and very much in focus; the fastest transformer in the industry, a fully electric brand with direct consumer relations, and lower carbon emissions is our way forward,” Volvo Cars CEO Jim Rowan said.
“To achieve our ambitions we will increase our pace of product development, strengthen the resilience of our supply chain, and accelerate our digital and software capabilities,” he added.
Global plug-in light duty EV sales are expected to total 13.7 million units in 2025 and 26.8 million units in 2030, up from 6.3 million units in 2021, according to S&P Global analysts.
— Jacqueline Holman


EU HRC negotiations move lower on bearish turn, competitive import offers
European HRC was stable April 28 — sources reported prices as on a downtrend in the slow market, driven by competitive import offers and withheld demand.
In northern Europe, the hot-rolled coil price remained stable on the day, assessed at Eur1290/mt ex-works Ruhr.
A service center source reported deals from week ended April 22 at Eur1300/mt – though saw current achievable prices as lower at Eur1250-1260/mt.
A mill source heard deals on the day at Eur1300-1320/mt, with most deals concentrated at the Eur1300/mt level.
The source reported an increase in the HRC-slab spread from Eur100/mt to Eur200-250/mt – considering Eur1050/mt as a feasible end-point for the current downtrend based on estimated slab prices at Eur800 CFR Northern Europe. Demand remained as reduced as buyers observe the bearish turn.
“In general there’s a clear downward trend – mills and buyers are both holding back from trading waiting to see who will give first,” said source. “It’s seeming the mills will have to concede and prices will continue dropping. The only issue is production costs – energy, logistics and raw materials are all driving costs much higher.”
A trader source agreed – “Northern mills are keeping their offer levels steady, telling customers the prices are strong, but gaps in their production will force prices down. Prices in the South are softening more quickly, but still aren’t comparable to imports.”
Sentiment in the Southern market was much the same, with one mill source describing muted demand.
“No one is willing to buy, instead waiting for domestic prices to drop while monitoring falling import offers.”
A service center source confirmed expectations of further downtrend.
“The Italian market approached the end of April with minimal volumes traded – market price was unclear. What is clear is the trend – downward across Europe. End users stopped purchasing but have continued to produce and so will need material soon in contrast to distributors who have sufficient stock. The mills will need to fill orderbooks and compete with falling import prices – the price has to come down.
HRC in Italy was also assessed stable at Eur1200/mt ex-works.
Import offers from India were heard on the day at Eur980/mt CFR, Eur1030-1040/mt CFR ex-South Korea and Japan, and Eur1100/mt CFR Italian ports ex-Turkey, anti-dumping duties included.
— Benjamin Steven, Maria Tanatar

Revista InfoAcero Abril 2022
En el siguiente enlace pueden acceder a la edición de Abril de nuestra revista: INFOACERO ABRIL 2022
A continuación destacamos algunos de sus contenidos:
- Opinión – D. Juan Ramón Fernández – Junta Directiva de la UAHE.
- Evolución del Índice de Precios de Productos Siderúrgicos – UAHE
- Información Asociativa: Conferencias organizadas por UAHE, Programa Steel Net Forum Iberia (Barcelona-23, 24 de Mayo)
- Sector Siderúrgico: Previsión a corto plazo –WorldSteel Association