

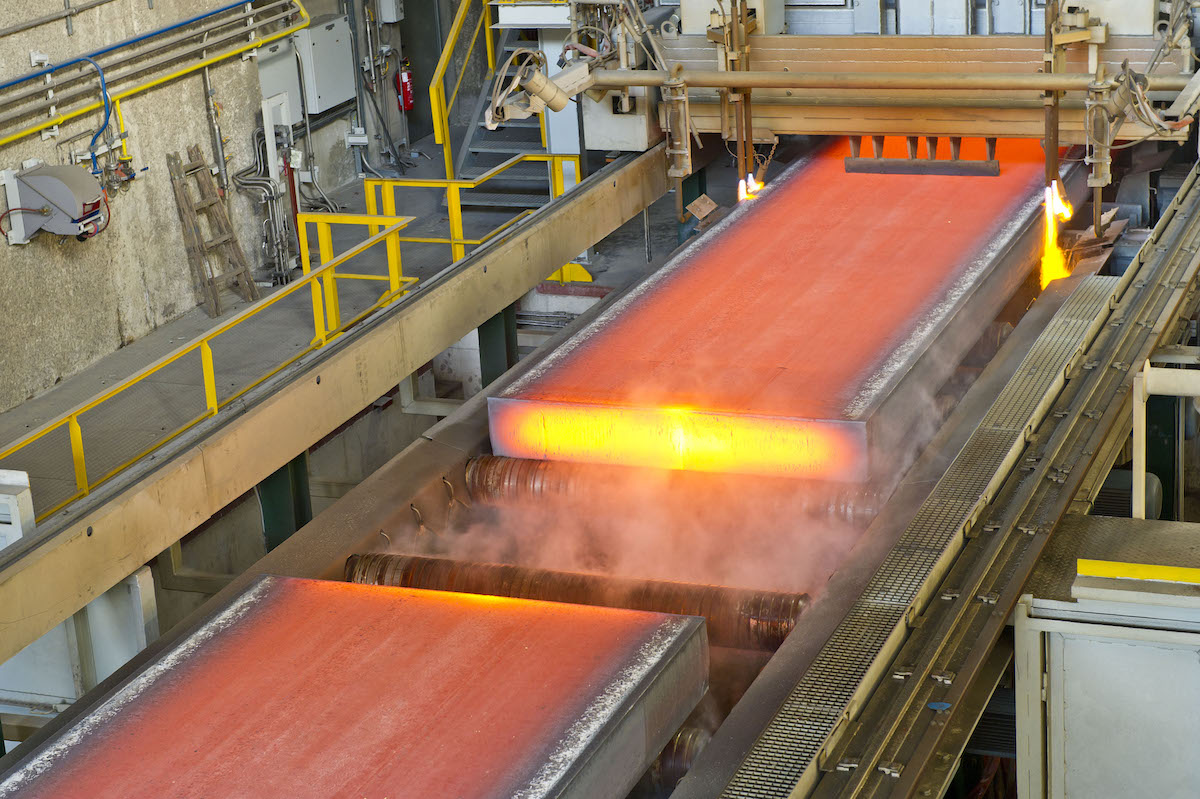
German steelmaker Salzgitter expects lower strip shipments for rest of 2024
German producer Salzgitter expects strip steel shipments to continue at a somewhat lower level for the rest of 2024, with section shipments at around the same level, and crude steel production running at a slightly reduced rate, according to its interim earnings Aug. 12.
In the first half of the year, Salzgitter produced 2.69 million metric tons of crude steel, slightly up on the same period of 2023, when it registered 2.51 MMt. In the same period, shipments were 2.81 MMt against 2.77 MMt in H1 2023, but shipments sales moved down to Eur2.47 million mt from Eur2.69 million mt.
Salzgitter said it expects the economy to remain weak in the heavy steel plate market, with order intake forecast “to drop below the already weak year-earlier level, with prices under intense pressure.”
The company said that pipe plate output is only likely to benefit around year-end, following delays in awarding projects for large-diameter pipes, while there will likely be a significant downturn in volumes in its medium-diameter pipe segment. In the precision tubes group, demand remains hesitant following on from the previous year, it said.
In the company’s steel processing business unit in H1, Salzgitter rolled 520,000 t of steel products against the 538,000 t recorded in the same period of 2023.
A generally improved result is expected for the trading business unit in 2024, thanks to more stable prices than in H1 2023.
Platts, part of S&P Global Commodity Insights, assessed the 62% Fe Iron Ore Index at $98.85/dry metric ton CFR North China on Aug. 12, down 45 cents/dmt from Aug. 8, in line with tradable values.
Salzgitter said it is also on track in its low carbon transformation program, which aims to fully convert the integrated steelworks of Salzgitter Flachstahl by 2033. At the moment, the company is in the process of building a 100 MW electrolysis plant, a direct reduction plant and an electric arc furnace.
Platts assessed Northwest European hot-rolled carbon-accounted coil at Eur725/t ex-works Ruhr Aug. 9, down Eur10 on the day.
The assessment was calculated in line with the sum of Platts daily carbon-accounted steel premium assessments and Platts daily hot-rolled coil price assessments in Northwest Europe.
Annalisa Villa


Tosyali reiterates commitment to expanding Spain’s Baika Steel Tubular System
Turkish conglomerate Tosyali Holding, which announced the acquisition of Spain’s Baika Steel Tubular System (STS) earlier this year, now rebranded as Tosyalı STS Spain, has reiterated its commitment to expanding the facility, Kallanish notes from the company’s social media statement.
Initially, when announcing the acquisition in January this year, the company stated its aim to increase the production capacity of Tosyali STS Spain from 150,000 tonnes/year to 240,000 t/y through new investments. This expansion was described as a key part of Tosyalı’s strategy to meet rising demand for spiral steel pipes, driven by the growing hydrogen distribution networks in Europe. The acquisition also increases Tosyali’s global pipe production capacity to over 3 million tonnes/year, reinforcing its status as Europe’s largest steel pipe producer, the company claims.
“Spain’s strategic location spans the European, African, and American markets,” said Şerif Tosyali, representing Tosyali’s foreign economic relations board at a meeting with employees, which was also attended by board members Yavuz Tosyalı and Kadir Tosyalı. “Here we will be able to contribute to Europe through our gradually increasing production of high-quality green steel. For us, new investments are the cornerstone of sustainable growth. In line with this approach, we will also make new investments in this plant in Spain. We continue to work towards increasing capacity here to 240,000 tonnes through new investments. With the strength of our plant in Spain, we will now pursue even better projects in the spiral pipe sector,” he added.
STS, located near Vitoria-Gasteiz in Spain, specialises in manufacturing spiral welded steel pipes with various coatings for oil, natural gas, hydrogen, and water transmission lines, as well as structural pipes for civil engineering projects.
Elina Virchenko UAE


Polish steel rebar, wire rod prices down on seasonal low demand
The summer holiday slowdown has also contributed to the poor consumption. And expectations of a possible price rebound in the autumn months were mixed, Fastmarkets heard.
Rebar
Polish mills continued to offer rebar at 2,750 zloty ($694) per tonne CPT in the week to August 9, industry sources told Fastmarkets.
But producers were willing to give discounts, and some volumes were sold at 2,650-2,700 zloty per tonne CPT, Fastmarkets heard.
Market participants estimated the tradeable market level at 2,650-2,700 zloty per tonne CPT.
According to some sources, rebar in Poland could be sold at 2,600 zloty per tonne CPT, but this was not confirmed by the market.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, cpt Poland, was 2,650-2,700 zloty per tonne on Friday, down by 30 zloty per tonne from 2,680-2,730 zloty per tonne the previous week.
“Demand is still weak. I do not see any chance for a price increase in the third quarter,” a distributor source told Fastmarkets. The same source suggested that prices could slide further in September when all mills were back in the market and could see that demand would not improve.
According to a producer source, however, the construction sector in Poland has been performing comparatively well. The source hoped that demand would improve after the summer and would eventually support a price rebound.
In terms of imports, offers of rebar from Germany to Poland were heard at €615-620 ($672-677) per tonne CPT.
Wire rod
Offers of Polish low-carbon drawing-quality wire rod were heard at 2,900 zloty per tonne in the week to August 9, trade sources told Fastmarkets.
Some volumes were traded at 2,850 zloty per tonne CPT, Fastmarkets heard.
Buyer sources estimated the tradeable market level at 2,700-2,800 zloty per tonne CPT, but producer sources did not agree with the lower end of that range, saying that it was too low for sales to be made.
Fastmarkets’ price assessment for steel wire rod (drawing quality), domestic, delivered Poland, was 2,800-2,850 zloty per tonne on Friday, narrowing downward by 50 zloty per tonne from 2,800-2,900 zloty per tonne the previous week.
According to a second distributor source, demand for low-carbon drawing-quality wire rod remained low in Poland due to summer holiday absences.
“I hope that demand will improve in September, but restocking, in my opinion, is just a dream,” the source said.
In terms of imports, offers of low-carbon drawing-quality wire rod from Italy were heard at €650-680 per tonne CPT.
Mesh-grade material from Ukraine was offered to Poland at €625 per tonne CPT.


Post-holiday price direction unclear for European HRC
Fastmarkets calculated its daily steel hot-rolled coil index domestic, exw Northern Europe at €618.88 ($676) per tonne on Friday, down by €0.14 per tonne from €619.02 on Thursday.
The index was down by €1.62 per tonne week on week and by €14.25 per tonne month on month.
Trading in the region was extremely quiet due to the holiday season, with even steady offers rare, sources said.
Buyer sources estimated the workable prices at €600-620 per tonne ex-works.
But buyers and sellers have been holding back in the week to Friday, monitoring the situation.
Producer sources said that post-summer price increases were likely to be necessary because they have been operating “below the cost line.”
But slow demand for steel remains a “big red flag” for the market, one producer source told Fastmarkets.
“We have low demand [for steel] caused by low production of cars and a weak construction [sector]. And Germany is fearing another recession just because of these problems,” the producer source added.
In addition, more and more market participants are questioning the future of the electric vehicle (EV) sector.
“Demand for e-cars has crashed,” a buyer source in the region said.
In Southern Europe, meanwhile, Fastmarkets calculated its daily steel hot-rolled coil index domestic, exw Italy unchanged at €618.13 per tonne on Friday.
The index was down by €2.50 per tonne week on week and by €10.20 per tonne month on month.
The Italian market was also in “holiday mode,” with activity expected to resume at the end of August or in early September, sources said.
Buyers estimated workable prices at €600-620 per tonne ex-works and even below €600 per tonne ex-works for bigger tonnages.
But some sources said that local suppliers were likely to attempt a price rise after the summer break in expectations of the traditional rebound of trading.
Others said the anti-dumping (AD) investigation launched by the European Commission against HRC from Egypt, Vietnam, Japan and India was also likely to support a rebound in prices.
Doubts remained, however, over whether the AD probe would have any immediate effect on the market.
“First, the demand [for steel] must come back; second, the domestic mills must increase the price [of HRC],” a buyer in Europe said.
The market for imported coil was also largely quiet, with no new offers from Asia heard on Friday.
Turkish HRC for September-October shipment was on offer at €570-590 per tonne CFR, including the AD duty.
And HRC from Ukraine was on offer to Italy at €565-575 per tonne CFR.
Two sources said a small deal for India-origin HRC to Italy was done at $625 per tonne CFR in the week to Friday.

UK proposes HR flat steel import quota expansion
The UK’s Trade Remedies Authority (TRA) has proposed an increase in the import quota for HR flat steel due to a reduction in domestic production, the authority announced on Friday, 9 August, Kallanish notes.
This proposal was triggered particularly by the recent closure of a blast furnace at Tata Steel UK’s Port Talbot site as part of a transition to an electric arc furnace, according to the notice.
The TRA proposal includes increasing the quota on imports under category 1 steel — non-alloy and other alloy hot rolled sheets and strips — to a total of 2.9 million tonnes.
Changes in circumstance, including the closure of the blast furnace, have impacted the UK’s domestic flat steel production, leading to an increase in imports that have consistently exhausted part of the quota for hot rolled flat steel products across four consecutive quarters, according to notice. This, in turn, has driven up the cost of these products for the UK market.
As a result of the reduction in domestic production of category 1 steel, the TRA has proposed varying the measure by duplicating Category 1 to form Categories 1A and 1B. The quota for Category 1A, which would be for those importing for commercial applications, will be retained at current levels. Meanwhile, the quota for Category 1B, accessible solely for downstream processing, will be set 89% higher than that of 1A. Together, categories 1A and 1B will bring the total category 1 quota to approximately 2.9 million tonnes per year. The TRA has also proposed that the Category 1B quota be allocated on a global basis to allow companies to establish reliable supply chains for domestic processing, with a cap in the range of 37-42% to ensure no single country’s exports dominate this new quota.
“Our proposal today is designed to address the reduction in production of hot rolled flat steel at Port Talbot. These changes have resulted in higher imports and parts of the current quota being exhausted, creating uncertainty and driving up costs for steel users. We propose maintaining the current quota volumes for steel used for commercial applications and creating a new quota accessible for downstream processing,” TRA chief executive Oliver Griffiths said.
The import allowance under category 1A equates to just over 1 million tonnes annually, and under category 1B, to around 1.9 million tonnes annually. If these limits are breached, importers would need to pay the 25% tariff, the TRA explained.
The goods subject to review are currently classifiable within the following commodity codes: 72081000, 72082500, 72082600, 72082700, 72083600, 72083700, 72083800, 72083900, 72084000, 72085210, 72085299, 72085310, 72085390, 72085400, 72111300, 72111400, 72111900, 72126000, 72251910, 72253010, 72253030, 72253090, 72254015, 72254090, 72261910, 72269120, 72269191, and 72269199.
Elina Virchenko UAE

UK TRA proposes increasing HRC import quota citing Tata Steel UK production drop
The UK Trade Remedies Authority has proposed an increase to the import quota for hot-rolled flat products as changes in circumstance, including the recent closure of a blast furnace at Tata Steel UK’s Port Talbot works, have decreased domestic production of these products, it said Aug. 9.
Under the proposal, the current quota volumes for steel used for commercial applications will be maintained, while the TRA would create a new quota accessible for downstream processing, it said.
The TRA has proposed that the category for hot-rolled flat products, known as Category 1, be split into two segments, Categories 1A and 1B. The quota for Category 1A, which would be accessible by parties looking to import the products for commercial applications will be retained at current levels, or just over 1 million metric tons/year.
The quota for Category 1B, which would be accessible solely for downstream processing, however, will be set 89% higher than that of Category 1A, to around 1.9 million mt annually. This means the total Category 1 category for hot-rolled flat products will be increased to 2.9 million mt.
The TRA also has proposed for the Category 1B quota to be allocated on a global basis “to allow companies to establish reliable supply chains for domestic processing,” along with a cap in the range of 37%-42% to ensure the quota is not dominated by a single country.
“Our proposal today is designed to deal with the reduction in production of hot-rolled flat steel at Port Talbot,” the TRA said. “These changes have resulted in higher imports and parts of the current quota being exhausted, creating uncertainty and driving up costs for steel users.”
Tata Steel is the UK’s sole HRC producer.
Platts, part of S&P Global Commodity Insights, last assessed UK HRC at GBP575/mt basis DDP West Midlands Aug. 8.
Justine Coyne

Swiss Steel discusses industry transformation and future plans
In a recent interview with marketSTEEL, Frank Koch, CEO of Swiss Steel Holding AG, highlighted the company’s pivotal role in transforming the steel industry.
Koch emphasized that the Swiss Steel Group is leading the charge in sustainability by focusing on reducing its carbon footprint through innovative technologies. Notably, the company offers green steel with a CO2 footprint 83% lower than the global industry average, showcasing its commitment to environmental responsibility.
Koch also addressed the ongoing restructuring efforts within the Group, particularly in Germany, where high energy costs pose significant challenges. To mitigate these, the company is implementing more efficient energy systems and exploring alternative energy sources to optimize production and reduce costs.
Looking ahead, Koch outlined the Group’s future as one driven by innovation, sustainability, and customer-centricity. Key initiatives include advancing scrap recycling processes, particularly in their Uginè, France site, and intensifying research and development to create environmentally friendly products that meet customer needs. Koch expressed confidence that these strategies will ensure the company’s continued success and deliver sustainable value to all stakeholders.
The interview underscores Swiss Steel Group’s commitment to leading the industry’s transformation towards a more sustainable and customer-focused future.
Read more: marketsteel.com
