


World crude steel output down 5.8 percent in June 2025
Global crude steel production in June this year decreased by 5.8 percent year on year to 151.4 million mt, according to the World Steel Association (worldsteel).
In the first half of this year, global crude steel production went down by 2.2 percent year on year to 934.3 million mt.
In June, crude steel output in Asia amounted to 112.9 million mt, down 6.2 percent, with China’s output at 83.2 million mt, down 9.2 percent, with 6.7 million mt produced by Japan, decreasing by 4.4 percent, 13.6 million mt produced by India, up by 13.3 percent, and 5 million mt produced by South Korea, moving down by 1.8 percent – with all comparisons on year-on-year basis.
EU-27 countries produced 10.4 million mt of crude steel in June, down by 8.2 percent year on year. In the given period, Germany’s output amounted to 2.7 million mt, down 15.9 percent year on year.
Turkey produced 2.9 million mt of crude steel in June with a 3.5 percent decrease compared to the same month in the previous year. The CIS registered a crude steel output of 6.7 million mt, decreasing by 8.8 percent on year-on-year basis, with Russia’s estimated output at 5.6 million mt, down 7.4 percent year on year.
In North America, in June, crude steel output totaled 8.7 million mt, up by 1.2 percent year on year, with the US producing 6.9 million mt, increasing by 4.6 percent, both year on year. Crude steel output in South America in June amounted to 3.5 million mt, up by 1.3 percent compared to the same month in the previous year, with Brazil’s output totaling 2.8 million mt, falling by 0.5 percent year on year.
In the given month, Africa produced 1.7 million mt of crude steel, increasing by three percent year on year. In the Middle East, crude steel output totaled 4.3 million mt, moving down by 4.9 percent.
Shares in global crude steel production in June 2025



Vallourec inks agreement to sell Déville-lès-Rouen site
French pipe manufacturer Vallourec has announced that it has signed an exclusive agreement with France-based VINCI Immobilier to sell its Déville-lès-Rouen site, its former tube mill.
Following an intensely competitive selection process, VINCI Immobilier emerged as the preferred buyer in March 2025, entering into exclusive negotiations with a project proposal that aligned with local development goals and stakeholder expectations.
The final transfer of the site is expected in 2026 after the necessary regulatory steps.

EU issues minor Chinese tinplate anti-dumping duties correction
The European Commission has issued a corrigendum concerning definitive anti-dumping duties on imports of flat-rolled products of iron or non-alloy steel plated or coated with tin originating in China, notes Kallanish.
The correction addresses minor numerical inaccuracies in the duty rates originally adopted in May 2025. While the adjustments are purely technical, the update ensures legal precision without altering the substance or scope of the anti-dumping measures imposed, EC notes.
The definitive anti-dumping duty and dumping margin for Shougang Jingtang United Iron & Steel Co., Ltd. have been revised from 46.8% to 46.7%. Similarly, the figures for other cooperating Chinese companies listed in the annex have been corrected from 24.6% to 24.5%.
| Chinese exporter | EU definitive AD duty % |
| Baosteel Group: — Baoshan Iron & Steel Co. — WISCO-Nippon Steel Tinplate Co. |
13.1 |
| Shougang Jingtang United Iron & Steel Co. | 46.7 |
| Other cooperating companies | 24.5 |
| All other imports originating in China | 62.3 |
Elina Virchenko Ukraine


EU’s Russia-origin semis imports fall, pig iron surges
The EU has decreased imports of most steel products from Russia, but pig iron and scrap intake increased in January-May, according to Eurostat data.
Overall HS chapter 72 product volumes amounted to 2.57 million tonnes, up by 1.1% year-on-year, Kallanish notes. Revenue generated by these shipments however decreased 14.7% to €1.06 billion ($1.24 billion).
The main share of imports was taken by semi-finished products, accounting for 86% of supply. Semis intake nevertheless decreased 3.3% on-year to 1.49mt and revenue fell 14.6% to €681.9m.
Belgium took 554,630t of semis, down by 9.4% on-year. Italy imported 358,940t, higher by 5.6%, and Czech Republic 294,080t, up by 49%. Denmark took 251,040t, up 2.8% on-year.
Imports of pig iron from Russia to the EU in January-May amounted to 696,990t, up 68.5% y-o-y. Revenue increased by 52% to €254.45m. Italy imported 524,620t, an increase of 3.9%. Latvia took 82,270t, up 17% on-year, and Belgium accepted 31,070t compared with zero in January-May 2024.
There were not many deliveries of Russian-made ferroalloys to the EU market in January-May 2025, just 3,800t versus 39,470t a year earlier.
Supply of direct reduced iron from Russia to the EU amounted to 353,190t, down 33% on-year, at a value of €110.4m, down 38.9%.
EU scrap intake from Russia amounted to 30,550t, up 51%.
Iron ore supply was only 2,040t versus 9,360t in January-May 2024.
European steelmakers association Eurofer has previously voiced concern over the European Commission’s decision to continue to allow Russian slab to enter the EU until 2028 (see Kallanish passim).
As part of the EU’s 12th Russia sanctions package, EU importers will be able to import some 3m t/year of slab from Russia until October 2026. The quota will be reduced to 2.6mt and then 2mt during the following 12-month periods through October 2028.
Russian-origin billet imports into the EU have been prohibited since April 2024. EU pig iron imports from Russia will be banned from 2026 and are subject to quotas in 2024 and 2025. Russia already exhausted its 2025 quota in February.
Ukraine’s Metinvest urged the EU to close all loopholes for imports of Russian semi-finished products as soon as possible (see Kallanish passim). Russian steelmakers have maintained competitive positions in the EU market despite sanctions, especially in the area of slab supply, the firm said.
Svetoslav Abrossimov Bulgaria

Italian rebar prices, demand recover
Italian rebar prices are on the rise, with both producers’ asking prices and contracted levels increasing.
Steelmakers are now pushing for further hikes this week, following a sharp drop in both prices and volumes since May. Domestic producers are currently proposing an additional €30/tonne ($34) increase compared to mid-July quotations.
Compared to the initial round of increases in mid-July, when steelmakers were asking for around €270/t base ex-works, current offers have risen to €290/t base ex-works. This upward movement is driven by reduced availability of specific grades and rebar in coil, along with elevated production costs that continue to pressure mill margins.
Sellers are reporting some restocking activity as buyers replenish inventories ahead of the planned production stoppages in August. Most mills will be idled between 8-24 August, Kallanish notes.
Current base transaction levels for rebar now range from €250-270/t ex-works, reflecting an average increase of €30/t compared to the first half of July. Effective rebar prices, including size extras averaging €260-270/t, are reported at €510-540/t ex-works.
Domestic mesh prices are also trending up, averaging at €350-370/t ex-works, excluding transport and size extras which add approximately €300/t.
Natalia Capra France

European HRC producers target higher prices; buyers hold back
European hot-rolled coil prices were broadly stable amid subdued trading on Wednesday July 23. Mills expected regulatory pressure and increased protectionism to support price rebounds later in the year, and ArcelorMittal increased offers by €30 ($35) per tonne, Fastmarkets heard.
Trading was seasonally quiet in the European HRC market, sources said.
However, most major suppliers have already closed order books for September-delivery coil, with some mills already trying to implement minor price hikes for October-delivery material.
“European mills are relying a lot on the potential impact of CBAM (Carbon Border Adjustment Mechanism) on the market and also the implementation and new trade measures to replace safeguards,” a buyer source said. “These measures are supposed to limit imports, especially in the first quarter of 2026, so European mills will be able to grab bigger market share.”
Leading European steelmaker ArcelorMittal increased HRC offers for October delivery by around €30 per tonne, to €590 per tonne delivered in Northern Europe, several sourced told Fastmarkets.
It remains to be seen if new offers will be sealed in deals.
“I heard that [a leading European steel producer] intends to increase [HRC prices], but I guess the market will not accept,” a second buyer said.
Offers from integrated suppliers in Europe were reported at €560-590 per tonne ex-works.
Italy-origin coil was offered to Germany at €580-600 per tonne delivered, but buying interest for such prices was minimal so far. An Italian supplier could still offer September lead times, sources said.
Buyers’ ideas of tradable prices were still hovering around €540-550 per tonne ex-works.
“It remains to be seen if higher offers will be traded. Mills put too much hope in protectionism, while real consumption is not supportive of any increase at all,” a third buyer said.
But most mill sources that spoke to Fastmarkets indicated a minimum €560 per tonne ex-works for new sales.
Some suppliers claimed that new offers should be in the €600s per tonne amid high production costs.
As a result, Fastmarkets’ calculation of the daily steel hot-rolled coil index, domestic, exw Northern Europe was €555.00 per tonne on July 23, stable day on day.
The Northern European index was up by €7.94 per tonne week on week but was down by €25.23 per tonne month on month.
Meanwhile, in Italy, Fastmarkets’ daily steel hot-rolled coil index, domestic, exw Italy was calculated at €526.88 per tonne on Wednesday, down by just €3.75 per tonne from €530.63 per tonne on Tuesday.
The index was however up by €2.50 per tonne week on week, but down by €29.12 per tonne month on month.
Local integrated suppliers were aiming for €540-550 per tonne ex-works for coil to be delivered in September-October, but this price was not yet accepted in deals.
Buyers’ estimates of achievable prices remained at €520-530 per tonne ex-works.
“We still have about two weeks before summer closures — we’ll see if mills manage to sell anything at higher prices,” a source in Italy said.
Import offers were broadly stable in the week to Wednesday, but there were some signs of higher offers amid cautious optimism in China.
Fastmarkets’ weekly assessment for steel hot-rolled coil import, cfr main port Southern Europe was €450-500 per tonne on Wednesday, stable week on week.


US, Japan reach trade deal; steel tariffs remain
The US and Japan reached a trade deal, with Japan to invest $550 billion into the US economy, US President Donald Trump said late on Tuesday July 22.
“We just completed a massive Deal with Japan, perhaps the largest Deal ever made [sic],” Trump announced via a social media post.
The US will receive “90% of the Profits [sic],” he said. “Japan will open their Country to Trade including Cars and Trucks, Rice and certain other Agricultural Products, and other things.”
A tariff rate of 15% on Japan will be applied instead of the previous rate of 25%, Trump’s post said.
Japanese Prime Minister Shigeru Ishiba supported the deal, saying “Japan’s tariff rate, which had been set to increase to 25% on reciprocal tariffs, was kept at 15%. This is the lowest figure to date among countries with trade surpluses with the US.”
“Japan is, for the first time ever, OPENING ITS [market] TO THE USA, even to cars, SUV’s, Trucks, -and everything else, even agriculture and RICE, which was always a complete NO, NO [sic],” Trump said in a Truth Social post Wednesday July 23. “The Open Market Japan may be as big a profit factor as the Tariffs themselves, but was only gotten because of the Tariff Power.”
Japanese chief negotiator Ryosei Akazawa told reporters on July 22 there would be no change to the Section 232 steel and aluminium tariffs yet.
Currently, the US imposes a 50% tariff rate on all imports of steel from Japan.
The ramifications on the steel industry are “too early to know,” Keybanc director of metals equity research Phil Gibbs told Fastmarkets.
“It sounds like a good deal for the US,” a steel buyer said, “but the devil is in the details.”
US buyers “would love to have slabs from [Japanese producer] JFE at 15% versus possible 50% from Brazil,” the buyer added.
The US automotive industry reacted negatively to the news. American Automotive Policy Council leader Matt Blunt told an independent news source, “any deal that charges a lower tariff for Japanese imports with virtually no US content than the tariff imposed on North American-built vehicles with high US content is a bad deal for US industry and US auto workers.”
Japan’s trade deficit with the US totaled $68.5 billion in 2024, according to data from the Office of the US Trade Representative.
In the first six months of 2025, the US imported 491,454.57 tonnes of steel from Japan, making Japan the sixth-largest exporter to the US, according to data from the US International Trade Agency. The US imported 218,068.72 tonnes from Japan in the three months after the revival of the Section 232 tariffs, down by 17.3% from the same period in 2024.
Deal comes after conclusion of US Steel-Nippon Steel Saga
The agreement between the two countries comes amid the finalization of of Japanese-owned Nippon Steel’s fraught acquisition of US Steel.
The deal concluded on June 18, after a long-winded saga that began during the Biden Administration.
Trump approved the merger with various caveats, like US Steel must maintain its name and headquarters in Pittsburgh, Pennsylvania. The companies also had to sign a national security agreement and issue a “golden share” to the US government.
The merger will give the company a total global capacity of 86 million short tons, nearing Nippon’s goal of 100 million tons.
Robert England in Milton, Delaware, contributed to this story.
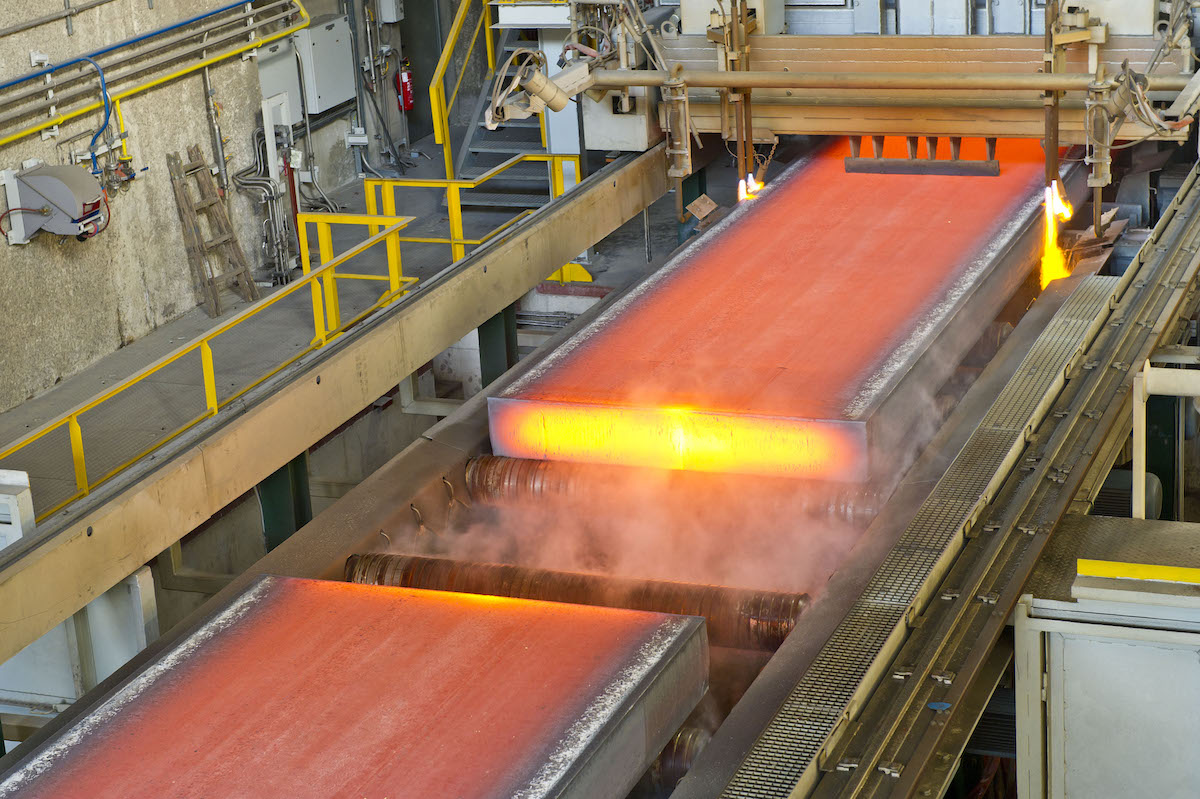
China sells 20,000 t of greensteel slab to Italy
Chinese steelmaker HBIS has traded up to 20,000 t of hydrogen-based green steel slab to Italy, with the material to be shipped before September, market participants told McCloskey on 22 July.
HBIS released a statement on 18 July describing the sale of a non-specific 10,000 t of “hydrogen metallurgical green steel” to an Italian end-user, cited as bearing a 50% reduction in embedded carbon content.
Through investigation with market sources, McCloskey now understands the exporter agreed additional volumes – for a total of around 20,000 t of steel slab – all sold to Italy. Approximately half of this material, or 10,000 t, has been confirmed as purchased by an Italian re-roller. The remaining order allocation has not been confirmed, though some in the market attributed the rest of the load to the same re-roller in a further 10,000 t deal.
Sources close to the deal describe the CO2 content of the material as around 0.5 per tonne of steel – competitive against even European electric-arc furnace (EAF) producers – with slab of comparable CO2 content said to be almost impossible to source within Europe at present due to a lack of relevant offerings from EAF-based mills, and in increasing demand due to the upcoming definitive stage of the Carbon Border Adjustment Mechanism (CBAM).
“It seems everybody is searching for slab [from alternative sources] now due to CBAM,” a distributor source said.
Even if calculated on default EAF values for the CBAM, which enters its duty-liability phase from January 2026, sources consider HBIS’ hydrogen-produced slab as preferable to other exporters that predominantly operate via the blast furnace route, able to attract lower CBAM duties due to its reduced emissions balance.
Despite the material’s marketability, McCloskey understands that the deal did not incorporate a significant green steel premium, traded at only around a 2-3% premium to current slab prices, in the vicinity of $500/t CFR Italy. In contrast, green hot-rolled coil (HRC) sales to end-users in the European domestic market can reach premiums of up to EUR200/t. McCloskey’s reduced carbon marker, which calculates the value of one unit of reduced carbon in reference to all surveyed green HRC premiums in the week to its publication, currently stands at just under 11% of the spot HRC price in Northwest Europe.
HBIS did not give detail of the production route of the cited 10,000 t order in its public statement, but McCloskey’s Asia-specific Green Steel Profile describes HBIS’ Zhangzuan Technology (ZXHT) site as utilising a hydrogen-rich coke oven gas direct-reduced-iron (DRI) plant to feed the steelmaker’s EAF production of low-carbon steel.
Both market sources and HBIS’ press release confirm that the steelmaker is targeting the European market with its low-carbon offerings, taking advantage of emerging arbitrage opportunities resulting from the upcoming full implementation of CBAM, potentially compounded if relevant carbon costs have already been paid domestically under China’s own Emissions Trading System.
Benjamin Steven Journalist, Steel
Maria Tanatar Associate Director, Steel and Green Steel


Luxembourg government moves to acquire insolvent ex-Liberty Dudelange plant
“In the context of the bankruptcy of Liberty Steel Dudelange, the Government Council has decided to submit an offer to the trustee to acquire the site,” the Ministry of Economy said in a press release.
“After almost three years of inactivity, the site can be redeveloped in a way that maximizes the use of available space and finally gives it a new purpose to contribute to economic development,” the ministry added.
In 2019, Liberty Steel acquired the Dudelange site, along with several other European steel assets, from ArcelorMittal. Almost all of those acquisitions have faced insolvency or closure in recent years.
The plant in Dudelange is capable of producing around 1 million tonnes per year of galvanized products from both electro-galvanizing and hot-dipped galvanizing lines, according to Fastmarkets’ information. There are two hot-dipped galvanizing lines with combined capacity for 620,000 tpy and two electro galvanizing lines with combined capacity for 360,000 tpy, according to Liberty Steel’s website.
There are 185 workers employed at the Dudelange plant, which lies in the south of Luxembourg, which itself is between France, Belgium and Germany.
The asset was part of Liberty Steel Belgium, along with Liberty Liège, which comprises the Flémalle and Tilleur production sites in Belgium, each producing cold-rolled coil, hot-dipped galvanized coil and tinplate.
In December 2024, the Dudelange plant was declared insolvent and a receiver was appointed, while the Belgian assets entered a process of liquidation.
Liberty Steel’s attempts to organize a reacquisition faltered. Then, in February this year, Turkey’s Tosyali Steel submitted an offer for the potential acquisition of the Dudelange plant, but Fastmarkets understands that the deal did not progress beyond that initial stage.
“If this offer is accepted, the Ministry of Economy will develop the land with a view to developing new industrial activities and promoting the creation of high-value jobs. The government will also examine the possibility of dedicating part of the site to defense-related projects,” the Ministry of Economy said.
Because no other potential buyer has emerged, industry sources familiar with the matter said that the chances were high that the Dudelange site would be nationalized.
Galvanized coil is mainly used in the automotive and construction industries. But these products are also used in the military industry, mainly for their corrosion resistance and durability in extreme conditions. Applications include structural elements, vehicle components and essential parts such as chains and anchors for landing craft.
