


French heatwave slows activity
The persistent heatwave in France is impacting transport and activity across the steel sector, including at mills and distributors, sources tell Kallanish.
Deliveries, particularly in the afternoon, are slowing as workers struggle to operate in sweltering yards and are reducing their hours to avoid the heat.
A purchasing group also warns of slowing deliveries and receptions, with many workers taking days off this week ahead of an expected easing of the heat on Sunday.
At northern ports, vessel discharging activity is also slowing. “France is not organised for extreme heat. Only a few cranes have air conditioning at the ports of Rouen and Gent, and the ones without are impossible to use,” one source in the scrap segment tells Kallanish.
Another source warns of possible delivery disruptions because of the low levels of rivers between France and Germany.
Two mill sources report that equipment is overheating, with breakdowns requiring repairs taking two to three hours and disrupting production.
Air conditioning is not widespread in central and northern France, where the majority of mills, distributors and shredders are located. A scrap seller warns that the risk of fire is significantly heightened in the current conditions. while office spaces benefit from air conditioning, shredder operating areas are described as unbearably hot, with workers taking holiday.
Two French distributors say that activity in June had recovered slightly from the lull seen the previous month but has since slowed sharply due to the weather. School closures in some regions on Thursday and Friday, and early afternoon shutdowns, are adding a further layer of disruption to the working week.
Author: Natalia Capra


UK adjusts EU import quotas after agreement reached
An agreement has been struck between the UK and the European Union regarding the tariff rate quotas (TRQs) on imported steel, days ahead of their implementation, Kallanish observes.
The deal was announced as the Department for Business and Trade published its final figures for the TRQs. This will see an overall quota reduction of 51%, down from the initial 60% proposed, while the out-of-tariff rate will increase to 50%. As part of the changes, 11 commodity codes have been removed while two have been added following industry feedback.
Addressing the House of Commons, Chris Bryant, Minister of State for DBT, said: “Some of the changes reflect the fact that the European Union remains our largest export market for steel, and we have highly interconnected supply chains … We have reached a mutual outcome with the EU as a result of these discussions.”
The UK will thus increase the EU’s quota access from the announced 1.58 million tonnes to 2.08mt. The bloc will announce its own quota numbers next Monday, he added.
“This will provide stability for UK-EU steel trade from 1 July, while we continue to work together to strengthen UK-EU steel trade longer term,” Bryant noted.
“This measure needs to work not just for our steel producers, but also, of course, for our manufacturers, who depend on steel, those who source it from the UK and those who source it from abroad. Our aim is solely to protect categories of steel that we produce in the UK, so we have deliberately excluded many categories from the measure,” he added.
Nearly three quarters of UK steel imports by value and 53% by volume are out of scope of this measure, according to Bryant. “The total quota volume will now be 3.2mt. That is an increase of over 560,000t of steel that can be imported, tariff free, compared to the provisional volumes we announced. A significant 21% uplift,” he said.
“We know that businesses will sometimes need to find specialised steel that we simply can’t procure here in the UK. In these cases, quotas have been designed to allow for imports and to ensure continued availability for UK businesses without additional unnecessary costs; to ensure continuity within supply chains for business, we are also introducing a transitional arrangement.”
Concerns have been raised that some products included in the quotas are those which “could” be made domestically but which are currently not being produced.
In Category 1, the provisional yearly EU quota stood at 68,226t and has now increased to 375,000t. Category 5 now stands at 49,836t for the EU, from 29,836t provisionally, while Category 6 has gone from 4,740t to 39,795t.
The EU quota for Category 12B has been revised to 47,618t from 4,454t, while Category 14 is now at 16,543t from 11,532t. Category 17 has increased to 253,678t from 106,106t, while Category 26 has risen to 30,026t from 19,666t.
Other categories saw no changes or only minor revisions. Category 4 has seen its EU quota reduced from 634,773t provisionally to 510,273t, as has Category 28 from 47,859t to 43,157t.
Author: Carrie Bone

Commission to unveil first strategic European defence projects as soon as next week
The EU executive is expected to unveil around five joint European projects, one Commission official and two diplomats told Contexte.
Two of the projects will focus on drones and air defence; another will seek to strengthen the bloc’s eastern regions, which have recently faced a spate of drone incidents.
The initiative forms part of the Commission’s push for member states to develop, produce and procure critical defence equipment on a large scale through so-called projects of common interest as the bloc seeks to rearm.
France, Italy and Greece had previously opposed using EU funds to set up a common project to help eastern countries counter drones over concerns about technical feasibility and frustration that it was unfair for other regions.
The European Defence Industry Programme has earmarked €325 million of EU funds for such projects, which can also involve Ukrainian and Norwegian companies.
Commission President Ursula von der Leyen also said on 25 June that Ukraine is set to receive €6 billion in the coming days to procure drones under the €90bn EU loan.


Stegra completes €1.4 billion financing for Boden green steel plant
Sweden-based green steel producer Stegra has completed a €1.4 billion financing round led by a consortium headed by Wallenberg Investments, with participation from existing and new investors as well as continued support from the company’s lenders. The financing, which was announced in principle in April 2026 subject to regulatory approvals, has now officially closed.
Financing preserves access to existing debt facilities
The Wallenberg Investments-led consortium includes existing investors IMAS and Temasek together with new investors Bolero and SEB-Stiftelsen. Several existing shareholders also participated in the financing round, including Altor, which will become Stegra’s second-largest shareholder. Other participating investors include Hy24, Just Climate, AMF, AP2, Climate Infrastructure Fund, Kallskär, Kobe Steel, Lingotto Innovation, Scania, Schaeffler, Security Trading, Stena Metall Finans and Swedbank Robur. In addition, a group of the company’s second-lien lenders led by AIP Management has invested directly in equity.
The financing package received unanimous approval from Stegra’s lender group. According to the company, all participating banks continue to support the project, allowing Stegra to retain access to the undrawn debt facilities established under its 2024 financing package. Håkan Buskhe, head of special investments at Wallenberg Investments and incoming Stegra board member, said the consortium will work closely with the company to complete and commission the Boden steel plant, describing the project as an important contribution to Sweden’s competitiveness and the European Union’s security of supply.
Construction continues at Boden project
According to Stegra CEO Henrik Henriksson, the financing round strengthens the company’s financial position by increasing its equity ratio. He also welcomed the increased Swedish ownership through the Wallenberg Investments-led consortium and highlighted the continued support of the Swedish National Debt Office and the Swedish Export Credit Corporation (SEK), which remain committed to previously agreed financing facilities.
Stegra stated that construction activities at its Boden steel plant are continuing to ramp up, while the overall project timeline remains under review.


EUROFER: EU steel demand to post modest growth in 2026, with capacity utilization still subdued
According to the Economic and Steel Market Outlook 2026-2027/Q2 2026 Report from the Economic Committee of the European Steel Association (EUROFER), apparent steel consumption in the EU recovered more strongly than expected in 2025, increasing by 4.4 percent year on year to 134 million mt, supported by exceptionally strong growth in the second half of the year and a sharp increase in imports.
According to EUROFER, apparent steel consumption rose by 13.5 percent year on year in the fourth quarter of 2025, following a 4.7 percent increase in the third quarter. The increase partly reflected the comparison with very weak volumes recorded in the same period of the previous year, as well as purchases brought forward in anticipation of stronger demand expected in 2026. However, apparent steel consumption remained around 10 million mt below pre-pandemic levels.
Capacity utilization remains low despite recovery in consumption
EUROFER also noted that steel capacity utilization in the EU remained subdued, standing at 65.4 percent in the first quarter of 2026, broadly unchanged from 65 percent in 2025. According to the association, this highlighted the continued weakness of underlying market conditions, despite the recovery in steel consumption.
Looking ahead, EUROFER expects apparent steel consumption in the EU to continue growing, though at a slower pace, by 0.4 percent in 2026 to 135 million mt, before increasing by 2.2 percent in 2027 to 138 million mt. Real steel consumption, meanwhile, rose by 0.9 percent in 2025 after three consecutive annual declines and is forecast to increase by 1.4 percent in both 2026 and 2027, supported by stock replenishment.
In 2027, demand from steel-using sectors is expected to gain further momentum, with the Steel Weighted Industrial Production index forecast to rise by 2.4 percent, driven by increases in construction output, mechanical engineering and automotive output.
GDP growth holds up despite geopolitical uncertainty
Meanwhile, EUROFER stated that economic growth has held up despite geopolitical uncertainty. According to the report, EU GDP increased by one percent year on year in the first quarter of 2026, compared to a 1.4 percent rise in the fourth quarter of 2025. In the same period, real GDP rose by 0.3 percent in Germany, by 1.1 percent in France, by 0.7 percent in Italy and by 2.7 percent in Spain, which continued to outperform other major EU economies.
EUROFER forecasts EU GDP to grow by one percent in 2026 and by 1.4 percent in 2027, following a 1.3 percent increase in 2025. Meanwhile, the European Commission’s spring forecast expects EU GDP to grow by 1.1 percent in 2026 and by 1.4 percent in 2027, while the IMF forecasts euro area GDP growth at 1.1 percent in 2026 and 1.2 percent in 2027.

Bulgarian longs prices stable, but mood weakens ahead of summer slowdown
The Bulgarian longs market has remained almost motionless this week, not because prices are being firmly defended, but because there is very little demand to test them. Buying activity is still weak, with full stocks, limited cash availability and slower construction-related demand leaving buyers with little reason to return to the market in a meaningful way.
Payment delays and liquidity problems continue to weigh on purchasing decisions, while the expected clarification of quota-related issues and the new import regulation in the EU have added another reason for market players to wait. Still, sources stress that the main pressure is coming from the lack of real consumption rather than from regulatory uncertainty.
“Demand is depressed and the market is moving very slowly. Buyers are already covered, liquidity is still a problem and the holiday season is starting to weigh on activity. Regardless of the new import regulation, demand will probably decline further, and prices may also come under pressure,” a trader told SteelOrbis.
Against this background, no change has been observed in domestic longs quotations in Bulgaria this week. Rebar prices have continued to be heard at around €625-635/mt CPT Bulgaria, while wire rod prices have remained at approximately €670-690/mt CPT.
In the import segment, no fresh bookings or new firm offers have been heard this week, while most import indications have remained broadly stable amid limited buying interest. Among non-EU suppliers, Turkish rebar offers are currently heard at $580-590/mt FOB, compared to $580-600/mt FOB last week. Taking into account freight costs of around €20-25/mt, these levels correspond to approximately €520-545/mt CFR Bulgaria, broadly stable week on week.
Egyptian rebar offers are currently estimated at $580-600/mt FOB, while wire rod offers are heard at $600-610/mt FOB. Based on prevailing freight rates of around €25-30/mt, these indications translate to roughly €530-555/mt CFR Bulgaria for rebar and €550-565/mt CFR Bulgaria for wire rod.
As for EU origin material, Italian rebar offers are still heard at around €655/mt CPT Bulgaria, unchanged from last week. Estimated Romanian rebar prices, meanwhile, have moved down by around €10/mt week on week to €650-660/mt delivered to Bulgaria.

Romanian longs prices soften as Italian arrivals deepen market pressure
The Romanian longs market has come under increased pressure this week, as the already weak demand has been accompanied by the arrival of previously booked Italian rebar cargoes in significant volumes.
According to market sources, several Italian suppliers had concluded sales to Romania earlier, with the overall volume estimated at around 50,000 mt. Although these bookings were not concluded this week, their arrival in the Romanian market has strengthened buyers’ expectations of lower prices and added pressure on sentiments. At the same time, the start of the summer slowdown, liquidity problems and cash flow constraints continue to limit trading activity, while many market players do not expect a meaningful recovery in the near term.
On the import side, Italian origin rebar has become the main focus of the market this week due to the arrival of these previously booked cargoes. Sources indicate that the FOB level for these sales was heard at around €600/mt, which would roughly correspond to around €620-625/mt CFR Romania, depending on freight costs and the terms of the deals. These levels have created a more competitive reference for the market and increased pressure on both import and domestic prices, especially as buying activity remains weak. Offers from Greece have also moved down this week, with rebar currently heard at around €650-660/mt CFR Romania and wire rod at €665-670/mt CFR Romania, compared to €655-665/mt CFR and €665-675/mt CFR, respectively, last week. Bulgarian rebar offers have remained stable week on week at around €650-660/mt CPT Romania.
On the non-EU import side, Egyptian rebar offers have remained stable at €535-555/mt CFR Romania, while wire rod offers continue to be heard at €555-565/mt CFR. Turkish rebar offers are currently heard at around €535-550/mt CFR Romania, compared to last week’s wider range of €530-555/mt CFR, based on an exchange rate of €1 = $1.14.
In the local spot market, domestic rebar prices in Romania have decreased to around €620-630/mt ex-warehouse this week, compared to €635-640/mt ex-warehouse last week. The pressure from competitive import levels has added to the already weak demand environment, while traders are also still holding relatively expensive material purchased earlier. Meanwhile, wire rod prices are currently heard at €680-690/mt ex-warehouse, slightly down from €685-690/mt ex-warehouse in the previous week.
Domestic producer Beltrame Group’s rebar offers are reported at around €635-640/mt ex-works this week, compared to last week’s level of approximately €640-650/mt ex-works.

German fabricators demand inclusion in EU import measures
Germany’s steel and metals fabricators are asking to be protected against imports to the same degree as steelmakers are, according to their federation Wirtschaftsverband Stahl- und Metallverarbeitung (WSM).
The federation has issued a call to the government and the European Union in reaction to the demonstrations by steelworkers for more political support earlier this month.
Those demonstrations “shed a limelight on 20%, while 80% are just extras in the background”, WSM states, referring to the ratio of jobs along the steel value chain, with fabricators provide five times as many jobs as the steelmakers.
“If you protect only the steelmakers from unfair imports, you are stopping short,” says WSM’s managing director, Christian Vietmeyer.
This echoes calls expressed at Kallanish’s Europe Steel Markets 2026 conference in Vienna this month, where speakers demanded that makers of steel-based products be included in the EU’s measures.
Players further down the chain are mainly small and medium enterprises (SMEs) which are fragmented, are easily overlooked, said Alexander Julius, president of distributors association Eurometal during a panel.
This puts them at a disadvantage against the mills, which traditionally have a strong lobby at EU level, he noted. Eurometal had earlier pointed out repeatedly that protection for mills makes little sense if their domestic customers remain under threat.
Domestic sheet formers, forges, makers of fasteners and springs and other components are pushed out of competition by pressure from Asia, Vietmeyer adds.
“A decline of orders has brought a profound structural crisis. To stop that trend, an expansion of the safeguards is unavoidable,” Vietmeyer says.
Meanwhile, the mechanical engineering association, VDMA, has warned against a widening of EU measures, arguing that it will block the entry of components that are not available in Europe (see Kallanish 16 June 2026).
An expansion of EU measures could therefore motivate the makers of big machinery and plants to cooperate more with European fabricators, making the development of components a joint effort, and so strengthen domestic value chains.
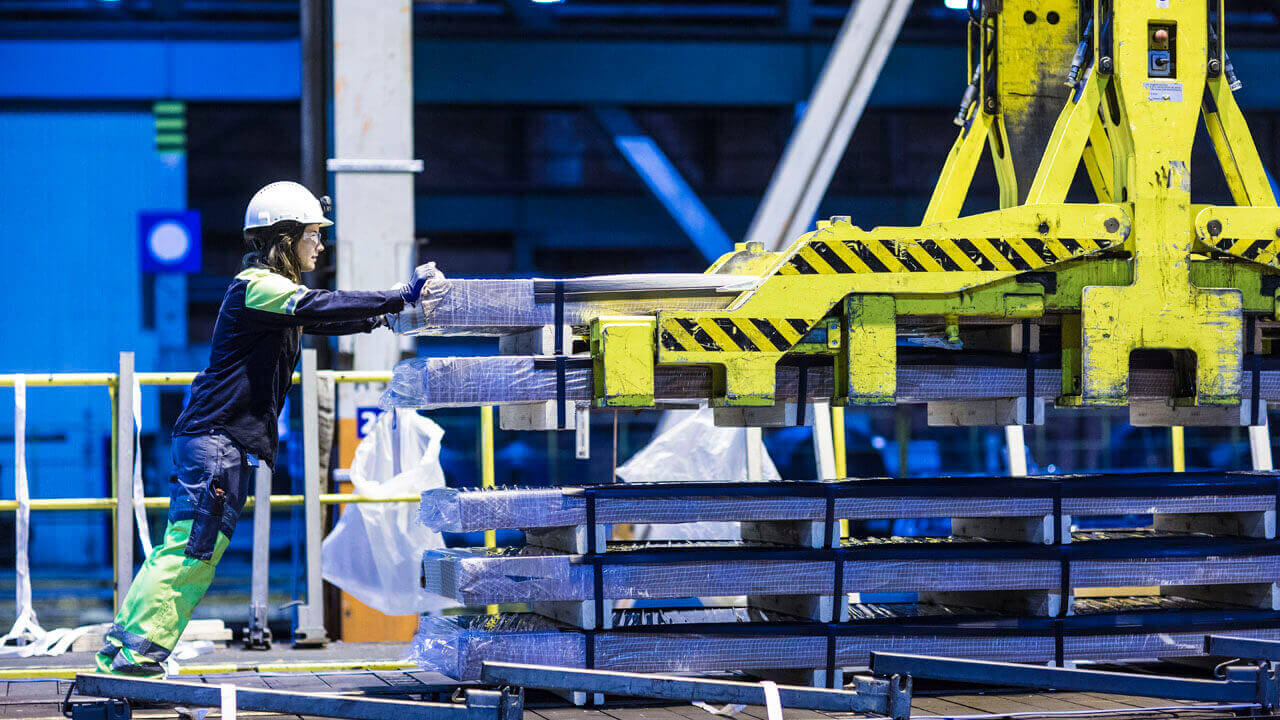
Finnish university, SSAB research future EAF technology
A new research project led by the Finnish University of Oulu and steelmaker SSAB will look to tackle the challenge of combining electric arc furnace technology with modernised hot rolling processes.
The solutions will support the transformation of Finland’s steel industry and its transition to low-carbon emissions steel production at the Raahe steelworks, Kallanish hears from the university.
The Future Sustainable Electric Steel Mill, known as FutSteel, research project has been selected as part of the Sustainable World Through Steels Flagship Programme, which will expand research and development activities in Finland, the university says. The budget of the FutSteel project is €17 million ($19m).
The project is starting this month and will run for three years. It will examine how production systems can be redesigned without compromising quality or delivery capability. “This is essential to ensure that high-quality steel production remains in Finland,” says Petri Sulasalmi, project manager of FutSteel at the university.
The project investigates how electric steelmaking can be combined with modernised rolling processes while utilising fossil-free energy solutions. The research focuses particularly on steel quality and on how new processes can be adapted to demanding high-strength steel production.
Besides SSAB, other steelmaker partners in the project include Ovako, plus other companies such as Hycamite, Otanmäki Mine, Strategic Resources, Titanor, Carbo Culture, Convion and Nordkalk.

Industry committee pushes broader CBAM expansion
MEPs on Parliament’s industry committee, ITRE, voted on 24 June to significantly broaden the range of products covered by the EU’s carbon border adjustment mechanism (CBAM).
The compromise amendment, backed by the EPP, S&D, Renew, and Greens groups, would extend the mechanism beyond those products proposed by the Commission to include a wide range of basic and semi-finished goods, household appliances, kitchen equipment, construction and handling machinery, transport equipment, and industrial products.
The text also removes a temporary suspension clause and deletes a reference to international carbon credits, a provision that had proved controversial.
It further strengthens measures against attempts to circumvent the CBAM and calls for the creation of key performance indicators to assess the mechanism’s effectiveness in protecting EU producers from international competition.
Parliament’s environment committee, ENVI, which leads work on the file, will be free to incorporate or disregard ITRE’s recommendations when it adopts its report on 6 July.