

British Steel highlights the role of steel production in the UK’s construction sector
Author: SteelRadar Editorial Team


European Commission approves Tenaris’ acquisition of Artrom Steel Tubes
Author: SteelRadar Editorial Team

Nippon Steel Slovakia assesses impact of EU’s new steel measures
EU to review anti-dumping measures on Chinese wire rod
Local HRC prices hold steady in Northern Europe, Italy on limited trading activity
Daily local steel hot-rolled coil (HRC) prices were mostly stable in Northern Europe on Wednesday October 14, with sources quoting weak demand and high stock levels. In the Italian market, requests for orders were increasing despite the limited transactions, market participants told Fastmarkets.
In Northern Europe, sources said weak demand and high stocks were limiting price increases in the market.
A buyer source reported offers within the range of €750-770 ($839-861) per tonne ex-works on Wednesday but said that workable prices should be around €740 per tonne ex-works. The higher offers were discarded from the index calculation due to a lack of buying interest for the upper end of the range.
A second buyer said that tradeable levels varied within €740-750 per tonne ex-works, adding that it was “hard to get anything below €740 per tonne ex-works.” The same source reported offers in the range of €750-760 per tonne ex-works.
A third buyer said tradeable levels were at €760 per tonne ex-works, but this price was discarded due to lower confidence in the participant’s view of the market.
Due to one source accounting for more than 50% of the final input, prices collected on Tuesday October 13 were copied over to Wednesday’s index, in line with Fastmarkets methodology.
On Tuesday, a seller source provided an indication of tradeable level within the range of €740-750 per tonne ex-works. A buyer source reported an indication within €740-760 per tonne ex-works on the same day and a second buyer source indicated prices at €740-750 per tonne ex-works.
Market participants said at the time that they expected some price increases by the end of 2026, linked to restocking and lower import activity because of the safeguard measures.
However, a fourth buyer disagreed with this scenario on Wednesday and said that they were not that optimistic about prices moving up toward the year end.
“Restocking for Q1 [first quarter] has not, and will not, take place to the extent needed to support price increases. I’m rather worried that the EU mills will not find sufficient orders for January-February rolling and therefore will adjust pricing downward to generate interest,” the same source said.
Thus, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €746 per tonne on October 14, down by €0.25 per tonne from €746.25 on October 13.
The index was down by €0.88 per tonne week on week but up by €8.50 per tonne month on month.
In Italy, the market was mostly quiet on Wednesday, with sources saying transactions remained limited, but added that the number of requests was increasing day by day.
A buyer indicated workable levels at €750 per tonne ex-works, in line with the latest deals and indications reported within €740-750 per tonne ex-works on Tuesday.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €745 per tonne on October 14, up by €0.31 per tonne from €744.69 per tonne on October 13.
The index was up by €3.75 per tonne week on week and by €8.75 per tonne month on month.

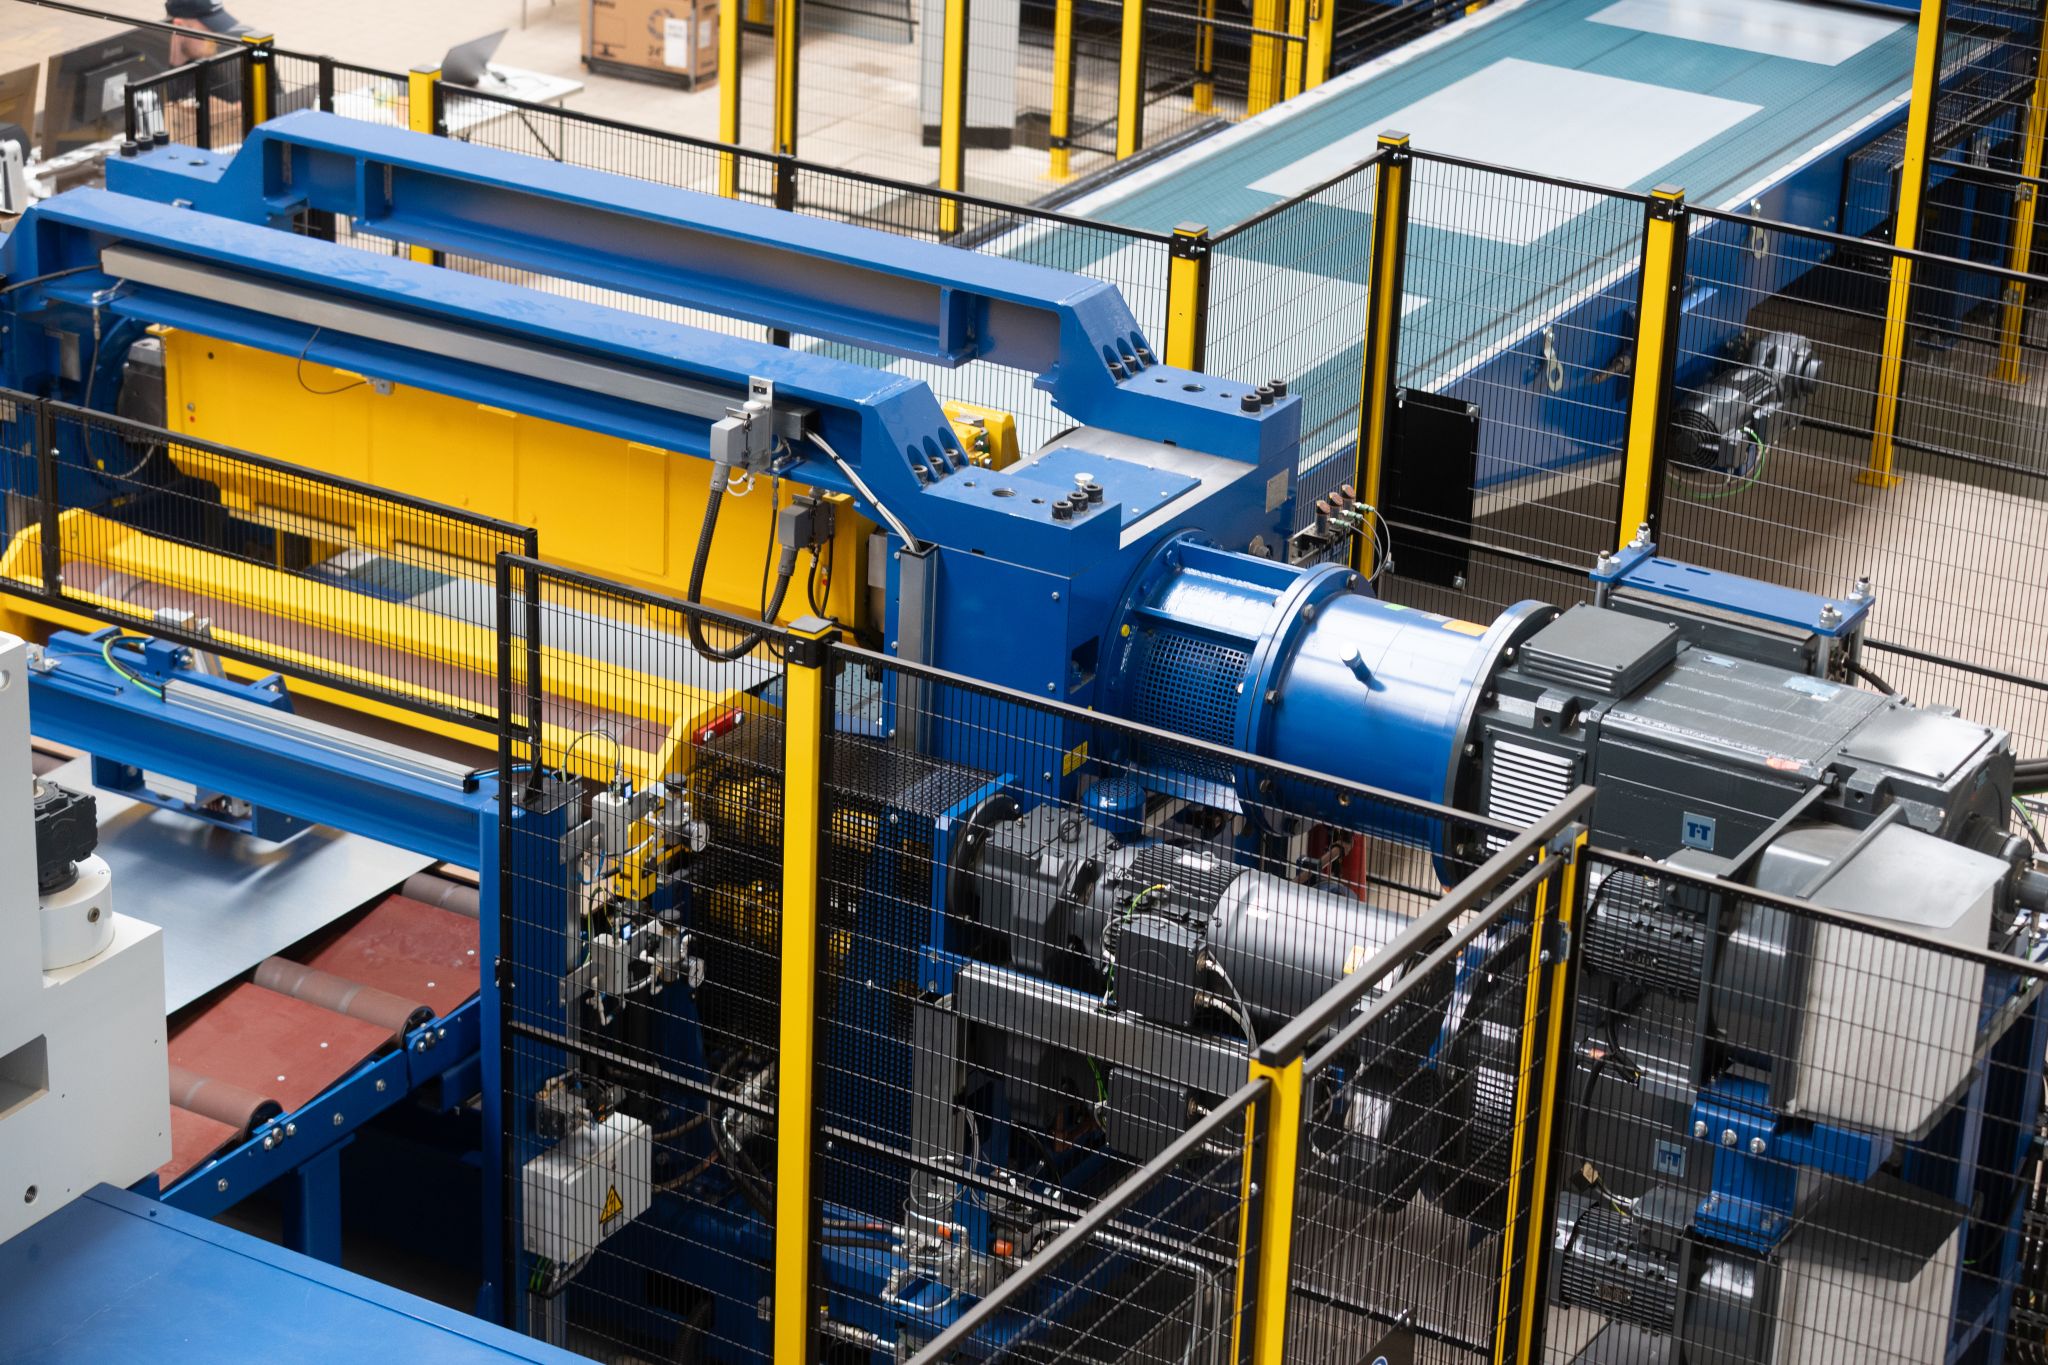
Knauf Interfer expands Delta Stahl service centre
German metals distribution group Knauf Interfer has started operation of two new production halls and a cutting line at its steel service centre Delta Stahl in Barsinghausen near Hanover.
One year after groundbreaking, the completed site has added 6,000m², and now has a size of 24,000m², Kallanish hears.
Knauf Interfer says that the investment in the site aims to improve efficiency and competitiveness of all its steel activities.
“We invest in a facility, and thus reinforce our entire network,” says Carsten G. Gast, ceo/cfo of Knauf Interfer.
The new cutting line will work sheet of widths between 500mm and 1,650mm, thicknesses between 0.5mm and 5,0mm, at speeds of up to 60metres/hour. It can also handle galvanized, surface treated, and oiled sheet in the minimum sizes, the company notes.
Parallel to the expansion, the company is also rebuilding the railway connection to allow for emission-reduced transport via rail.


Swiss Steel plans to sell some German plants
Swiss Steel has disclosed new details about its previously announced cutback plans for its German unit, Deutsche Edelstahlwerke (DEW).
It plans to sell, or close, two of its four plants in Germany; Hagen and Krefeld. If the negotiations do not lead to a successful conclusion, it intends to cease operating the sites. The comprehensive restructuring is intended to be implemented in stages over approximately the next two years.
DEW consists of four long-established sites, formerly owned by thyssenkrupp, each with different capabilities, production stages and equipment configurations: Hagen, Witten, Siegen and Krefeld. This is a technologically diverse but complex production network, with high fixed costs, numerous material transfers between sites and substantial investment requirements. At today’s structurally lower sales volumes, the available capacity can no longer be sufficiently utilised, Swiss Steel says.
Since 2021, market volumes have declined significantly across all product groups relevant to DEW, as the European long steel market has become structurally smaller, while key customer industries remain under pressure, Swiss Steel explains. DEW’s production system was designed for significantly higher volumes, the parent writes in a statement seen by Kallanish.
Over recent years, DEW has already initiated extensive improvement and restructuring measures, which have not sufficiently succeeded in returning the company to operating profitability, the parent notes. Its aim is to establish an industrial structure that is competitive over the long term. To achieve this, the remaining volumes will be concentrated on fewer facilities with higher utilisation, namely the works in Siegen and Witten.
Steelmaking operations will be concentrated in Witten, while operations at the Siegen steelworks will be temporarily suspended. If steelmaking at Siegen is discontinued for good, it would affect 400 of the 1,000 employees at the site, says local broadcasting station WDR, citing union IG Metall.
Witten offers the broadest product portfolio and covers all three speciailty steel segments – engineering steel, stainless steel and tool steel. Witten is already positioned towards higher-margin and growing end markets such as civil aviation and the defence industry, and is less dependent on the shrinking automotive industry, the statement says.
Italian decree buys Taranto additional time
Italy’s cabinet approved a new decree-law on 13 October to support Acciaierie d’Italia (ADI), also known as former Ilva, and its direct and contractor workers.
The decree-law responds to “urgent measures to support workers at former Ilva and its supply chain, and to relaunch industry in the area,” the government says in a note obtained by Kallanish.
The decree allows the special commissioners to keep the Taranto blast furnaces and steel shop hot in order to avoid irreparable damage to the equipment. This applies until the publication of the reasoning behind the expected Supreme Court’s ruling on 20 October.
The reasoning will be published by 15 December. Emissions monitoring must continue even though production has stopped.
To keep the plants operational during the ongoing sale process, the government will also release the final tranche of an existing loan to ADI which a source close to the company believe to be around €40 million.
The decree also aims to bring new industry to Taranto beyond steel.
Italy’s Ministry of Enterprises and Made in Italy (MIMIT) will gather and coordinate proposals for private investment on ADI’s land and on nearby state-owned port and military areas suitable for industry. It will then draw up an investment plan for cabinet approval.
As part of the sale process, the special commissioners will also be able to sell or lease land not used for steel production separately, as long as the projects are included in the plan.
Meanwhile, a Fiom union source confirms that Fim, Fiom, Uilm unions will implement a 48 hour strike.
IMF forecasts global economic growth to slow to 3.1 percent in 2026 amid energy price pressures
The International Monetary Fund (IMF) has forecast that global economic growth will slow from 3.5 percent in 2025 to 3.1 percent in 2026, before recovering to 3.4 percent in 2027, according to its October 2026 World Economic Outlook report.
The IMF maintained its 2026 global growth forecast from April while revising its 2027 projection upward by 0.2 percentage points. Despite the global economy’s resilience amid geopolitical conflicts, energy market disruptions and trade tensions, the organization warned that economic and policy buffers are becoming increasingly limited.
Growth in advanced economies is expected to reach 2.1 percent in 2026, before slowing to 1.8 percent in 2027. Meanwhile, emerging and developing economies are projected to expand by 3.7 percent in 2026, down from 4.5 percent in 2025, before recovering to 4.4 percent in 2027.
US economic growth expected to remain at 2.3 percent, while EU and euro area growth remain subdued
The US economy is expected to grow by 2.3 percent in both 2026 and 2027, supported by resilient private consumption, fiscal policies and continued investment in artificial intelligence (AI) and other technologies. US inflation is projected to increase from 2.7 percent in 2025 to 3.6 percent in 2026, before easing to 2.8 percent in 2027.
In the EU, economic growth is forecast at 1.4 percent in both 2026 and 2027, compared with 1.5 percent in 2025. Euro area growth is expected to slow from 1.2 percent in 2025 to 1.1 percent in 2026, before recovering to 1.2 percent in 2027, as higher energy prices and weak consumer confidence continue to constrain economic activity. Euro area inflation is projected to rise to 3.1 percent in 2026 from 2.1 percent in 2025, before declining to 2.8 percent in 2027.
Growth to slow in China and Turkey in 2026, while India maintains strong momentum
China’s economic growth is projected to decline from five percent in 2025 to 4.5 percent in 2026 and four percent in 2027, reflecting higher energy prices, prolonged uncertainty and structural economic constraints. Chinese inflation is expected to increase from zero in 2025 to one percent in 2026 and 1.4 percent in 2027.
Meanwhile, India is expected to remain among the fastest-growing major economies, with growth forecast at seven percent in both fiscal years 2026 and 2027, supported by resilient domestic demand and strong services activity. On a calendar-year basis, India’s growth is projected at 7.4 percent in 2026 and seven percent in 2027. Indian inflation is expected to increase from 2.0 percent in 2025 to five percent in 2026, before declining to 4.4 percent in 2027.
Regarding Turkey, the IMF expects economic growth to slow from 3.7 percent in 2025 to 2.7 percent in 2026, before recovering to 3.6 percent in 2027. Average consumer price inflation in Turkey is projected to decline from 34.9 percent in 2025 to 31.2 percent in 2026 and 26.5 percent in 2027.
Global inflation expected to rise to 4.7 percent amid higher energy prices
The IMF expects global headline inflation to rise from 4.1 percent in 2025 to 4.7 percent in 2026, mainly due to higher energy and food prices, before declining to 4.1 percent in 2027. The report assumes an average oil price of $95.74 per barrel in 2026, up 41.3 percent from $67.74 per barrel in 2025, before declining to $87.39 per barrel in 2027. Nonfuel commodity prices are expected to increase by 17.3 percent in 2026.
Meanwhile, global trade volume is projected to increase by 4.6 percent in 2026 and 4.7 percent in 2027, supported partly by technology-related trade despite tariffs and the reorganization of international supply chains. The IMF warned that further disruptions to energy supplies, prolonged conflicts, renewed trade tensions, high public debt and tighter global financing conditions could weaken economic activity.
It also highlighted risks associated with the concentration of investment in AI-related industries, noting that a reassessment of expected returns could trigger financial market corrections and lower investment. To strengthen economic resilience, it recommended credible fiscal adjustment, monetary policies focused on price stability and greater diversification of energy supplies, critical technologies and international trade relationships.

SSAB begins construction of quenching line in Oxelösund
Swedish specialty steel producer SSAB has announced that it has started construction of a new quenching line at its Oxelösund steel mill in Sweden, marking the implementation phase of a SEK 3.3 billion ($331.6 million) investment announced in May this year.
The new facility will increase the company’s annual production capacity for advanced high-strength wear-resistant and protection steels by approximately 100,000 mt. Production is scheduled to begin in 2030.
New quenching line to expand Hardox and Armox production capacity
The investment is aimed at expanding SSAB Special Steels’ capacity for advanced products, including Hardox wear-resistant steels and Armox protection steels, which are used in demanding industrial, safety and defense-related applications.
Quenching is a heat-treatment process in which steel is rapidly cooled to achieve high hardness and strength. The new line will enable SSAB to increase production of some of its most advanced and high-value steel grades.
According to the company, the investment forms part of its strategy to strengthen its position in premium steel products and expand its offering of advanced steels.
Johnny Sjöström, SSAB President and CEO, stated that the investment would increase capacity for differentiated products while the company finalizes the conversion of its Oxelösund steel mill. He also highlighted the role of modern electrified technology in expanding SSAB’s production system and meeting customers’ requirements for performance, durability and protection.
Investment accompanies Oxelösund steel mill transformation
The construction project is being carried out alongside SSAB’s broader transformation of its Oxelösund operations, which includes replacing conventional blast furnace-based steelmaking with electric arc furnace (EAF) technology.
According to SSAB’s second-quarter 2026 report, the new EAF at Oxelösund is under installation, with production scheduled to begin in the second quarter of 2027.