

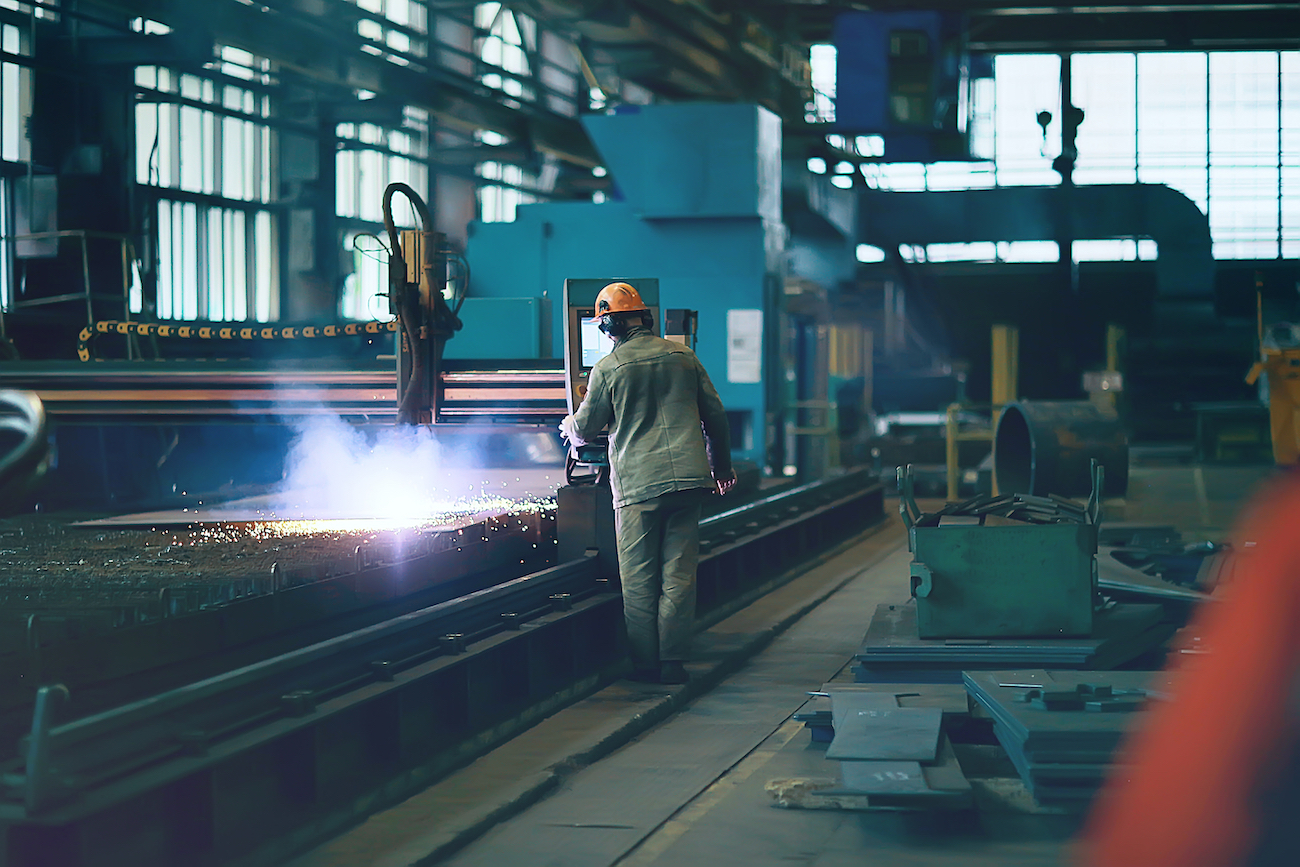
German machinery industry registers tepid spring improvement
Germany’s mechanical engineering industry saw a gentle increase in orders in the first four months of the year, but the overall picture does yet indicate a rebound from the long-term lull.
In the first quarter, the companies in this sector lifted orders by 4% in comparison with Q1 2025, Kallanish learns from their federation VDMA. The orders came mainly from abroad, rising 6% year-on-year, while domestic order activity actually suffered another dip, by 2% y-o-y.
VDMA also cautions that the positive quarterly figure is based on an irregularly strong intake in March. After two disappointing months, March saw an increase of 27% y-o-y, boosted by orders for large plant-building projects. “Such special effects are welcome, but they paint a rosier picture than the reality, and do not signal a broad upswing,” says VDMA chief economist Johannes Gernandt.
He notes the wars in the Gulf region and in Ukraine, as well as US protectionism are keeping industries away from making investments into production equipment. He also criticises the German government, which he says after one year in office has stood out more for internal disagreements, rather than for providing conditions that improve German machinery makers’ international competitiveness.
The mixed picture for the industry continued into April. Order intake was 4% higher than in the corresponding 2025 month. But again, foreign orders went up 8%, while domestic orders remained 7% below April 2025.
Gernandt therefore reiterates the industry’s demands to the government. “We need lower taxes for companies, more flexibility with the workforce, an alleviation of costs for bureaucracy, and a reform of the social insurance system,” he says.
Author: Christian Koehl


Germany’s crude steel production maintained its growth in May

Liberty Galați steel complex tender concludes without bids, search for investors continues

Steel: a burning issue of sovereignty
As Brussels seeks to secure its transatlantic trade relations, the continent’s leading steel producers are calling for a reform of the European Union Emissions Trading Scheme (EU ETS) in order to safeguard their competitiveness.
Faced with the need to drastically reduce its carbon emissions whilst contending with ever more aggressive international competition, the steel industry once again epitomises Europe’s contradictions.
Two separate cases highlight this. On the one hand, the European Parliament has given the green light to the implementation of the tariff commitments agreed between the European Union and the United States under the Turnberry Agreement.
On the other hand, ArcelorMittal, Thyssenkrupp Steel and Voestalpine – which together account for nearly 60% of integrated steel production in Europe – are calling for a reform of the European Union Emissions Trading Scheme (EU ETS). Despite their different natures, these two initiatives share a common concern: to preserve European production capacity against a backdrop of profound transformation in the global economy.
Europe is strengthening its trade safeguards
The agreement reached with Washington aims to ease several years of trade tensions and provide greater certainty for businesses on both sides of the Atlantic. However, Brussels was not prepared to open up its market without receiving something in return. The texts adopted include, in particular, safeguard mechanisms enabling the EU to respond in the event of a significant trade imbalance. They also introduce clauses suspending tariff preferences should the United States maintain certain customs barriers on products derived from European steel and aluminium.
For the European institutions, the challenge is clear: to promote trade whilst ensuring that European industry is not undermined by asymmetrical trade practices. This approach is part of a broader shift in European economic policy. In the face of the resurgence of industrial policies in the United States and China, competitiveness has once again become a strategic priority in Brussels.
Decarbonisation at the right pace
It is precisely on this issue of competitiveness that the major European steelmakers have chosen to raise their concerns with European decision-makers. In their joint statement, ArcelorMittal, Thyssenkrupp Steel and Voestalpine do not dispute the EU’s climate targets. All have made significant investments in production technologies that emit less CO2. Their concern relates more to the gap between regulatory ambitions and industrial realities.
With green hydrogen still being expensive, electricity prices among the highest in the world and inadequate carbon capture infrastructure, the conditions for competitive decarbonisation have not yet been met for these three steelmakers. As the cost of carbon continues to rise, these three companies fear that this situation will put European producers at a disadvantage compared with competitors subject to less stringent constraints. This brings with it all the associated risks in terms of industrial sovereignty.
They are therefore calling for a temporary suspension of the increase in ETS costs – with prices remaining at current levels until the key drivers of economically viable decarbonisation are in place – support for businesses embarking on decarbonisation, and border measures to ensure a level playing field in international competition.
Behind these two issues lies a more fundamental question: what role does Europe still wish to play in the global industry of the future?

Nordwest Handel lifts steel tonnages, revenue
Nordwest Handel, through its steel division Phoenix, lifted the turnover of its steel products in 2025, after two years of decline, and has continued that trend into this year so far.
As one of Germany’s big purchasing cooperatives for hardware, sanitary equipment, construction materials and steel, Nordwest Handel achieved total revenues of €4.65 billion ($5.39 billion) in 2025, broadly on par with the previous year.
In terms of volumes, steel is the cooperative’s biggest divisions, with revenues of €1.56 billion, marking an increase of 3.2% year-on-year. In terms of volume, Phoenix handled 1.64 million tonnes of steel for its member companies, rising by 1.6% from 2024.
It its report, Nordwest notes that the increase occurred mainly in the first half of the year, while the second half saw a negative development with a year-on-year drop of 3.3%.
It adds that the overall positive development in the first half resulted both from an increase in sales volume and from a higher average price level over the year.
The increase of volumes was more pronounced in the first half, Kallanish hears from the head of the Phoenix division, Claudio Kemper. He attributes this to higher demand for rebar, which accounts for more than half of Nordwest’s steel sales and benefited from a mild recovery in construction activity. He believes that the second half saw the reservation of orders due to insecurities in view of the upcoming CBAM regulation.
In the first quarter of the current year, Phoenix reported a y-o-y increase of 6.5% over an already strong Q1 in 2025, achieving revenues of €419 million. The unit represents more than 100 steel buying companies in Germany.

Thyssenkrupp to float materials division tk accelis
Thyssenkrupp steel distribution division tk accelis – formerly thyssenkrupp Materials Services – is to be spun-off and listed on the stock exchange.
The division has 15,500 employees, around 250,000 customers worldwide, and generates revenue of €11.4 billion ($13.2 billion), with 7.6 million tonnes of material sold in the 2024/25 fiscal year.
It emerged on the market under the new brand just a few days ago, which was the first step on the path towards independence (see Kallanish 11 June 2026). According to the parent group, tk accelis benefits from a strong position in fast-growing industries such as aviation, defence, and data centres, and therefore has a strong operating base for its next step on the capital markets.
The plans involve transferring a 49% minority interest to the shareholders of thyssenkrupp AG in proportion to their interest in thyssenkrupp AG and listing the shares on the Frankfurt Stock Exchange. The spin-off requires the approval of an extraordinary general meeting, projected for 7 August. If the general meeting approves the resolution, thyssenkrupp will retain a majority stake even after the spin-off. Tk accelis would then remain a fully consolidated company within thyssenkrupp, the group states.
“Tk accelis has made impressive progress in recent years. Its ceo, Ilse Henne, and her team are systematically positioning the company as a fully integrated materials distributor and powerful supply chain service provider,” says thyssenkrupp AG chief executive Miguel López. “Now is the right time to take the next step and establish tk accelis as an independent company.”

EU steelmakers call for ETS cost freeze
Europe’s leading steelmakers have called on European policymakers to stop Emissions Trading System (ETS) cost escalation until companies have solid business cases for transformation investments.
The European Commission is due to present its eagerly awaited ETS review in July, Kallanish notes.
In a letter addressed to European Council President António Costa and European Commission President Ursula von der Leyen, the firms, including ArcelorMittal, thyssenkrupp, voestalpine, Moravia Steel and Vitkovice Steel, demand “decisive intervention” to arrest ETS costs. This includes recalibration of ETS free allocations, benchmark methodologies and values, CBAM factor and the Cross-Sectoral Correction Factor (CSCF).
“Further conditionalities to free allocation as currently discussed must be avoided as this would weaken the intended carbon-leakage prevention,” the firms say.
This intervention must allow firms to build solid business cases for transformation investments, supported by “comprehensive and reliable policies” to incentivise the uptake of low-carbon and circular products, they add. ETS revenues should also be “channelled into accessible, technology-neutral industrial transformation support linked to verified emissions reductions.”
“The ETS no longer reflects current global realities. Europe is effectively acting alone in imposing rapidly rising carbon costs on its industry,” the letter asserts. Meanwhile, the conditions required for industrial transformation are not in place, with critical infrastructure for energy, CO2, hydrogen and CCS missing or insufficient. Investment frameworks are unreliable, and customer demand and willingness to pay for low-carbon products are low, the signatories note.
CBAM remains untested and leaves downstream industries exposed, they add.
“If current policies continue, rising carbon costs will be passed on value chains, triggering downstream carbon leakage, compressing margins, scaling back production and accelerating plant closures. The consequences – job losses, reduced investment, and weakening economic growth – are foreseeable,” the letter reads.
“Time is running out. Decisive and immediate policy correction is required to preserve Europe’s industrial foundation and enable a credible path to transformation,” it concludes.

German recycling associations BDSV and VDM unite to form Circular Metal Association
The German Steel Recycling and Disposal Association (BDSV) and the German Association of Metal Traders and Recyclers (VDM) have announced that they have signed a merger agreement, establishing the legal foundation for the creation of the Circular Metal Association (CMA).
The new organization will serve as the unified representative of Germany’s steel and metal recycling industry at national, European and international levels.
Merger expected to take effect in coming weeks
The merger will become effective once it is registered in the association register, a process that is expected to be completed in the coming weeks. Until then, both organizations will continue operating under their existing structures.
Following registration, BDSV and VDM will cease to exist as independent legal entities, with all rights, obligations and memberships transferred to the CMA.
CMA to represent the full recycling value chain
The Circular Metal Association will represent the entire value chain of steel and metal recycling, including collection, processing, trading and supply to the metalworking industry. Its scope will also cover the trade of primary metals, ferroalloys and special metals.
According to the associations, the CMA aims to strengthen the sector’s representation before German policymakers as well as European institutions, including the European Parliament and the European Commission. The organization will also represent the industry within international bodies such as Recycling Europe and the Bureau of International Recycling (BIR).


Trading activity in European steel HRC market remains slow on high stocks, uncertainty
The European market for steel hot-rolled coil remained slow on Monday June 15, mainly due to uncertainty caused by the imminent imposition of a new safeguarding regime. Some demand appears only from buyers who need to restock before the start of the summer holiday period, while stocks are predominantly high, sources told Fastmarkets.
The market is affected by “uncertainty about Carbon Border Adjustment Mechanism (CBAM), new quota, increasing energy costs due to [conflict between Iran and the US]; and we are close to summer holidays, so a big improvement is not likely before the summer,” one trader said.
In Northern Europe, offers of material scheduled for delivery in late July-September were heard within the range of €710-720 ($821.48-833.05) per tonne ex-works. Meanwhile, the workable level was estimated at €680-700 per tonne ex-works.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €692.50 ($801.24) per tonne on June 15, up by €7.29 per tonne from €685.21 per tonne on June 12.
The index was slightly up by €0.50 per tonne week on week and up by €8.75 per tonne month on month.
In Italy, offers varied within the range of €685-695 per tonne ex-works, with indications of tradable levels within the range of €680-685 per tonne ex-works. For large tonnages, the workable level was reported at €675 per tonne ex-works.
“There was some activity because some buyers wanted to restock before the start of summer holidays — in southern Europe it normally starts earlier than in Northern [Europe],” another trader said. “People want to have some stocks for the future because an increase in prices is possible. Mills are pushing prices up.”
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €684.50 per tonne on June 15, down by €3.00 per tonne from €687.50 per tonne on June 12.
The index was up by €3.67 per tonne week on week and down by €0.33 per tonne month on month.

