French long product prices are remaining mostly stable compared to the pre-holiday levels, though in some contracts and certain products moderate decreases are reported, Kallanish hears.
Since the activity resumption last week, the market has been uneventful with little appetite for material. Large steel processors report some financial difficulties and struggle to afford price increases.
Broadly speaking, with the flats and longs price increases seen in recent months, since the Middle East conflict started, margins have recovered, and volumes downstream are mostly stable year-on-year.
Over the course of the year, however, downstream margins have come under pressure from rising costs.
Looking ahead, pessimism is growing in the downstream sector as the French economy remains subdued and, according to the latest quarterly data, has only narrowly avoided recession. The construction sector, particularly private residential, remains weak, and the new infrastructure projects supported by post-Covid recovery funds are ending this year.
One large buyer, also pessimistic about the outlook, says the upcoming elections will slow activity. “Elections will have a strong impact on our business and this is happening during a period of great uncertainty,” he says.
In flat products, black hot rolled sheet prices are on the rise to €820-840/tonne ($957-980/t) delivered, in line with higher coil prices across Europe. This is up significantly from the level of €800/t seen at the end of July, just before the sector’s August shutdown.
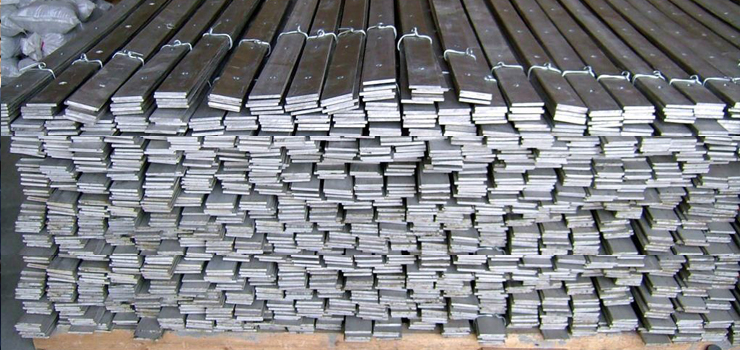
Long product consumption remains limited as companies try to reduce exposure. Domestic merchant bar is at €290-300/t base delivered, excluding size extras of around €410/t, slightly below July levels as many buyers turned to Spanish producers offering competitive prices.
New contracts, however, are seen higher, with domestic merchant bar expected to recover to €310-320/t base delivered. Meanwhile, despite the several increase attempts for sections over the past months, prices for the first category material have remained stable at €800-810/t delivered.
Rebar levels are also flat compared to the pre-holiday levels with an uncertain market and limited volume orders. Values remain between €680-710/t delivered, sources suggest.