


ArcelorMittal rolls first coil on Mardyck electrical-steel lines
ArcelorMittal has produced its first coil on the new production lines at its Mardyck site in northern France, marking a key step in the ramp-up process. Industrial tools and processes will now be refined ahead of full-line validation and first customer deliveries.
The company is expanding its portfolio in non-grain-oriented electrical steel (NOES) and introducing upgraded high-polarisation grades, new self-bonding varnish (SBV) coating solutions, and its latest high-specification low-loss iCARe 420Save grades designed for e-traction applications.
The first coil produced weighs over 17 tonnes and spans nearly four kilometres in length. It passed through the first three lines of the new production chain, the preparation line, the annealing and coating line, and the slitting line. Electrical steels produced by ArcelorMittal across its Mardyck and Saint-Chély-d’Apcher sites in the Lozère region will be used in electric motors and generators in the automotive, wind energy and industrial sectors, the company notes.
“Several months will be needed for the new lines to reach full operational capacity. The skills, know-how and energy of the 175-strong new team, along with feedback and expertise from the ArcelorMittal group, will be the key drivers of success,” the steelmaker says in a note obtained by Kallanish.
The Mardyck expansion is a strategic growth project for ArcelorMittal, tripling the group’s electrical steel production capacity in Europe. Combined with the existing Saint-Chély-d’Apcher facility in the Lozère region, the group’s European electrical steel capacity will reach 295,000t annually. All of ArcelorMittal’s European electrical steel output will be produced in France, “consolidating the country’s industrial ecosystem around electromobility and the energy transition”, the note continues
Electrical steels are used in motors in the form of stacked ultra-thin layers, between 0.2 and 0.35 millimetres thick in automotive applications. They are characterised by a combination of precise magnetic and mechanical properties.
This $500 million investment in the new Mardyck lines is ArcelorMittal’s largest in Europe in the past ten years (see Kallanish passim).


Tube sector expects demand boost, margin pressures: ITA
The outlook for the tube and pipe market remains positive, supported by energy security concerns, new pipeline projects, growth in carbon capture and hydrogen infrastructure, industrial growth in India, China and the Middle East, and global infrastructure development, Kallanish learns from the International Tube Association (ITA).
However, the market environment is expected to remain volatile in the short term due to geopolitical risks, high energy costs, trade restrictions and investment uncertainty, an ITA report explains. Stronger growth is expected in the longer term.
In 2025 the global tube and pipe market recovered, with production increasing by 10% year-on-year to an estimated 177.9 million tonnes, driven mainly by pipeline construction linked to energy security concerns and shifting global gas flows.
Production growth was strongest in pipeline tubes larger than 16” outside diameter, rising by 37% to 31mt in 2025, from 22.5mt, driven by new pipeline projects linked to global energy logistics.
Tube pricing shows mixed trends, with OCTG prices declining to around $1,800/t in early 2026 from about $2,000/t in 2025. Structural pipe prices have been relatively stable at around $600/t, supported by infrastructure demand, although margins are increasingly under pressure due to rising input costs.
The cost base is becoming increasingly volatile, ITA notes, as around 73% of global pipe production is welded pipe, meaning producers are highly exposed to hot-rolled coil prices.
Regional differences in electricity and gas prices remain a key factor determining global tube and pipe production costs and competitiveness. Producers in the US, China, India, Türkiye and the Middle East benefit from structurally lower energy costs. European producers face significantly higher electricity and LNG prices, pressuring margins, limiting production and increasing the risk of production shifting to lower-cost regions.
China accounts for around 52% of global output. India is the fastest-growing producer, according to the association. The US market is supported mainly by pipeline demand, while Europe remains constrained by high costs and relatively weak industrial demand. Energy costs are a major risk factor for tube prices, particularly in LNG-dependent regions where gas prices increased sharply following disruptions in the Strait of Hormuz. Oil price fluctuations, which directly affect OCTG demand, hot-rolled coil price movements, geopolitical disruptions and trade measures remain additional sources of price volatility.
Since late February, oil prices increased from around $60/barrel to more than $100/bbl. The new, higher levels support OCTG demand but increase cost volatility and economic uncertainty.
The ITA report notes that the oil and gas sector remains the dominant consumer, accounting for around 51% of global tube demand, followed by automotive, mechanical engineering and construction. Pipeline construction, shale gas development and corrosion-resistant applications continue to support OCTG and line pipe demand. New demand segments are emerging from hydrogen transport, carbon capture infrastructure and electric vehicle production, where tubular products are increasingly used in vehicle structures.
Duferco Travi e Profilati earns GSCC decarbonisation certification
Italian longs producer Duferco Travi e Profilati has received certification of its corporate average steel emissions intensity (CASEI) and science-based emissions target (SBET) from the Global Steel Climate Council (GSCC), Kallanish notes.
The certification was verified by Italian certification body Rina Services. Duferco Travi e Profilati which produces sections from scrap using renewable energy, recorded a base emissions intensity of 1.13 tonnes of CO2e/t of hot-rolled steel in 2022, and has set an interim target of reaching 1.01t of CO2e/t by 2030, with a long-term target of 0.12t of CO2e/t by 2050.
The targets are aligned with the GSCC Steel Climate Standard, a global benchmark for measuring steel carbon emissions. The standard provides a science-based framework for members to obtain third-party certification of emissions intensity and conduct annual self-audits to track decarbonisation progress. It supports the Paris Agreement’s 1.5°C warming limit goal.
“This achievement confirms the validity of our approach, based on the use of recycled raw materials, the efficiency of production processes, and the use of renewable energy. We have defined clear and measurable targets, aligned with the most rigorous international standards, because we believe that the transition to a low-emissions steel industry must be built on transparent and verifiable data. We will continue to invest in innovation and sustainable technologies,” Duferco Travi e Profilati general manager Simone Campanella says in a joint note obtained by Kallanish.
According to GSCC nearly 3 million tonnes of CO2e have been avoided through independently verified reductions, “demonstrating what is possible when climate commitments are grounded in accountability and transparency,” GSCC executive director Adina Renee Adler concludes.

Tata Steel IJmuiden stops plant amid environment issues
Tata Steel Nederland has announced it is to temporarily shut down the direct sheet plant (DSP), its casting roller plant, in Ijmuiden, Kallanish learns from a statement.
“Recent emission measurements show that the emission of chromium-6 at one chimney is higher than the legal standard,” the company says.
“Because safety and the environment are our main priority, we take this measurement very seriously. In consultation with the North Sea Canal Area Environment Agency (ODNZKG), we have decided to shut down the DSP. We are currently working on additional technical and organisational measures to reduce Chromium-6 emissions. Only after we have tested that the DSP fully meets all standards again, we will take the installation into normal use,” it adds.
It has informed the Environment Agency of the decision and will continue to do so in the measures to be taken.
Previously, the coke plants at Tata Steel IJmuiden were targeted by Extinction Rebellion (XR) just weeks after it was ordered by Dutch environmental regulators to rectify emissions issues.

European mills push steel HRC prices higher for July but buyers push back
European producers of steel hot-rolled coil have increased their offer prices for third-quarter deliveries but buyers have stepped back to digest the higher prices, Fastmarkets heard on Tuesday April 7.
Trading activity remained slow across the European HRC markets after the Easter break.
Major European suppliers were largely sold out for second-quarter delivery HRC, with only limited availability from some sellers.
Meanwhile, offers of July-delivery coil had already been reported at much higher prices before Easter.
In Germany and the Benelux area, integrated mills were hoping to achieve €750-760 ($867-879) per tonne ex-works, Fastmarkets heard.
No sales were reported at the new prices, with buyers taking a wait-and-see approach for now.
“July is too far away and demand is not supporting such price jumps. European mills rely too much on regulations [such as safeguards and the Carbon Border Adjustment Mechanism (CBAM)] to support the uptrend,” a distributor in northern Europe said.
“Stocks are still too high. We do not need material for July,” a steel-service centre (SSC) in Germany said.
In contrast, in the second half of March, deals for June-delivery coil in Northern Europe were heard at €700-730 per tonne ex-works.
On April 7, buyers’ estimates of achievable prices in the region were reported at €700-730 per tonne ex-works.
As a result, Fastmarkets’ daily steel hot-rolled coil index, domestic, exw Northern Europe, was calculated at €718.25 per tonne on April 7, down by €0.51 per tonne from €718.76 per tonne on April 2.
Fastmarkets’ European HRC indices were not published on April 3 and April 6 because of the Good Friday and Easter Monday holidays in the UK.
The Northern Europe index was, however, up by €6.75 per tonne week on week and up by €18.25 per tonne month on month.
In the secondary market, trade sources reported that SSCs were gradually pushing prices toward €820-830 per tonne CPT for 4mm S235 grade hot-rolled (HR) sheet, with transactions already concluded at €800 per tonne CPT. But sporadic sales were still being reported around €750-770 per tonne CPT and even lower, continuing to disrupt price stability.
“Some SSCs keep selling HR sheet even at €740 per tonne CPT, using old feedstock,” a buyer in Germany said.
Meanwhile, in Southern Europe, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy, was calculated at €698.75 per tonne on Tuesday, unchanged since April 2.
But the index was up by €3.75 per tonne week on week and up by €17.92 per tonne month on month.
The Italian market was also quiet, with no major trading reported on Tuesday.
Offers of June-delivery HRC from local sellers were heard at €700-705 per tonne ex-works on Tuesday, while buyers’ estimates of achievable prices were heard at €690-700 per tonne ex-works.
In the secondary market, sources reported that, for 4mm S235 grade hot-rolled (HR) sheet, €800 per tonne CPT was being gradually achieved in deals, with only occasional deals heard at lower prices of €760-780 per tonne CPT.
Meanwhile, the market for imported coil was totally quiet on Tuesday, with CBAM, safeguard measures and the conflict in the Middle East significantly limiting “safe” import options for European buyers.
“Freight costs are increasing, insurance costs are dramatically high, CBAM costs are uncertain, [country-specific] quotas for new safeguards to start on July 1 are unknown – it’s simply gambling [to deal with imports],” a buyer in Europe said.
HRC offers from Turkey to Italy were heard at €620-630 per tonne CFR on Tuesday and at €630-640 per tonne CFR from Algeria.

UK looks to rebalance import-heavy steel market despite downstream resistance
The UK government was hoping to balance enhanced support for domestic steelmaking with continued access for downstream processors after announcing new steel trade measures that will take effect from July 1, 2026.
The UK government unveiled late in March a sweeping support package for the country’s steel sector, combining stricter import controls with a long-term industrial strategy intended to raise local steel production.
It would entail reducing overall quota volumes for imports by 60% compared with the existing steel safeguard measures, with any import volumes above these levels facing a 50% tariff.
Although the measures were welcomed by UK steelmakers with melting facilities, the harsher import rules were questioned by traders and downstream processors.
But in an update published on April 2, the UK Department for Business and Trade announced that it intended to allocate an additional specific quota for use in downstream processing.
UK steel output dropped to 2.50 million tonnes per year in 2025, down by 38% year on year, according to the World Steel Association.
And the UK imported 7.15 million tonnes of iron and steel products over the year, according to UK customs data cited by Global Trade Tracker. This was up by 10.9% year on year from 6.45 million tonnes in the previous year.
Downstream challenges
Plans to drive down the volumes of steel imports into the UK were debated widely on social media following the March announcement.
“Such protectionist measures could allow domestic producers to increase prices to sustainable levels while remaining competitive,” Laurence McDougall, owner of All Steels Trading, said on social media in late March.
“Some producers are suggesting that this environment could enable them to increase domestic market share to 50% from approximately 30%, a rise in domestic sales of around 66%,” he said.
“As UK stakeholders, we all want to see our steel industry thrive, particularly where state participation is involved,” he added. “But a key question remains: will end-users be able to absorb significantly higher steel prices while still competing against imported finished goods that are not subject to equivalent duties?”
If this imbalance were not addressed, McDougall said, there would be a risk that domestic steel consumption could fade away unless the government closed such loopholes.
“These measures are nothing but harmful to the UK steel industry as a whole, and the UK economy, more importantly,” Nick Lally, owner of Steel Traders Midlands, said on social media in late March.
“Simply, the UK does not produce enough steel to satisfy the demand. Even if they could, the range of steel produced is not sufficient either,” he said. “Imports need to happen.”
This challenge to traders came at a time of rising freight costs, exacerbated by the conflict in the Middle East. Shipping costs from Turkey to the UK have risen by as much as $50 per tonne due to increased risks and higher marine diesel prices, McDougall said.
Category 1 authorization
In its April 2 update, the UK government confirmed that it will continue to allow defined volumes of steel products to enter the UK tariff free through a system of tariff rate quotas, applied on a quarterly basis and allocated on a first come, first served basis.
The measure, named category 1 authorized use products, covers steel products that can be made domestically.
But it also allows tariff free imports up to set limits across 20 product categories, including coated sheet, tin mill products, plates, bars, wire rod, sections, pipes, tubes and hollow sections. Each category is defined by specific commodity codes.
Quota volumes will be split evenly across four quarters: July September, October December, January March and April June. Any unused quota in one quarter will roll over into the next, providing additional flexibility for importers managing irregular purchasing patterns or demand fluctuations. But unused quotas will not carry into the following quota year.
For volumes imported outside the quota, a tariff rate of 50% will apply, calculated on the value of the steel before any other import duties.
Quota reviews
The UK government’s Trade Remedies Authority (TRA) announced on March 31 decisions on three tariff-rate quota (TRQ) reviews – pertaining to metallic coated sheets, merchant bars and light sections – which have seen a country-specific import quota introduced for Turkish exporters.
In one of the reviews concluded on March 31, three of eight commodity codes were removed from the TRQ in the March 31 decision, with the TRA saying that it found no evidence of UK production during the period of investigation for the goods subject to review in those commodity codes.
Regarding category 4 steel imports into the UK from Turkey, comprising metallic sheets, the TRA stripped Turkey of its Developing Country Exception status, instead choosing to impose a country-specific import quota, saying that imports of metallic sheets from the region in 2025 exceeded 3% of the total imports of that product.
The ruling came despite pleas from contributors to the review including Turkish exporters TatMetal and Tezcan Galvaniz, which said in their submissions that the TRA should assess whether any apparent increase in imports is sustained and structural, and should avoid placing undue weight on short-term spikes or other temporary market factors.
Turkish exporters TatMetal and Borçelik Çelik Sanayi Ticaret both also argued for Turkey to retain its DCE status.
The UK imported 67,848 tonnes of metallic coated sheet from Turkey in 2025, which was 7.09% of total imports, above the 3% threshold needed for an exemption, but approximately 54,000 tonnes of metallic coated sheet was imported in just the final quarter of 2025, according to HMRC Country of Origin import data.
Imports from developing countries are given exceptions to TRQs if the goods imported make up less than 3% of the total imports of that product and if, collectively, these low-volume exporters account for no more than 9% of the total imports of that product.
The consequences of all three TRQ reviews were to come into effect on April 1, the TRA announced.

The US cancels antidumping investigation into cold-drawn mechanical tube imports from Switzerland


EU steel import safeguard measures updated

The new quota period in the EU has started
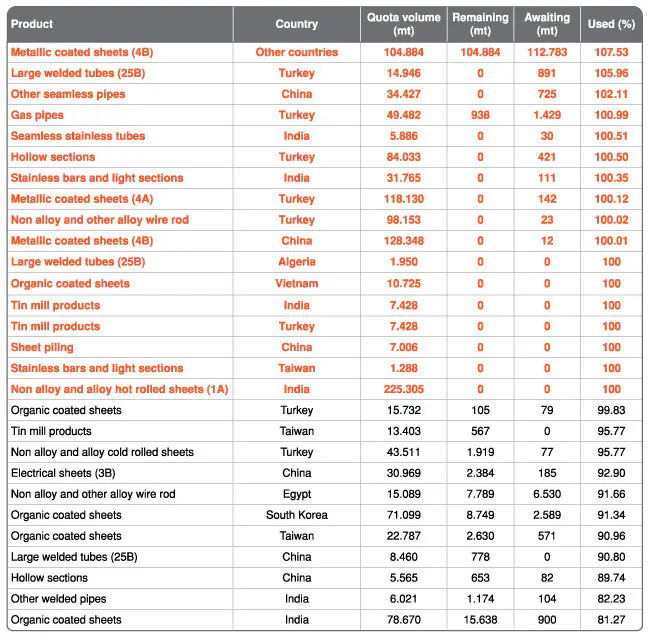
The new quota period in the EU has started as of April 1.
Although the volumes awaiting at the ports are not cleared through customs yet, given the high volumes of imports waiting at the ports, for some products, the quota volumes have already been exhausted.
In the table below, you can see the products for which quotas have already been exhausted and also those for which more than 80 percent of quotas have been used up.
Author: SteelOrbis Editorial Team


EU flat steel TRQs near exhaustion early in Q2; long steel uptake slower
Flat steel
In the flat steel segment, quota utilization has been relatively strong in key categories, with several origins approaching full allocation shortly after the start of the quarter.
For hot-rolled coil, India and Turkey remained the most “popular” origins.
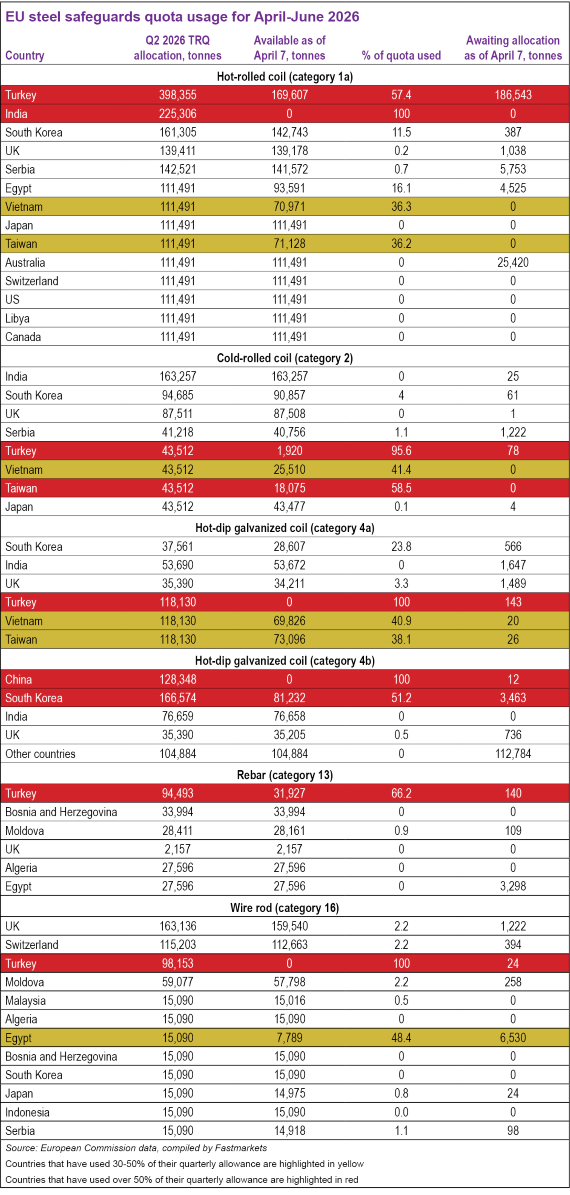
Notably, India has fully exhausted its allocation for HRC for the second quarter of 2026, just a couple of days after it was renewed. It is worth noting that, as of April 1, indicative HRC volumes awaiting allocation for India stood at 304,826 tonnes, exceeding the available duty-free quota of 225,306 tonnes. By Tuesday April 7, the quota had been fully exhausted, with no tonnages remaining awaiting allocation, European Commission customs data showed.
Market participants noted that a portion of these volumes reflects carry-over demand from the previous quarter, combined with continued preference for duty-free material.
Turkey has used over 50% of its 398,355 tonne allocation for the period, with tonnages awaiting allocation indicating that the quota will be fully utilized within days as well [see table].
Sources said, that buyers were rushing second-quarter bookings ahead of imminent implementations of new safeguards as of July 1. The EU implemented provisional steel safeguard measures in July 2018, followed by definitive measures in February 2019. The new system, expected to replace existing safeguards, will come into effect as of July 1 and are expected to include a large cut in import quotas (about 50%) and a higher “out of quota” duty (50% instead of 25%).
“We don’t know the size of country-specific quotas, so everyone who needs to import [is trying] to buy as much as possible with delivery in Q2,” a buyer in Italy said.
In downstream products, including cold-rolled coil and hot-dipped galvanized coil, quota usage has also been uneven.
Europe’s CRC market has historically relied heavily on imported material, particularly for standard commodity grades. But recent regulatory changes have significantly narrowed sourcing options. In particular, an ongoing anti-dumping probe covering CRC shipments from India, Japan, Taiwan, Turkey and Vietnam — which together account for roughly two-thirds of the EU’s total CRC import volume — has materially reduced the availability of foreign supply.
Despite the ongoing anti-dumping investigation for CRC, three out of five targeted countries — Turkey, Vietnam and Taiwan — have used up large portions of their allocations as of April 7.
“We take the risk [of importing coil] to diversify supply sources. Plus, new safeguards will come into force in July — so it is best to import coil before that, because the new regime suggests a 50% imports cut,” a buyer in Germany said.
For HDG, certain origins have seen rapid take-up, while others still have notable balances available or pending allocation.
Sources said this divergence reflects shifting trade flows and continued uncertainty linked to the EU’s Carbon Border Adjustment Mechanism (CBAM), which has complicated import planning.
“Some quotas are moving quickly, but others are barely touched because buyers are still cautious on CBAM costs,” a trader in Northern Europe said. “Besides, lead times are stretching, and new war in the Middle East send Asia-origin cargoes around the Cape of Good Hope, which adds 2 more weeks to lead times.”
Disruptions to new import flows have lent support to a bullish trend in the domestic market, despite end-user demand seen as stable at low levels, Fastmarkets understands.
For example, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €718.25 ($839.37) per tonne on April 7, down by €0.51 per tonne from €718.76 per tonne on April 2.
The Northern Europe index was up by €6.75 per tonne week on week and up by €18.25 per tonne month on month.
European mills were largely sold out for second-quarter delivery HRC, with only limited tonnages for June lead times left. For example, in Germany and the Benelux area, offers for July shipment HRC were reported at higher levels of €750-760 per tonne ex-works. In contrast, in the second half of March, deals for June-delivery coil in Northern Europe were heard at €700-730 per tonne ex-works.
Long steel
In contrast, uptake in the long steel segment has generally lagged behind that of flat steel.
Although some activity has been recorded in rebar and wire rod quotas, with Turkey leading the uptake in both categories, significant volumes are yet to be utilized across multiple origins.
Market participants said that this slower pace is consistent with recent trends, where buyers have increasingly relied on domestic supply rather than imports.
“There is no urgency to book imports in longs at the moment,” a distributor said. “People prefer local material, especially with the uncertainty around additional CBAM costs.”
Fastmarkets’ price assessment for steel reinforcing bar (rebar) domestic, delivered Northern Europe averaged €635.63 per tonne at the midpoint in March, versus an average of €623.75 per tonne in February.
The corresponding weekly price assessment for steel wire rod (mesh quality) domestic, delivered Northern Europe averaged €621.25 per tonne at the midpoint in March, versus an average of €597.50 per tonne in February.
Local prices in Europe have been on an upward trajectory in recent months, driven by higher production costs — for scrap, electricity and transportation. Coupled with tighter imports due to the implementation of CBAM and upcoming safeguards, this creates the room for further increases.
Author: Julia Bolotova, Vlada Novokreshchenova
