


European steel HRC market quiet amid summer closures
Fastmarkets’ daily steel HRC index, domestic, exw Northern Europe, was calculated at €654.92 ($721.34) per tonne on Monday, down by €1.08 per tonne from €656.00 per tonne on July 28.
The latest calculation of the Northern European index was down by €0.91 per tonne week on week and by €19.18 per tonne month on month.
Market participants were largely absent from trading, resulting in seasonally slow activity.
“[The market] is dead at the moment,” a trading source said.
Some sources forecast that there would be a pick-up in demand by September and said that mills could look to achieve price rises before the autumn.
During the week to July 28, one mill in Germany expected to achieve €700 per tonne ex-works for November-rolling HRC, according to market sources. It remained uncertain whether this price would be achieved.
Offer prices of HRC were in the range of €660-680 per tonne ex-works, while buyers’ estimates of tradeable prices were still being reported at €650-660 per tonne ex-works.
Meanwhile, Fastmarkets calculated its daily steel HRC index, domestic, exw Italy, at €635.00 per tonne on Monday, down by €9.58 per tonne from €644.58 per tonne on Friday.
The Italian index was down by €10 per tonne week on week and down by €15 per tonne month on month.
Trading in the Italian market was almost nonexistent, but this was typical during the summer-holiday period.
Buyers reported tradeable prices for September-October-delivery HRC at €630-640 per tonne ex-works on Monday.
“Market activity is completely dead,” the first trading source said, “especially in Italy because of the summer holidays.”
Published by: India-Inés Levy


Steel rebar, wire rod prices stable in Poland; mills hope for post-summer recovery
Rebar offers from three local producers were broadly stable week-on-week.
One mill was hoping to get 2,640 zloty ($660) per tonne ex-works. Another producer was quoting rebar for the local market at 2,660 zloty per tonne CPT, roughly equivalent to 2,630-2,640 zloty per tonne ex-works. A third producer was hoping to get 2,680 zloty per tonne CPT, about 2,650-2,660 zloty per tonne ex-works.
Rare transactions were reported within the range of 2,600-2,650 zloty per tonne ex-works during the week. Mills in the region were able to offer rebar from stock with quick shipment, market sources said.
“As usual during summer vacations, demand [for rebar] is rather weak, but mills are reluctant to cut prices to less than 2,600 zloty [per tonne ex-works],” a trading source said.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, exw Poland, was 2,600-2,650 zloty per tonne on Friday, stable week on week.
In the secondary market, rebar prices were reported at 2,750 zloty per tonne CPT, compared with 2,750-2,800 zloty per tonne CPT in the preceding week.
Current prices were expected to be maintained over the next 2-3 weeks amid the traditional summer trading lull. In September, however, market sources expected to see a rebound in demand from the construction industry.
“Everyone is hoping for better demand in September,” a second source said. “There are many projects waiting for building permits.” This was because the Polish government was offering subsidies to people purchasing their first apartments, so there was not enough housing stock on offer at the moment.
Wire rod
The wire rod market has also been quiet recently, with prices said to be stabilizing.
Official offers of low-carbon drawing-quality wire rod issued by local steelmakers were reported at 2,800-2,900 zloty per tonne CPT this week, although the upper end of that range was deemed unworkable by most buyers.
In fact, sources reported that one local mill was actually selling wire rod at lower prices of 2,750-2,760 zloty per tonne CPT.
One deal for a low tonnage was reported at 2,800 zloty per tonne CPT.
Fastmarkets’ weekly price assessment for steel wire rod (drawing quality), domestic, delivered Poland, was 2,750-2,800 zloty per tonne on Friday, unchanged since July 7.
Import wire rod offers to Poland were also seen as stable over the past seven days.
One Ukrainian supplier was offering mesh-quality wire rod from stock at €610-615 ($674-680) per tonne CPT depending on tonnage, sources said.
Transactions for small lots were heard within the range during the week to Friday.
Another Ukrainian supplier was offering mesh-quality wire rod at €570 per tonne DAP border, which would net back to about €595-600 per tonne CPT.
Both Ukrainian mills were said to have limited allocations for exports, with both citing improved demand for long steel in Ukraine and a priority on domestic sales.
Offers from an Italian mill were reported at €600-610 per tonne CPT for mesh-quality wire rod with August delivery.
And a mill in Moldova was offering drawing-quality wire rod at €620 per tonne CPT, also flat week-on-week.
Published by: Julia Bolotova
Steel HRC prices flat in Europe as holiday lull begins
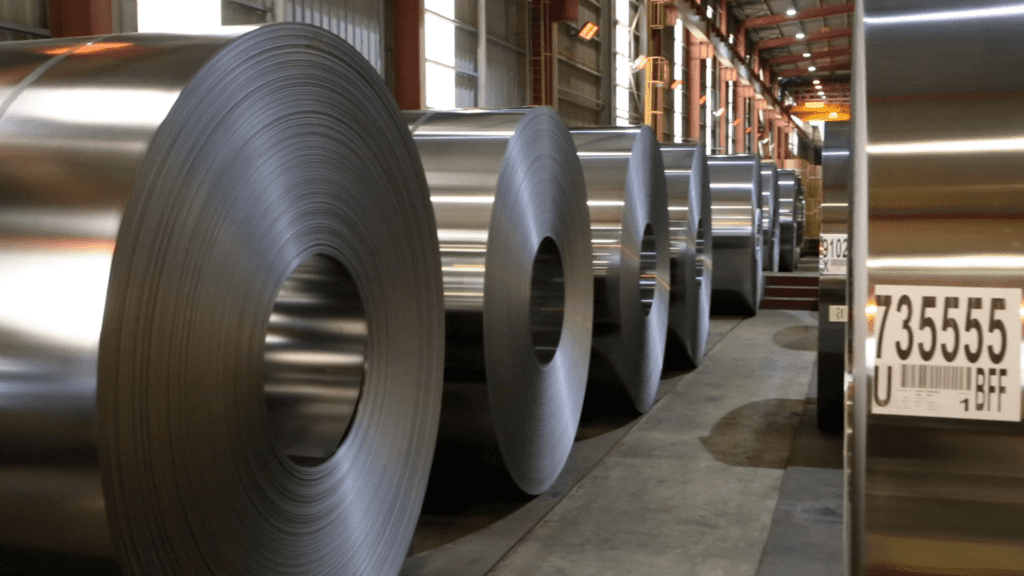
Fastmarkets’ daily steel hot-rolled coil index, domestic, exw Northern Europe, was calculated at €656.00 ($725.12) per tonne on July 28, up by €0.37 per tonne from €655.63 per tonne on July 27.
The latest calculation of the index was down by just €0.25 per tonne week on week, but down by €14.63 per tonne month on month.
Neither mills nor buyers were particularly active in the seasonally slow market.
“Mills offer [HRC] but there’s no hurry to buy, because demand is weak, stocks are more or less at the right level, and import volumes are high,” a trading source said.
One producer in Germany was hoping to achieve €700 per tonne ex-works for November-rolling HRC, but no deals at that price have been heard yet, market sources said.
In general, there were only a few producers active in the market, with September-October delivery HRC on offer at €660-680 per tonne ex-works, while buyer estimates of the tradable value were closer to €650-660 per tonne ex-works.
“Prices have been flat for several weeks and will stabilize [after the] summer holidays,” a second trader in the region said.
As for the post-holiday outlook, there was cautious optimism that apparent demand for HRC would improve due to restocking, market sources said, although the availability of low-priced imports was likely to decline quickly due to the fast uptake of European Union import quotas.
“There’s a risk the quota volume might be reached and even exceeded, which might make imports more expensive [and reduce] pressure on the domestic market,” a distributor said.
Fastmarkets calculated its daily steel hot-rolled coil index, domestic, exw Italy, at €644.58 per tonne on July 28, up by €1.25 per tonne from €643.33 per tonne on July 27.
The Italian index was up by €6.25 per tonne week on week, but was down by €0.60 per tonne month on month.
Trading in the Italian market was practically non-existent ahead of the normal August holiday stoppages.
Buyers said that the tradable value for September-October delivery HRC was no higher than €640-650 per tonne ex-works on July 27.
An offer for September-delivery HRC from a re-roller was heard at €650-660 per tonne ex-works.
And one buyer source said that it was negotiating a booking for October-delivery HRC with an integrated mill in the region at €670 per tonne delivered (equivalent to about €655 per tonne ex-works).
HRC import offers in Italy were also broadly stable, with little buying interest reported despite the competitive offers.
HRC for late September/early October shipment from Vietnam was said to be available at €580 per tonne CFR to Italy.
Taiwan and Japan were offering HRC with the same shipment dates at a slightly higher price of €600-610 per tonne CFR.
Published by: Julia Bolotova

German construction crashes after boom years
Germany’s construction industry appears to be suffering even more than in neighbouring countries, amid an overall slowing economy in Europe. However, the current performance must be viewed against the boom that had prevailed for years, which makes the fall even harder.
“For years, construction flourished more than was healthy, and production capacities were massively expanded with investment in machinery,” a manager of a rebar distribution group says. Consequently, suppliers of material now have big problems filling those capacities.
“The benders are vying for orders, and are undercutting one another with prices for jobs,” he tells Kallanish, noting that pricing has become totally unrealistic. He adds this is a problem that no bender would like to admit. “If you ask them, it’s never themselves, they always keep pointing at others,” he says. “I’ve heard that all too often.”
“It is a drama,” a manager at another big company concurs. “It’s really obscene when you see benders selling their processed rebar at below the purchasing price; they work for nothing, and concede losses.” He adds that he does not believe in a major rebound after the summer break, or for the rest of the year for that matter.
He thus echoes Feralpi chief executive Giuseppe Pasini who last week stated that the market for long products, particularly in Italy and Germany, is not sending signals for a rebound in September.
Christian Koehl Germany


Vallourec anticipates positive second half
French pipemaker Vallourec says it sees US pricing stabilising in the second half of the year at “healthy levels” and market headwinds slowing.
A decline in tube prices and profitability due to lower sales volumes should be slightly offset by higher international pricing in the third quarter, the company says in its first-half earnings report monitored by Kallanish.
While US prices are forecast to decrease moderately in Q3, sales volumes should bottom as distributor inventories normalise. “Our results in Q2 2023 continued the excellent performance we have produced over the last several quarters. Favourable pricing and solid execution across the Group and especially in the Eastern Hemisphere drove robust profitability,” says chief executive Philippe Guillemot.
“US tube pricing has been on a downward trend, though it remains at healthy levels … Outside of the US, demand for our tubular products remains strong, and pricing has continued to show an upward trend. We are capitalising on this via our premium production hubs in Brazil and Asia, while continuing to wind down our tube production activities in Germany,” he adds.
The company’s Brazilian capacity increase is underway and is expected to be completed in 2024. The closure of sites in Europe is slightly ahead of schedule. Vallourec expects German tube production operations to cease in Q4.
Consolidated H1 revenue was €2.6 billion ($2.8 billion), up 31% year-on-year thanks to stable sales volumes, positive price/mix effect, improved Mine and Forest division performance and the euro-dollar currency effect. Ebitda increased notably, reaching €694m compared to €205m in H1 2022. This reflects increasing margins.
Overall, the company registered a positive performance in the global Oil & Gas market in terms of prices and volumes and a recovery in iron ore volumes. For the first half, tube revenue was up 27% y-o-y due to higher pricing.
H1 gross capital expenditure stood at €119 million, up from €59m in H1 2022. Full-year 2023 gross capex is expected to be around €220m, including approximately €70m related to the transfer of Oil & Gas volumes from Germany to Brazil.
Natalia Capra France
Factors combine to finally halt EU construction: Eurofer
The sustained increase in construction material prices, coupled with labour shortages in certain EU countries and growing economic uncertainty, has finally impacted the positive trend in construction output observed since the fourth quarter of 2020, says Eurofer.
In Q4 2022, EU output recorded its first decline since then, by 0.1%, while it was nearly flat, at 0.1% growth, in Q1 2023.
Gross fixed investment in construction dropped in Q1 by 0.4% on-year after eight consecutive quarterly increases. However, two out of the last three quarter-on-quarter developments showed a clear slowdown in construction investment, signalling that activity in the sector has lost ground, the European steelmakers’ association notes in a report seen by Kallanish.
Q2 growth was driven mainly by “other construction” investment, particularly in civil engineering. Its expansion is projected to continue during 2023, but at a much slow pace due to lower public expenditure in construction. As expected, residential investment continued to drop, due to higher mortgage rates resulting from monetary policy tightening by the ECB to curb inflation.
Growth has been supported by generous housing and renovation schemes in place in many EU Member States. However, the impact of these is likely to fade due to downside factors including construction material cost and supply shortages.
The EU construction sector is expected to experience a mild recession in 2023, falling 0.5% on-year, and to recover modestly, by 0.7% in 2024, Eurofer says.
“Civil engineering will continue to be supported by EU-wide public policies … but their effects have become increasingly uncertain and difficult to quantify due to the recent deterioration of the economic outlook. The suspension of the Stability and Growth Pact has been extended until the end of 2023, which will leave room for government spending in infrastructure. However, the visible effects in terms of construction output related to these projects will be lagged over time,” the association concludes.
Adam Smith Poland

European stainless flats demand resumes, prices to increase
European stainless steel coil prices have reached rock bottom and will increase in new contracts, sources tell Kallanish. Mills in Europe are pushing prices up by some €50/tonne ($54) for hot and cold rolled coil for September delivery and plan a second step of increases for October delivery.
All steelmakers plan to idle their facilities for longer than usual this year due to poor sales and overcapacity. Because of the stoppages, deliveries of agreed contracts are being delayed.
European stainless flat steel market sentiment is now changing. Some northern European service centres have noticed a demand surge in July, with the return of apparent demand and restocking. This follows a long period of sluggish sales for HRC and its derivatives.
At present, stainless CRC in northern Europe is at €2,230-2,280/t delivered on average and HRC at about €2,100-2,130/t delivered. Scrap prices in Europe have also recovered this month by around €50/t, due also to extreme shortages, after prices reached unsustainable levels in June.
Natalia Capra France

EU HRC market activity low, negative pressure from import disappears
Domestic prices for hot-rolled coil in Europe remained largely unchanged on July 28, as summer market slowdown started.
Although sentiment has been largely negative, filled safeguard quotas for some Asian countries that had been offering the most competitive prices provided some support to the EU market.
“Vietnam, Taiwan and other ‘other counties’ quota exporters and South Korea have their quotas almost filled [for the third quarter],” a service center said. “And I heard that some volumes would remain in the European ports until the start of the fourth quarter to get custom cleared. So buyers simply do not want to risk and import when they might pay safeguard duties or keep material in ports until start of 2024.”
Offers of HRC from Vietnam have been reported at Eur580/mt CIF Antwerp and from India and Turkey at Eur600-620/mt CIF Antwerp, prices excluded anti-dumping duties if applicable.
In South Europe, import offers of the material from India, Turkey and Japan have been heard at Eur595-620/mt CIF Italy.
Apart from seasonal demand slowdown market participants have been concerned about end-user demand.
“Demand is weak, automotive industry had been performing fine, but outlook is not positive, steel consumption from construction is bad and white goods are also not OK,” a Northwest European service center said.
Some support of the domestic prices might come from production cuts and stoppages for maintenances, but to see any effects from the measures biggest mills need to take steps to reduce output, according to market sources.
Platts assessed domestic prices for hot-rolled coil in Northwest Europe down Eur5/mt on the day to Eur645/mt ex-works Ruhr on July 28.
Market participants estimated tradable values at Eur630-650/mt ex-works Ruhr, with majority of price points reported at Eur650/mt ex-works Ruhr.
Offers have been heard at Eur650/mt ex-works Ruhr and at Eur660/mt delivered Germany.
Platts assessed domestic prices for hot-rolled coil in South Europe unchanged on day at Eur635/mt ex-works Italy on July 28.
The assessment was based on tradable values heard at Eur630-650/mt ex-works Italy.
Platts is part of S&P Global Commodity Insights.
Author: Maria Tanatar

ArcelorMittal to construct new electric arc furnace at Gijon steel plant
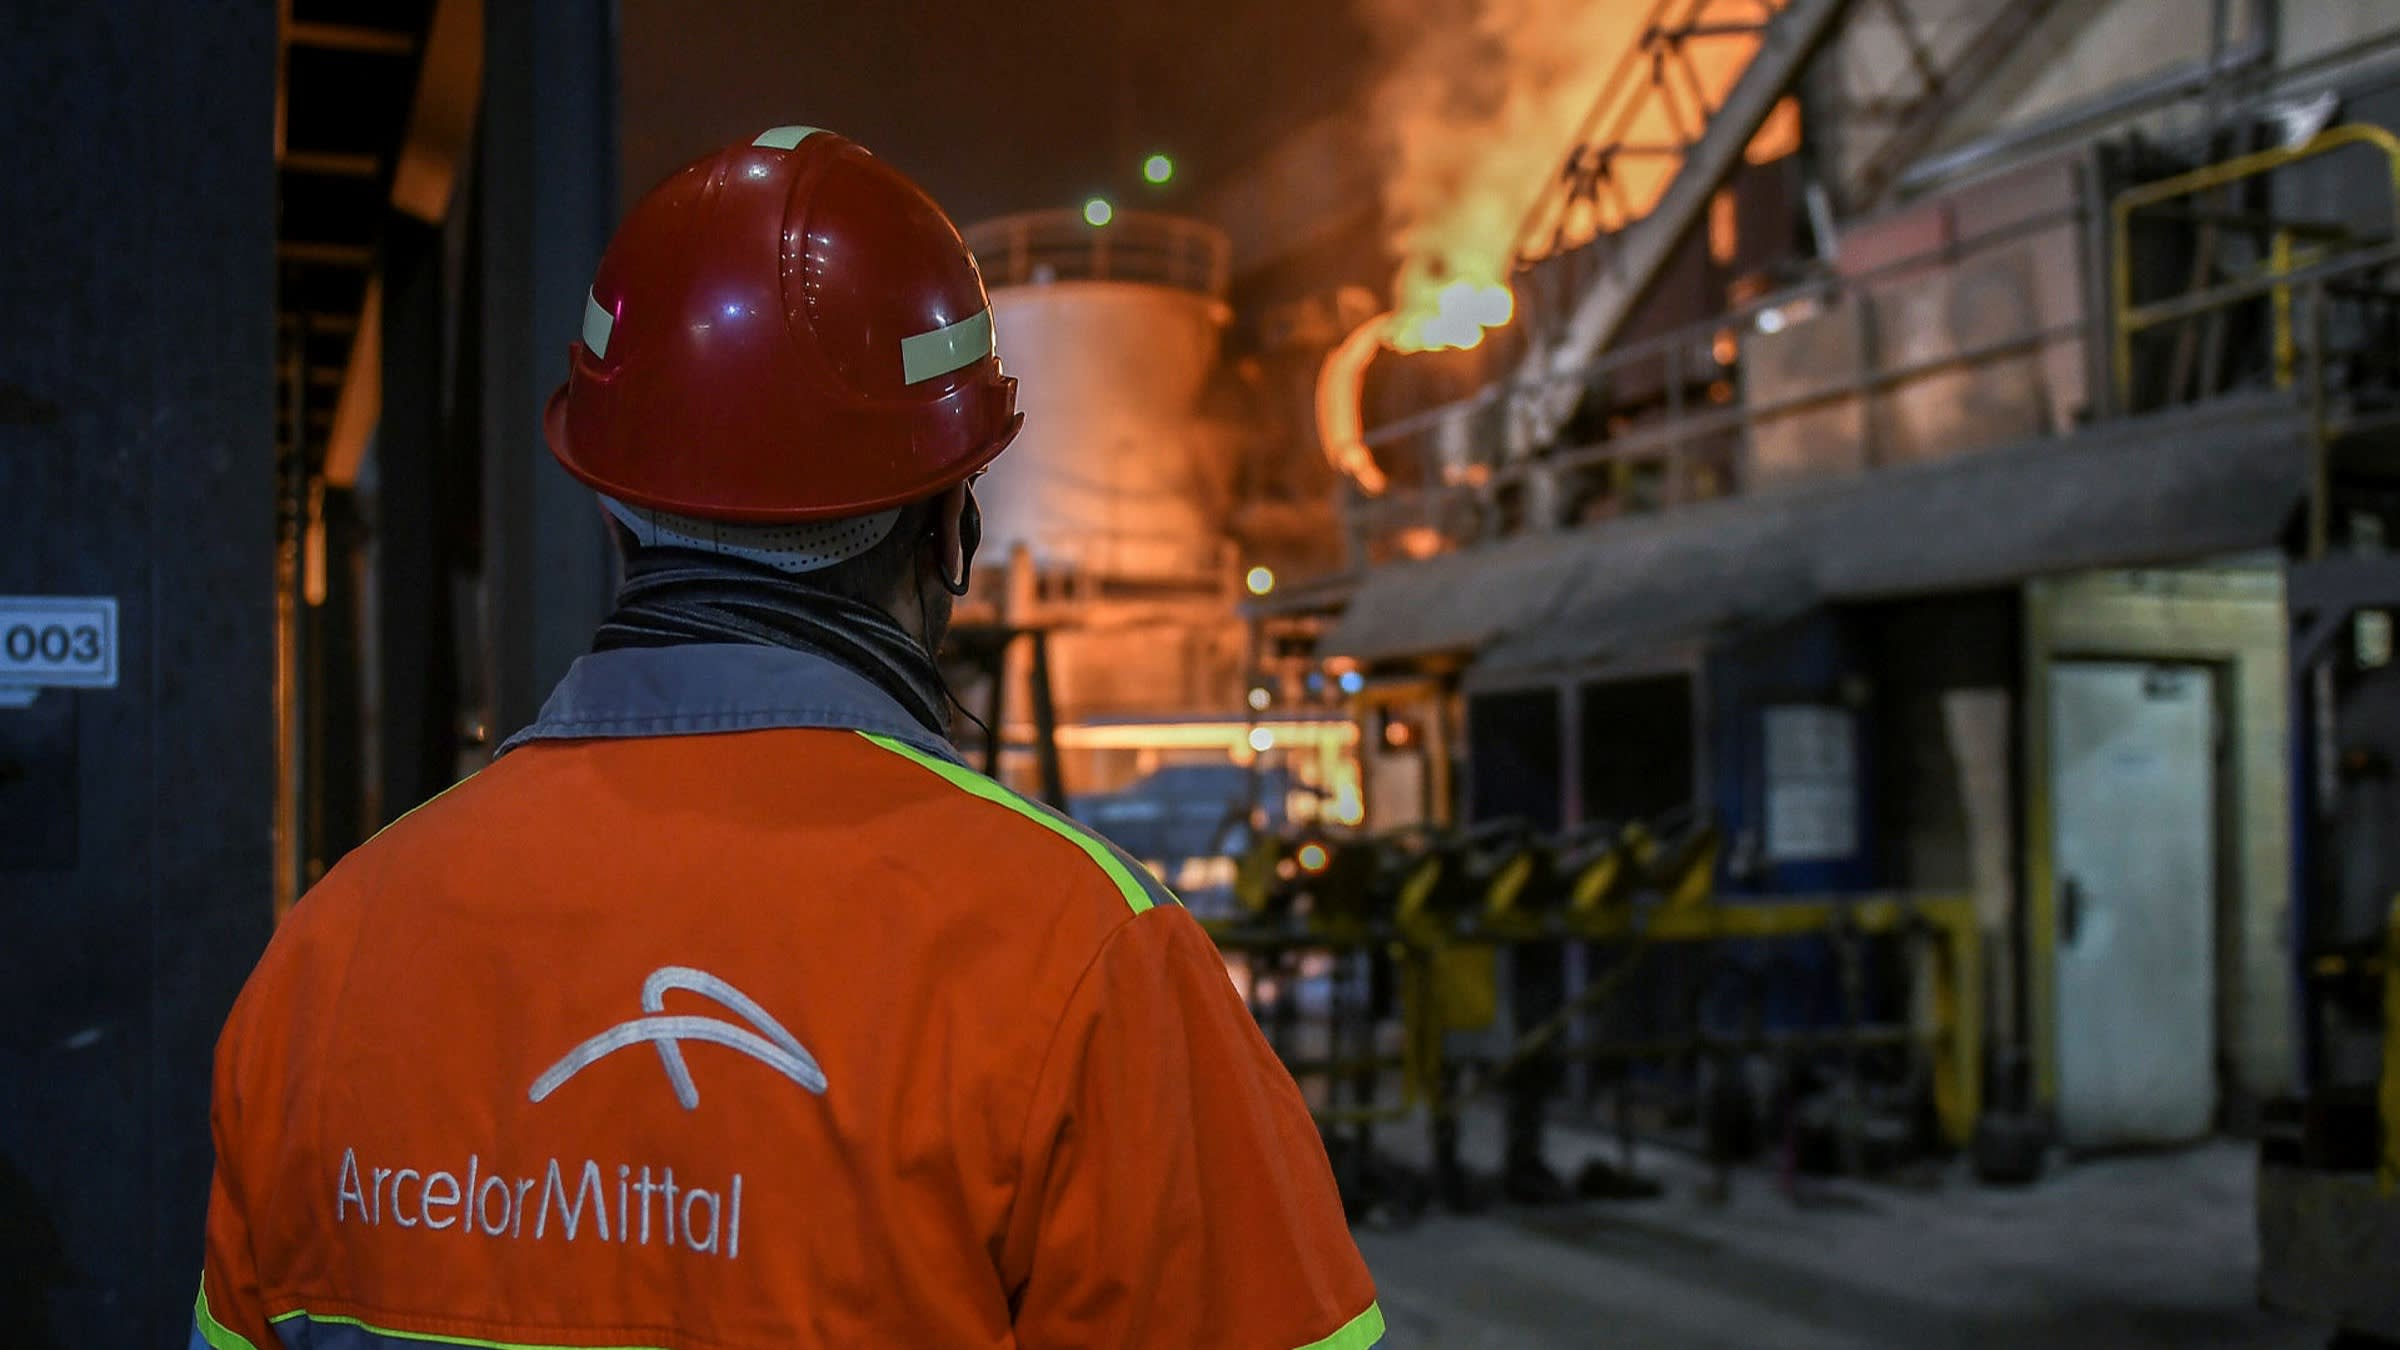
ArcelorMittal will proceed with a project to build a new electric arc furnace at it Gijon site in northern Spain replace one of its two blast furnaces, the company said July 27.
“The pre-FEED (front end engineering and design) part of the project has been completed and the FEED phase will begin,” ArcelorMittal de Espana said in a statement.
The new electric arc furnace (EAF), with 1.1 million mt capacity, is due to come online in the second half of 2025 and will produce increased volume of steel coil and steel rods with reduced carbon emissions.
The project will use hydrogen generated from renewables to decarbonize both the steel production and downstream industries.
This will make the plant competitive in high added value products with stricter environmental criteria for use in the public sector, it said. Spain’s government in April approved funding from Spain’s Recovery and Resilience funds of Eur450 million ($500 million) for ArcelorMittal’s “green steel” project at Gijon.
Overall investment is slated at around Eur1 billion ($1.1 billion) which covers a 2.3 million mt/year hydrogen-fed DRI unit and the hybrid EAF, which will reduce the mill’s CO2 emissions in Spain by 50% (4.8 million mt).
Hot-rolled coil CIF Antwerp was assessed by Platts for S&P Global Commodity Insights at a midpoint $664.96/mt July 27, down 4% from one month prior.
At the start of July, ArcelorMittal restarted its halted furnace at Gijon that had been closed due to a fire in March.
In July 2022, ArcelorMittal announced plans to also convert its 2 million mt/year Sestao, Spain plant to produce zero carbon emissions throughout the productive process, with a target date of 2025.
Gijon would be used to feed Sestao while there is also scope for a new electric furnace at nearby Aviles, which currently has capacity for 4.2 million mt/year of finished steel.
Author: Gianluca Baratti

Mills wind down for summer in Southern European rebar market; wire rod market quiet
Most mills in Southern Europe will stop production in early August until late August-early September, sources said.
Fastmarkets price assessment for steel reinforcing bar (rebar) domestic, exw Italy was €660-675 ($730-747) per tonne on Wednesday, down by €10 per tonne by €670-685 per tonne on July 19.
Market participants in Italy said they expect demand and trading to remain slow until the end of the summer holidays.
As a result, prices are also expected to remain flat.
“Demand remains flat in the market as everyone is evidently preparing for summer holidays,” a producer source said.
“Mills have tried to raise prices, but weak demand and an uncertain market has made it impossible,” a trader source said.
“Now there’s still a week and a half of work and after this the summer closures will put the price in stand-by,” he added.
At the same time, prices in the Spanish rebar market were stable.
Fastmarkets’ price assessment for steel reinforcing bar (rebar), domestic, delivered, Spain was €640-650 per tonne on Wednesday, unchanged since July 12.
Mills in the Spanish market were seeking extended production cuts to rebalance the market, given current slow demand, sources told Fastmarkets.
Southern European wire rod
Fastmarkets’ price assessment for steel wire rod (mesh quality), domestic, delivered Southern Europe was €580-600 per tonne on Wednesday, down by €10 per tonne from €590-610 per tonne on July 19.
Demand has remained flat this week, Fastmarkets heard.
Published by: India-Inés Levy