


European Commission assesses Marcegaglia’s Severstal Distribution acquisition plan
Marcegaglia plans to acquire Latvia-headquartered Severstal Distribution SIA from Russian steelmaker Severstal, Kallanish notes from a European Commission Directorate-General for Competition notice.
The Italian steel processing group’s Marcegaglia Carbon Steel subsidiary would thereby acquire full control over the Riga-based service centre, as well as its subsidiaries Severstal Distribution Sp.z.o.o. in Poland and Severstal Distribution OOO in Ukraine. The units are active downstream of the supply chain, which includes only the distribution of flat and long products, without any activity in production, points out the EU’s competition authority, which is assessing the potential acquisition.
Since the outbreak of war in Ukraine and consequent EU sanctions against Russia, it has become challenging for Severstal to continue operating its European subsidiary. Severstal said 12 months ago it was seeking to keep the Latvian unit running but this would be possible only for another two months due to EU sanctions on Severstal’s majority shareholder. The unit’s 2021 revenue amounted to €1.53 billion ($1.63 billion).
The Polish arm of Severstal Distribution was sanctioned by the Polish government last April to effectively prohibit cooperation with its parent. The Polish government said over PLN 2 billion ($451.8 million) was transferred from the Polish unit to the Russian parent in 2021.
Italian re-roller Marcegaglia has been busy in the acquisition market recently, completing the takeover in January of the majority of Outokumpu’s long products division (see Kallanish passim).
Adam Smith Poland

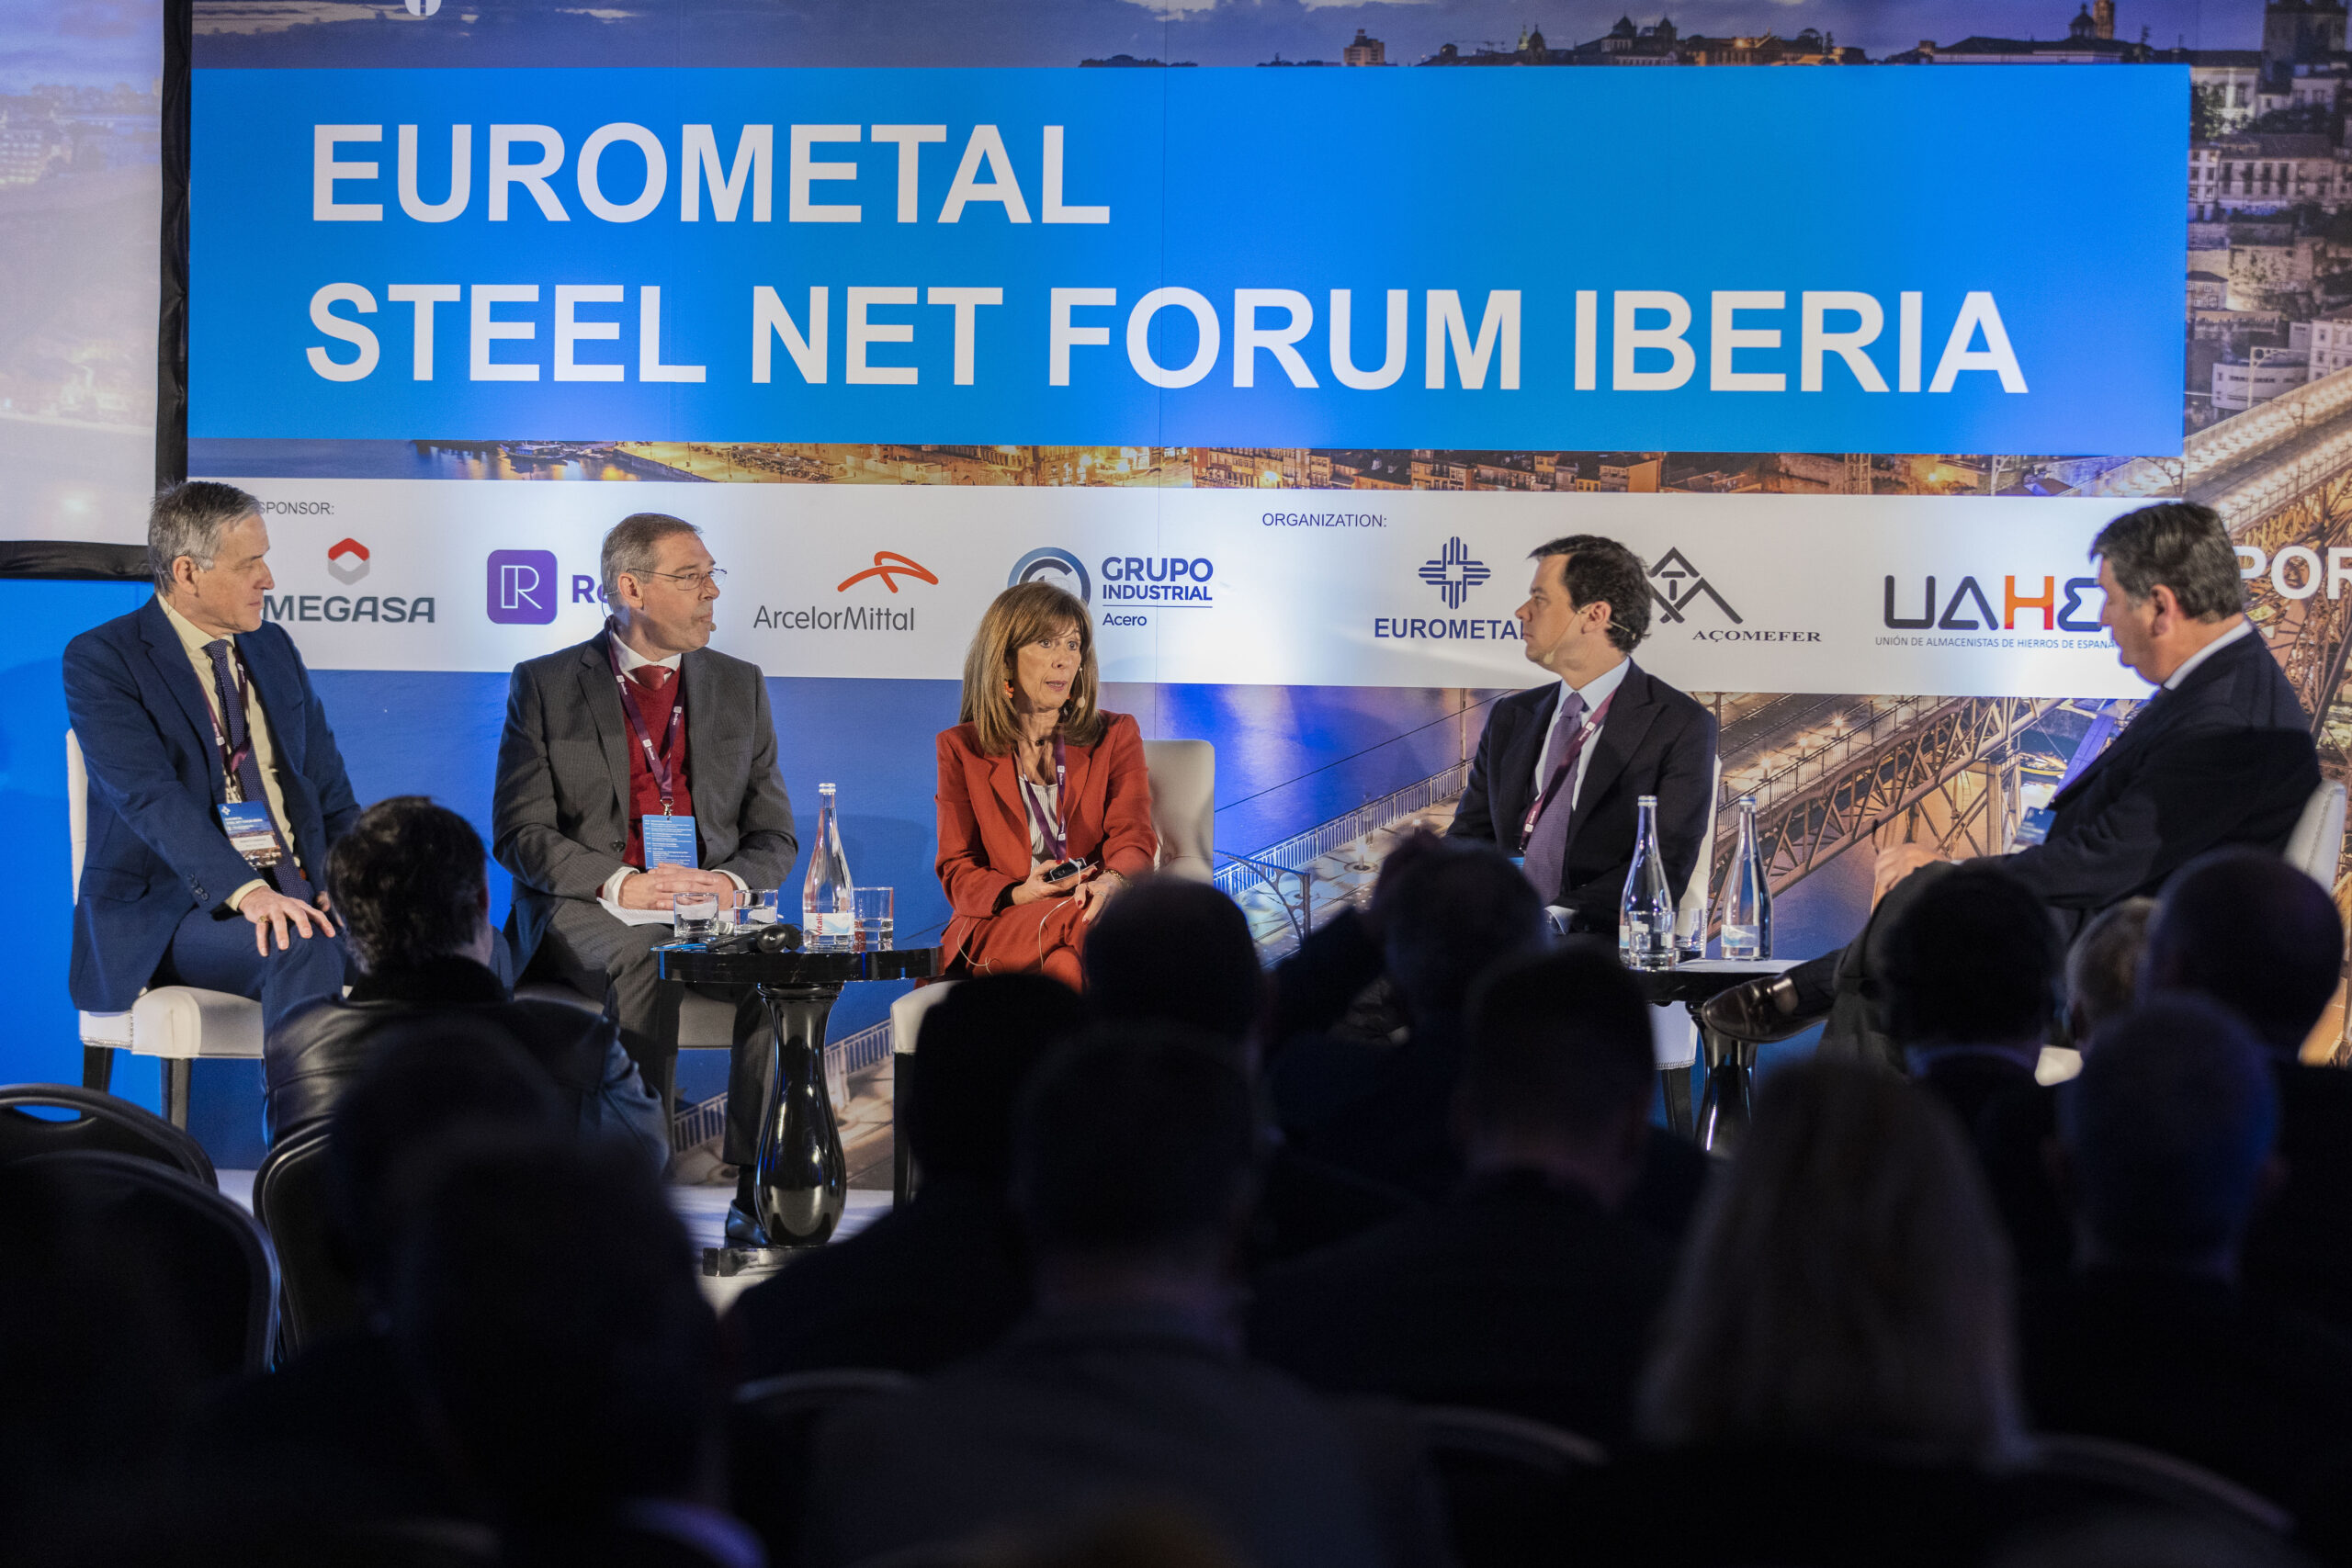
Iberian steel stockists expect prices to remain elevated amid ongoing market uncertainty
Spanish and Portuguese steel distributors expect steel prices to remain at elevated levels for the duration of 2023 amid ongoing economic uncertainty and high inflation.
Speaking at the EUROMETAL Steel Net Forum Iberia in Porto on March 17, a panel of executives from prominent steel distributors gave their thoughts on the challenges facing the industry going forward.
The war in Ukraine, the energy crisis, supply chain disruption and high inflation had contributed to sharp price variations seen throughout the course of 2022, said Paula Correia Dos Santos, chair of Portuguese steel stockist J. Soares Correia – Armazéns de Ferro.
She predicted that the current elevated market prices would persist for the near-term owing to higher costs and ongoing supply chain pressures.
In her opinion, Spanish and Portuguese steel distributors are too focused on maximizing sales rather than increasing efficiency across their business.
“The industry needs to think about cost reduction and strengthening gross margins while increasing awareness of the process services we provide,” she said.
She added that distributors should also improve their understanding of the price structure upstream.
“We should all be aware of upstream costs and ensure that our prices are sensitive to the market,” she added.
Manuel Nobre, who is president of the Portuguese steel association Acomerfer and CEO of Groupo FAF, said that steel distributors must improve their communication when it comes to the value they provide in terms of supporting the execution of projects.
He said that distributors should also improve the value of their service while being resistant to client pressure regarding prices.
“We must avoid analyzing everything at average prices,” he said.
He also said that distributors need to learn to better analyze the signals from the market in order to secure prices that reflect true value.
“Just focusing on margins and tonnage makes no sense,” he said.
— Euan Sadden


Distributors cautiously positive about 2023 steel price outlook: EUROMETAL forum

Iberian steel distributors are cautiously optimistic about the steel sector’s performance in 2023, Fastmarkets heard on the sidelines of EUROMETAL’s Steel Net Forum Iberia in Porto, Portugal, on Friday March 17.
Despite high levels of volatility and looming challenges — including high inflation rates, energy prices and geopolitical risks due to Russia’s war in Ukraine — steel prices are not likely to drop to the low levels seen in 2022 again, market sources told Fastmarkets.
“We might see a downward correction [of HRC prices] in the summer due to seasonal factors, but a nosedive is unlikely,” a distributor told Fastmarkets.
“Volatility will set prices, but old levels are very unlikely,” another source said.
Sources agreed, however, that the recent upticks in flat steel prices have mainly been achieved thanks to limited supply resulting from output cuts in the last months of 2022, rather than a real steel demand rebound.
Fastmarkets’ weekly assessment for steel hot-rolled coil domestic, exw Spain averaged €763.75 per tonne in February, up from a monthly average of €706.25 per tonne in January.
Last year, the European market registered the steepest drop in steel output rates since 2008, sources noted.
Steel output in Iberia totaled 13.3 million tonnes in 2022, down by 17.5% year on year, while flat steel output dropped by 25% and long steel by 14%.
In Spain, ArcelorMittal stopped one blast-furnace (BF) in Gijon in September 2022 amid poor fundamentals. The steelmaker also halted one electric-arc furnace (EAF) in Sestao in August 2022 for scheduled maintenance but delayed restarting operations in September, citing low consumer confidence and rising import levels.
The BF in Gijon has since restarted, but the EAF in Sestao remains idled.
Energy prices lower but still volatile
Energy prices in Spain and Portugal have declined from the record levels reached during last year’s energy crisis, triggered by Russia’s war in Ukraine, but costs still remain high and volatile.
The Spanish government has been regulating electricity prices to ensure stability and affordability; however, average electricity prices in Spain still remain higher than elsewhere in Europe.
Notably, energy prices in Spain were hovering at around €80-90 per megawatt hour (MWh) in mid-March, compared with a record monthly average of €283 per MWh in March last year.
The governments of Spain and Portugal have recently asked the EU to extend a cap on electricity prices, which is currently set to end on May 31, until the end of 2024. In case the so-called “Iberian exception” is not prolonged, the cost of electricity in Spain could surge to about €150 per MWh on average, one source told Fastmarkets.
Raw materials and carbon costs remain elevated
Also supporting upbeat expectations for finished steel prices have been the high costs of raw materials and carbon allowances, sources said.
The carbon permit price in the EU surged above €100 per tonne again on March 10, up from around €70-80 per tonne in March 2022. On March 17, however, the price retreated to around €90 per tonne.
International scrap prices have also been on the rise recently. Notably, Turkish steelmakers have accelerated deep-sea scrap purchases in recent weeks to meet the expected demand for 5 million tonnes of steel for the rebuilding of earthquake-damaged areas. Even though purchasing activity has slowed recently, sentiment in the market remained rather upbeat.
Fastmarkets’ index for steel scrap, HMS 1&2 (80:20 mix), North Europe origin, cfr Turkey averaged at $423.14 per tonne in February, up from a monthly average of $406.59 per tonne in January. The index was most recently calculated at $459.26 per tonne on March 17.
Published by: Julia Bolotova
17 Mar 2023 @ 20:57 UTC


European sections prices, demand to remain strong: EUROMETAL conference

Sharp price volatility in European steel and scrap markets is seen coming to an end in 2023, but pre-pandemic pricing levels are very unlikely to return, according to ArcelorMittal director of commercial profiles in Spain Juan Mañá Herranz. Higher prices will be supported by the international steel market and energy situation.
“The price of sections rose by almost €300/tonne between 2021-22, but at the end of last year fell by €340/t. Levels should be stable, fluctuating by €50-60/t or even a little more in the coming months but would never be so low as they were in 2018,” Herranz said during Friday’s EUROMETAL Steel Net Forum Iberia in Porto.
This price scenario is based on growing demand as well as higher production costs related to raw materials purchases, electricity and gas supplies, he noted at the event attended by Kallanish. According to Herranz, Spain should consume 500,000-515,000 tonnes of sections in 2023, up 4-7% on-year. Portuguese demand will range between 137,000-144,000t, which would be 5-10% more compared to last year.
The Iberian steel industry expects the recovery to continue in 2024, supported by a better economic scenario in the EU, which should be felt from the second half of this year, Herranz concluded.
Todor Kirkov Bulgaria
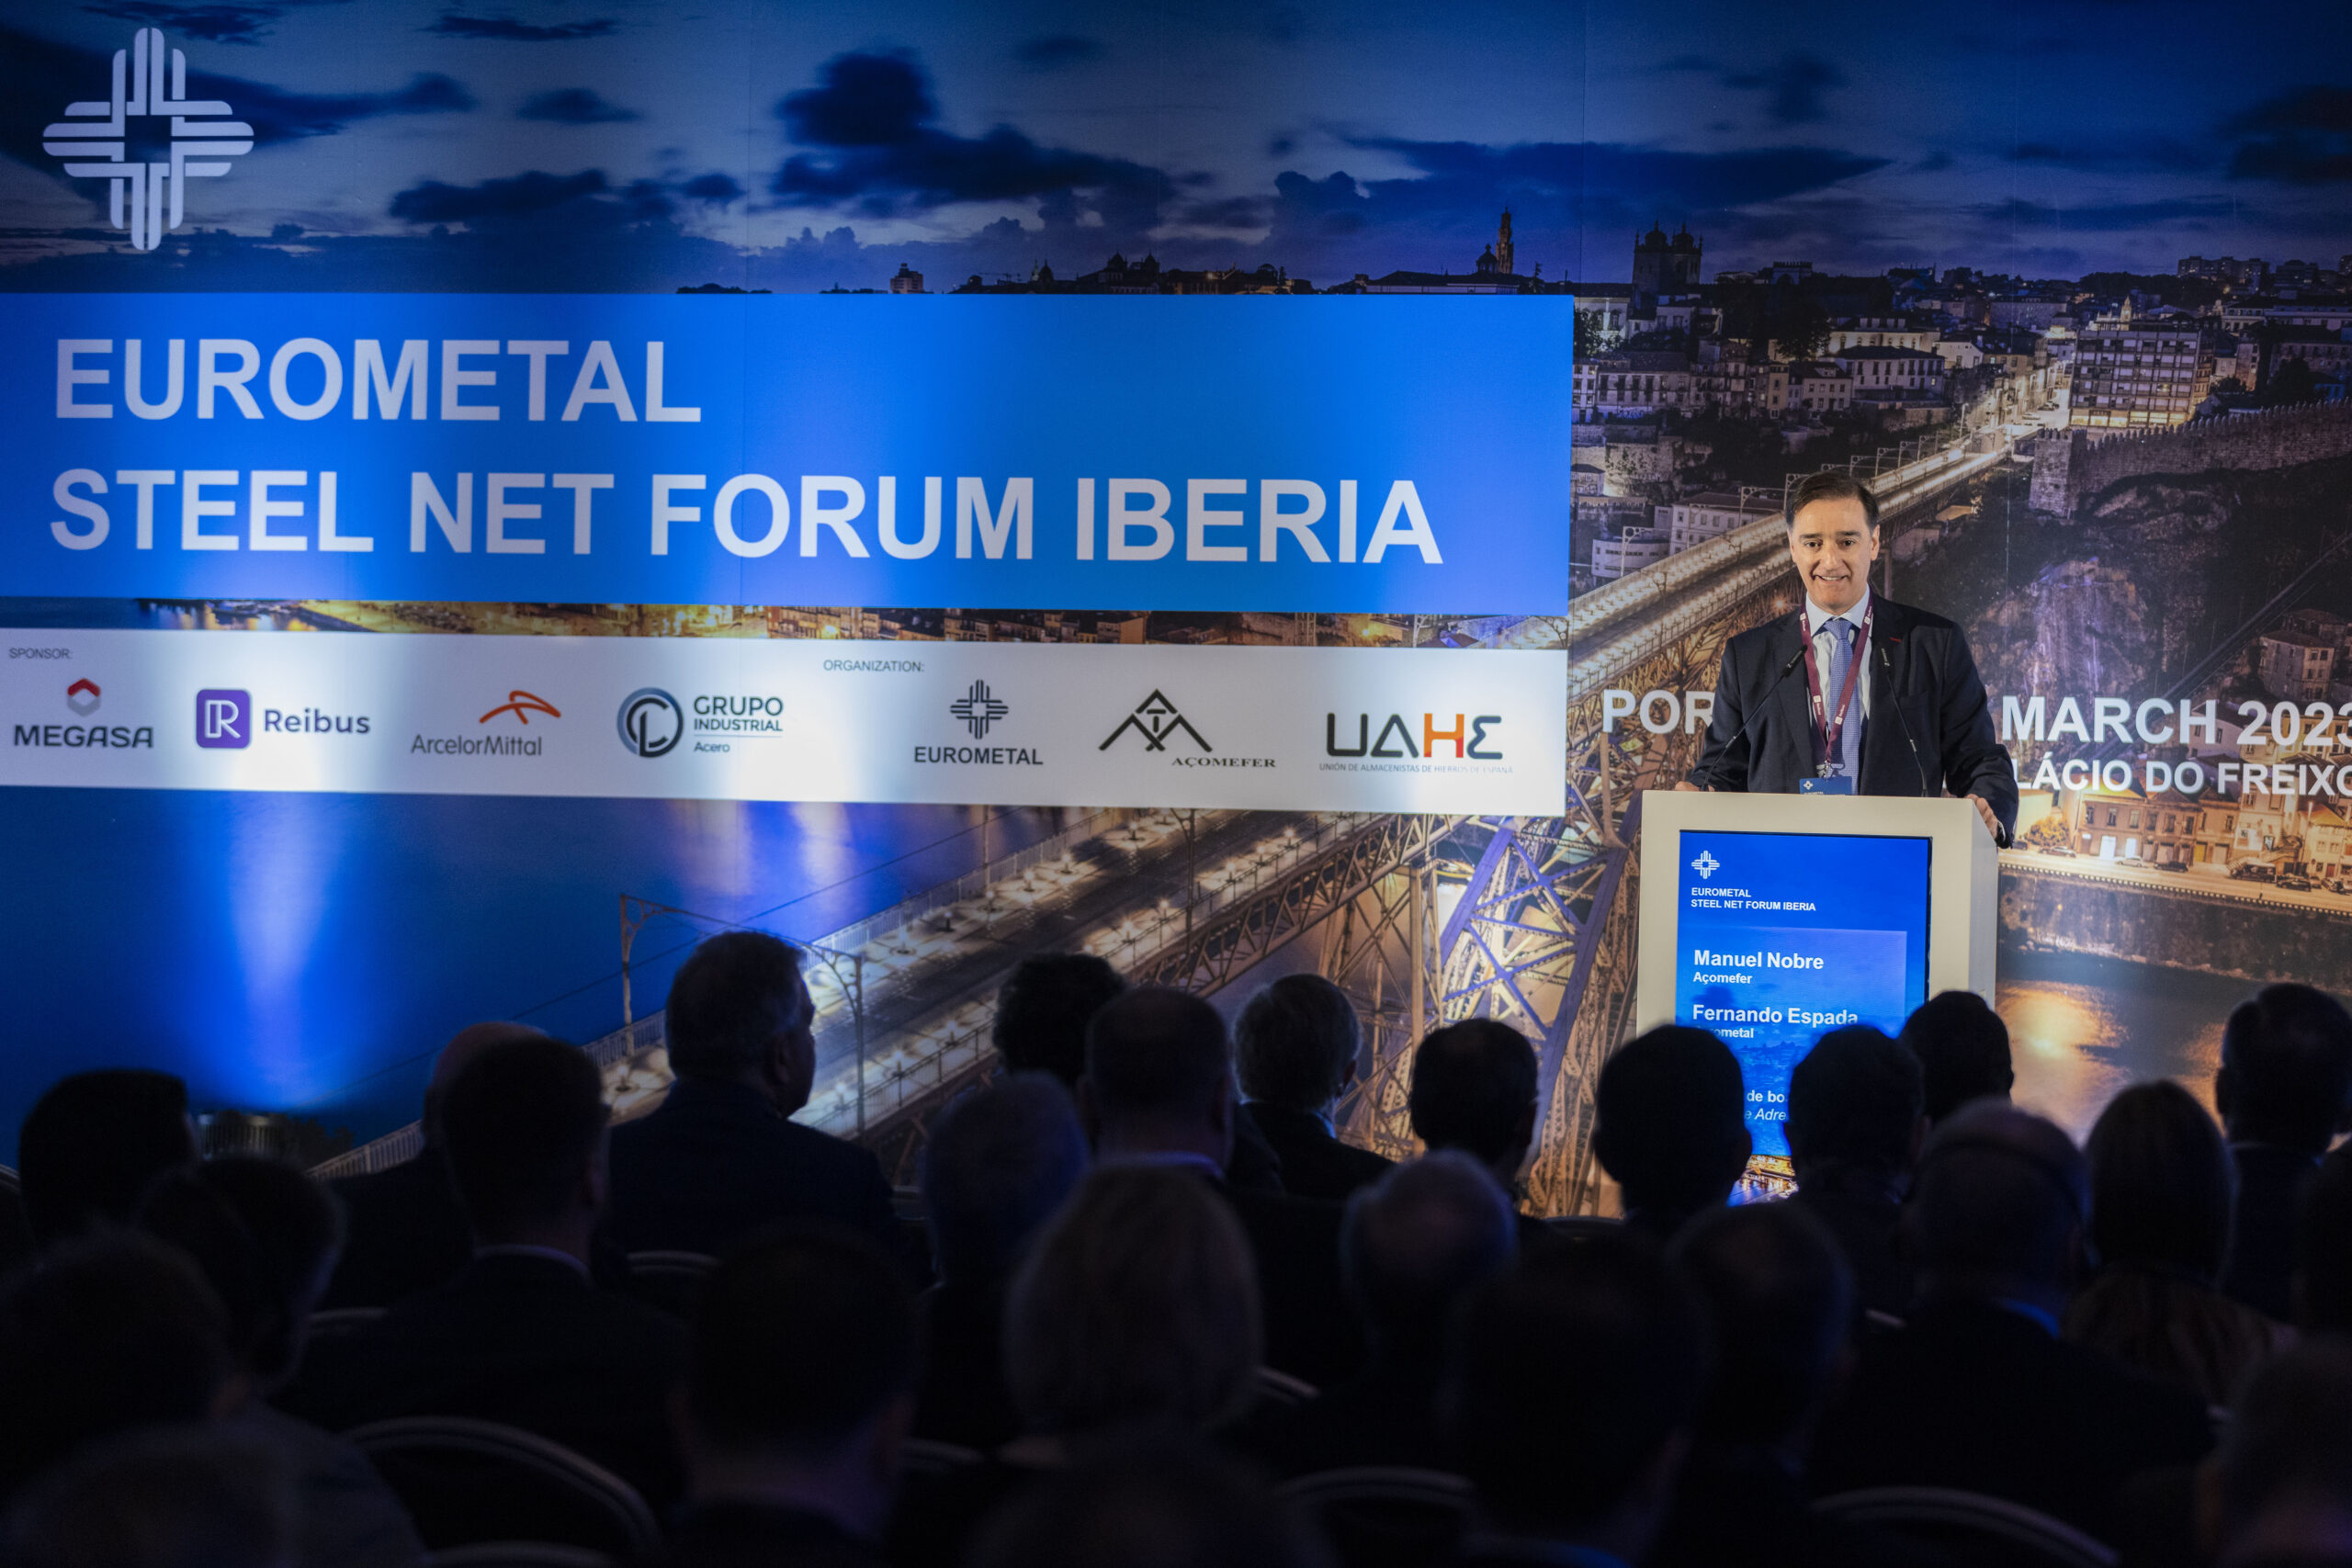
Spanish distributors see challenging scenario in 2023
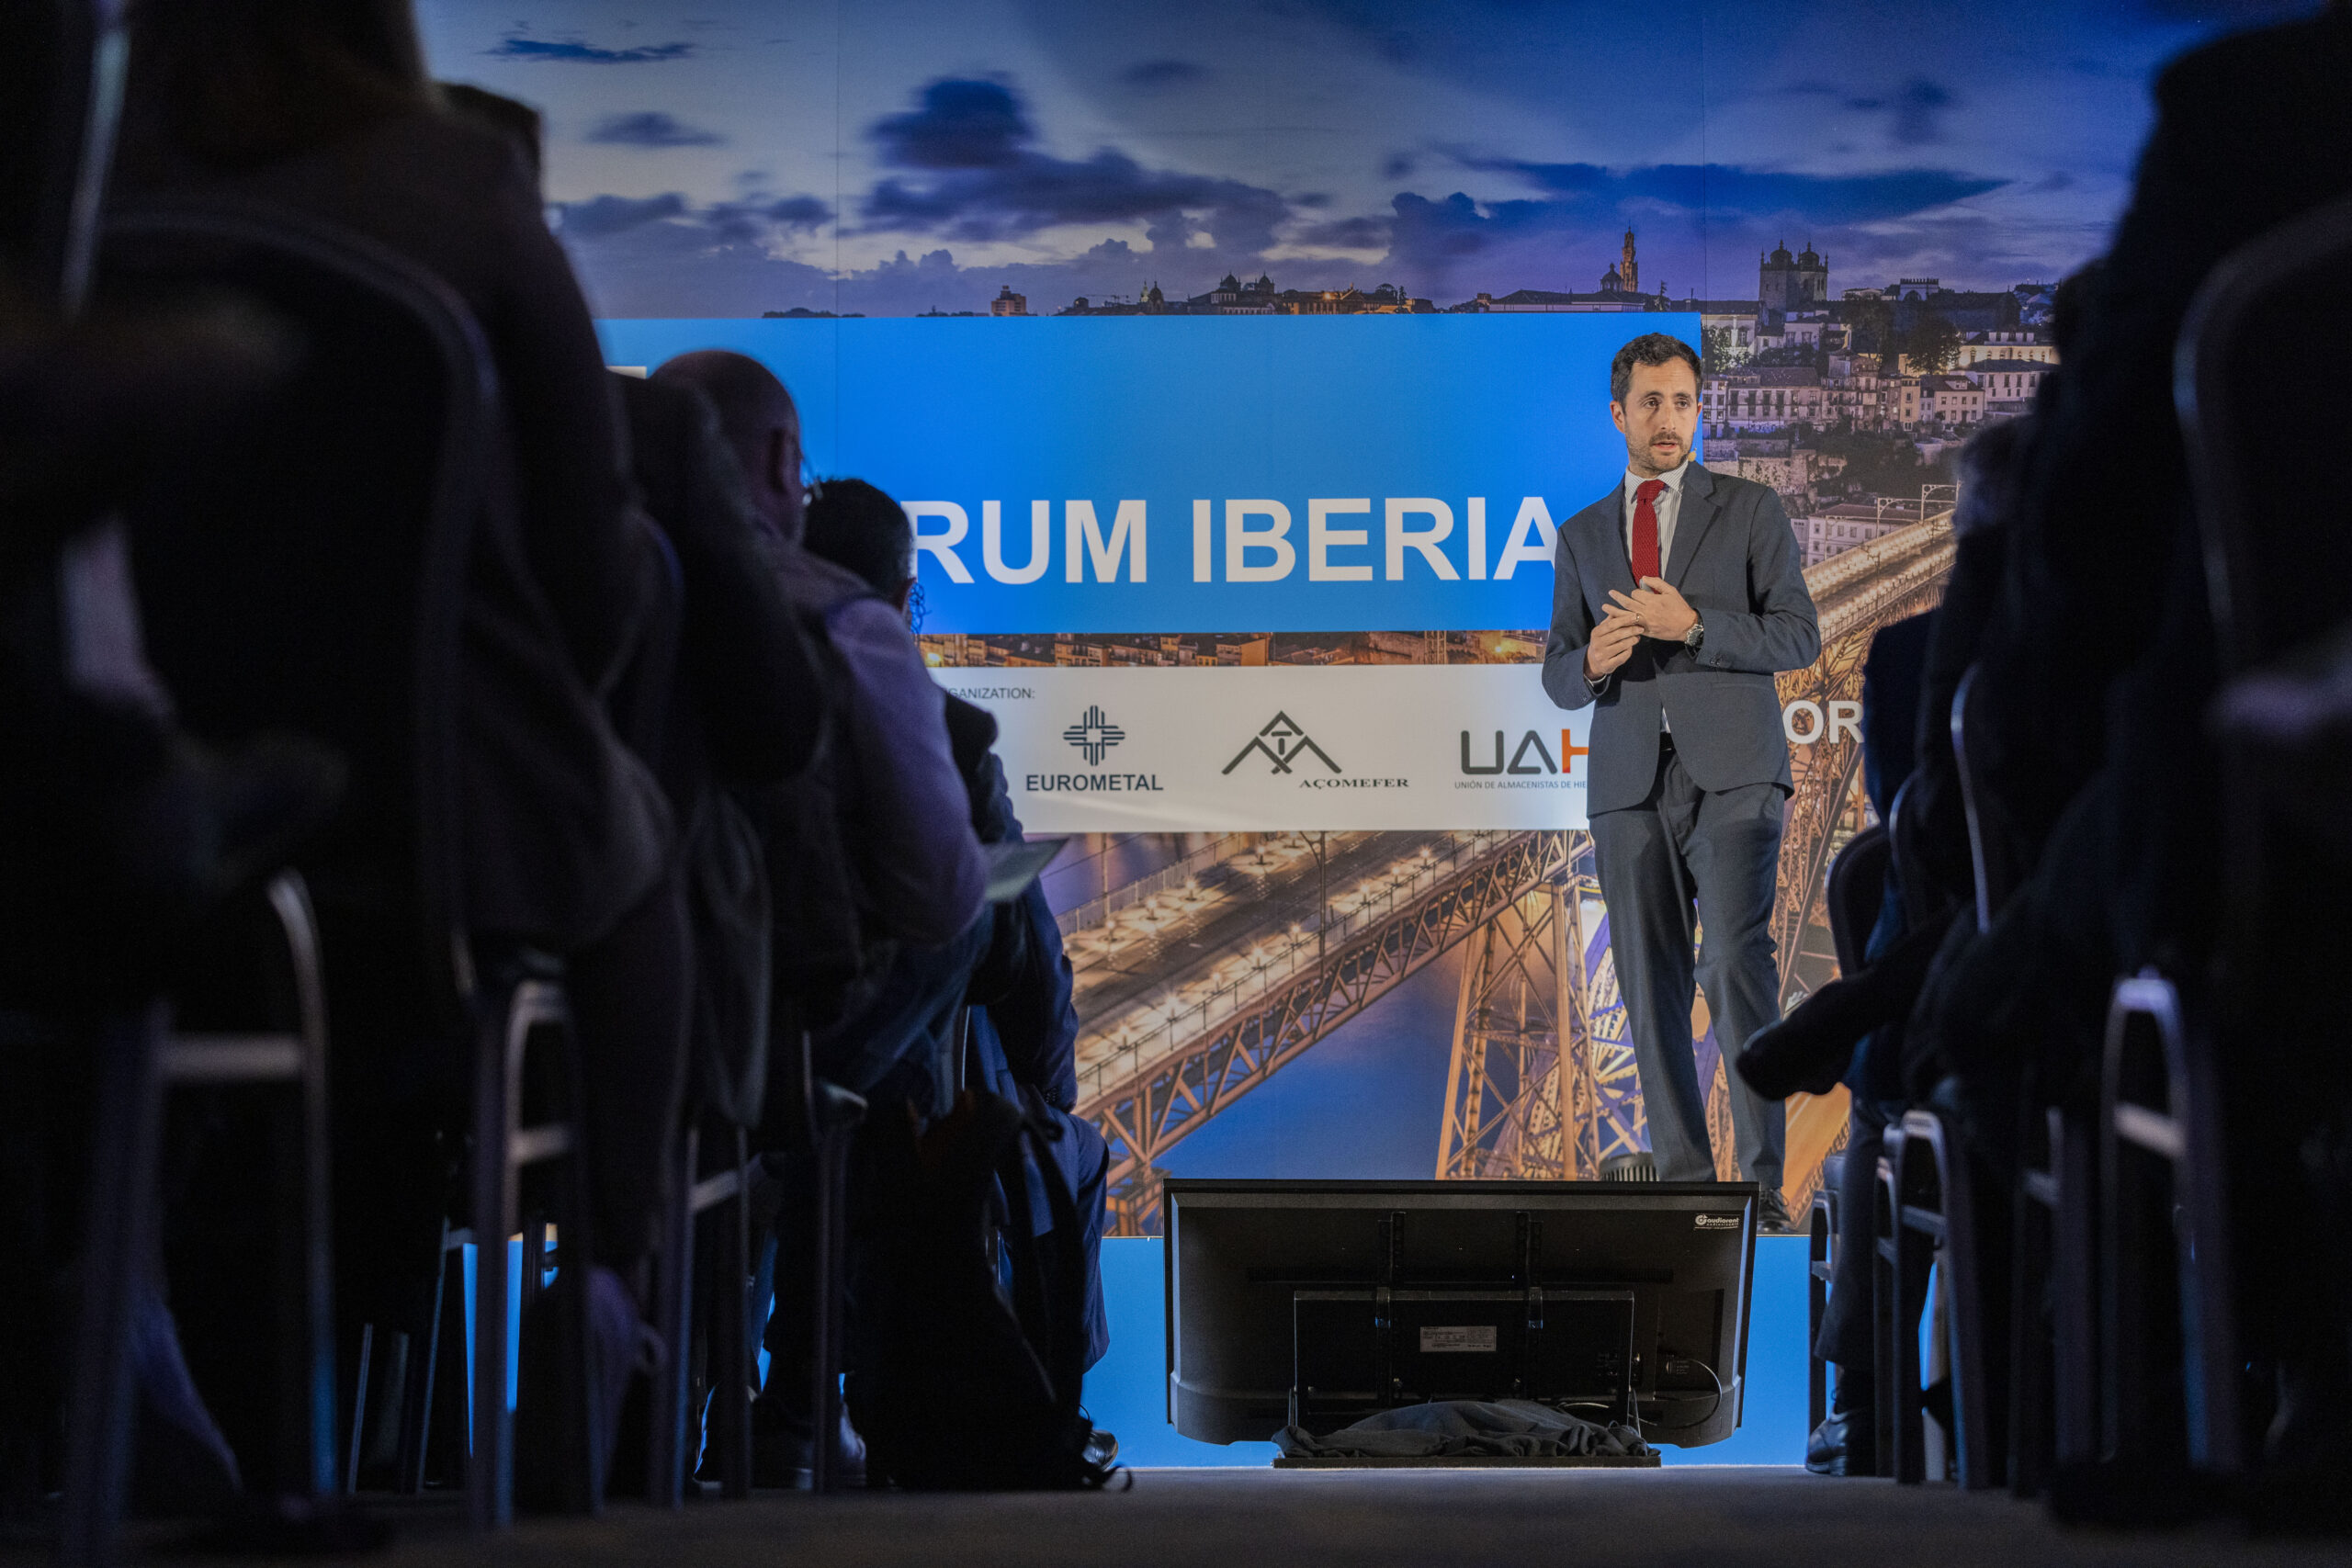
Spanish steel distributor representatives have expressed moderate optimism about the growth of steel consumption. They see short-term growth dependent on factors such as inflationary control, economic growth and the recovery of construction and infrastructure sector demand.
The uncertainty in the automotive sector’s transition towards electrification, as well as high prices of inputs and electricity continue to worry distributors, delegates told Kallanish on the sidelines of the EUROMETAL Steel Net Forum Iberia in Porto last week.
“We see a recovery in the sector, despite challenges resulting from the conflict in Ukraine and supply disruption,” one participant commented. “There was strong demand for material at the end of last year, both from construction companies and individuals preparing to restart projects, but higher prices in the last months are once again limiting purchases.”
However, according to another Spanish steel distributor, current levels may already have become a “new normal”. “At the end of our chain we find the conditions of the large steel companies. If they say they have high production costs and raise their prices, we must accept this, lowering our sales margins to be able to pass this adjustment on to final consumers. However, steelmakers’ commercial dealings are not so flexible with traders,” he said.
A service centre representative expressed concern that steel consumption in Spain is already being affected by higher prices. “Construction companies are reassessing their investments and that is indirectly affecting business. Efforts to improve the added value of our services, as well as improve equipment and build new storage yards, are in vain,” he commented.
Todor Kirkov Bulgaria
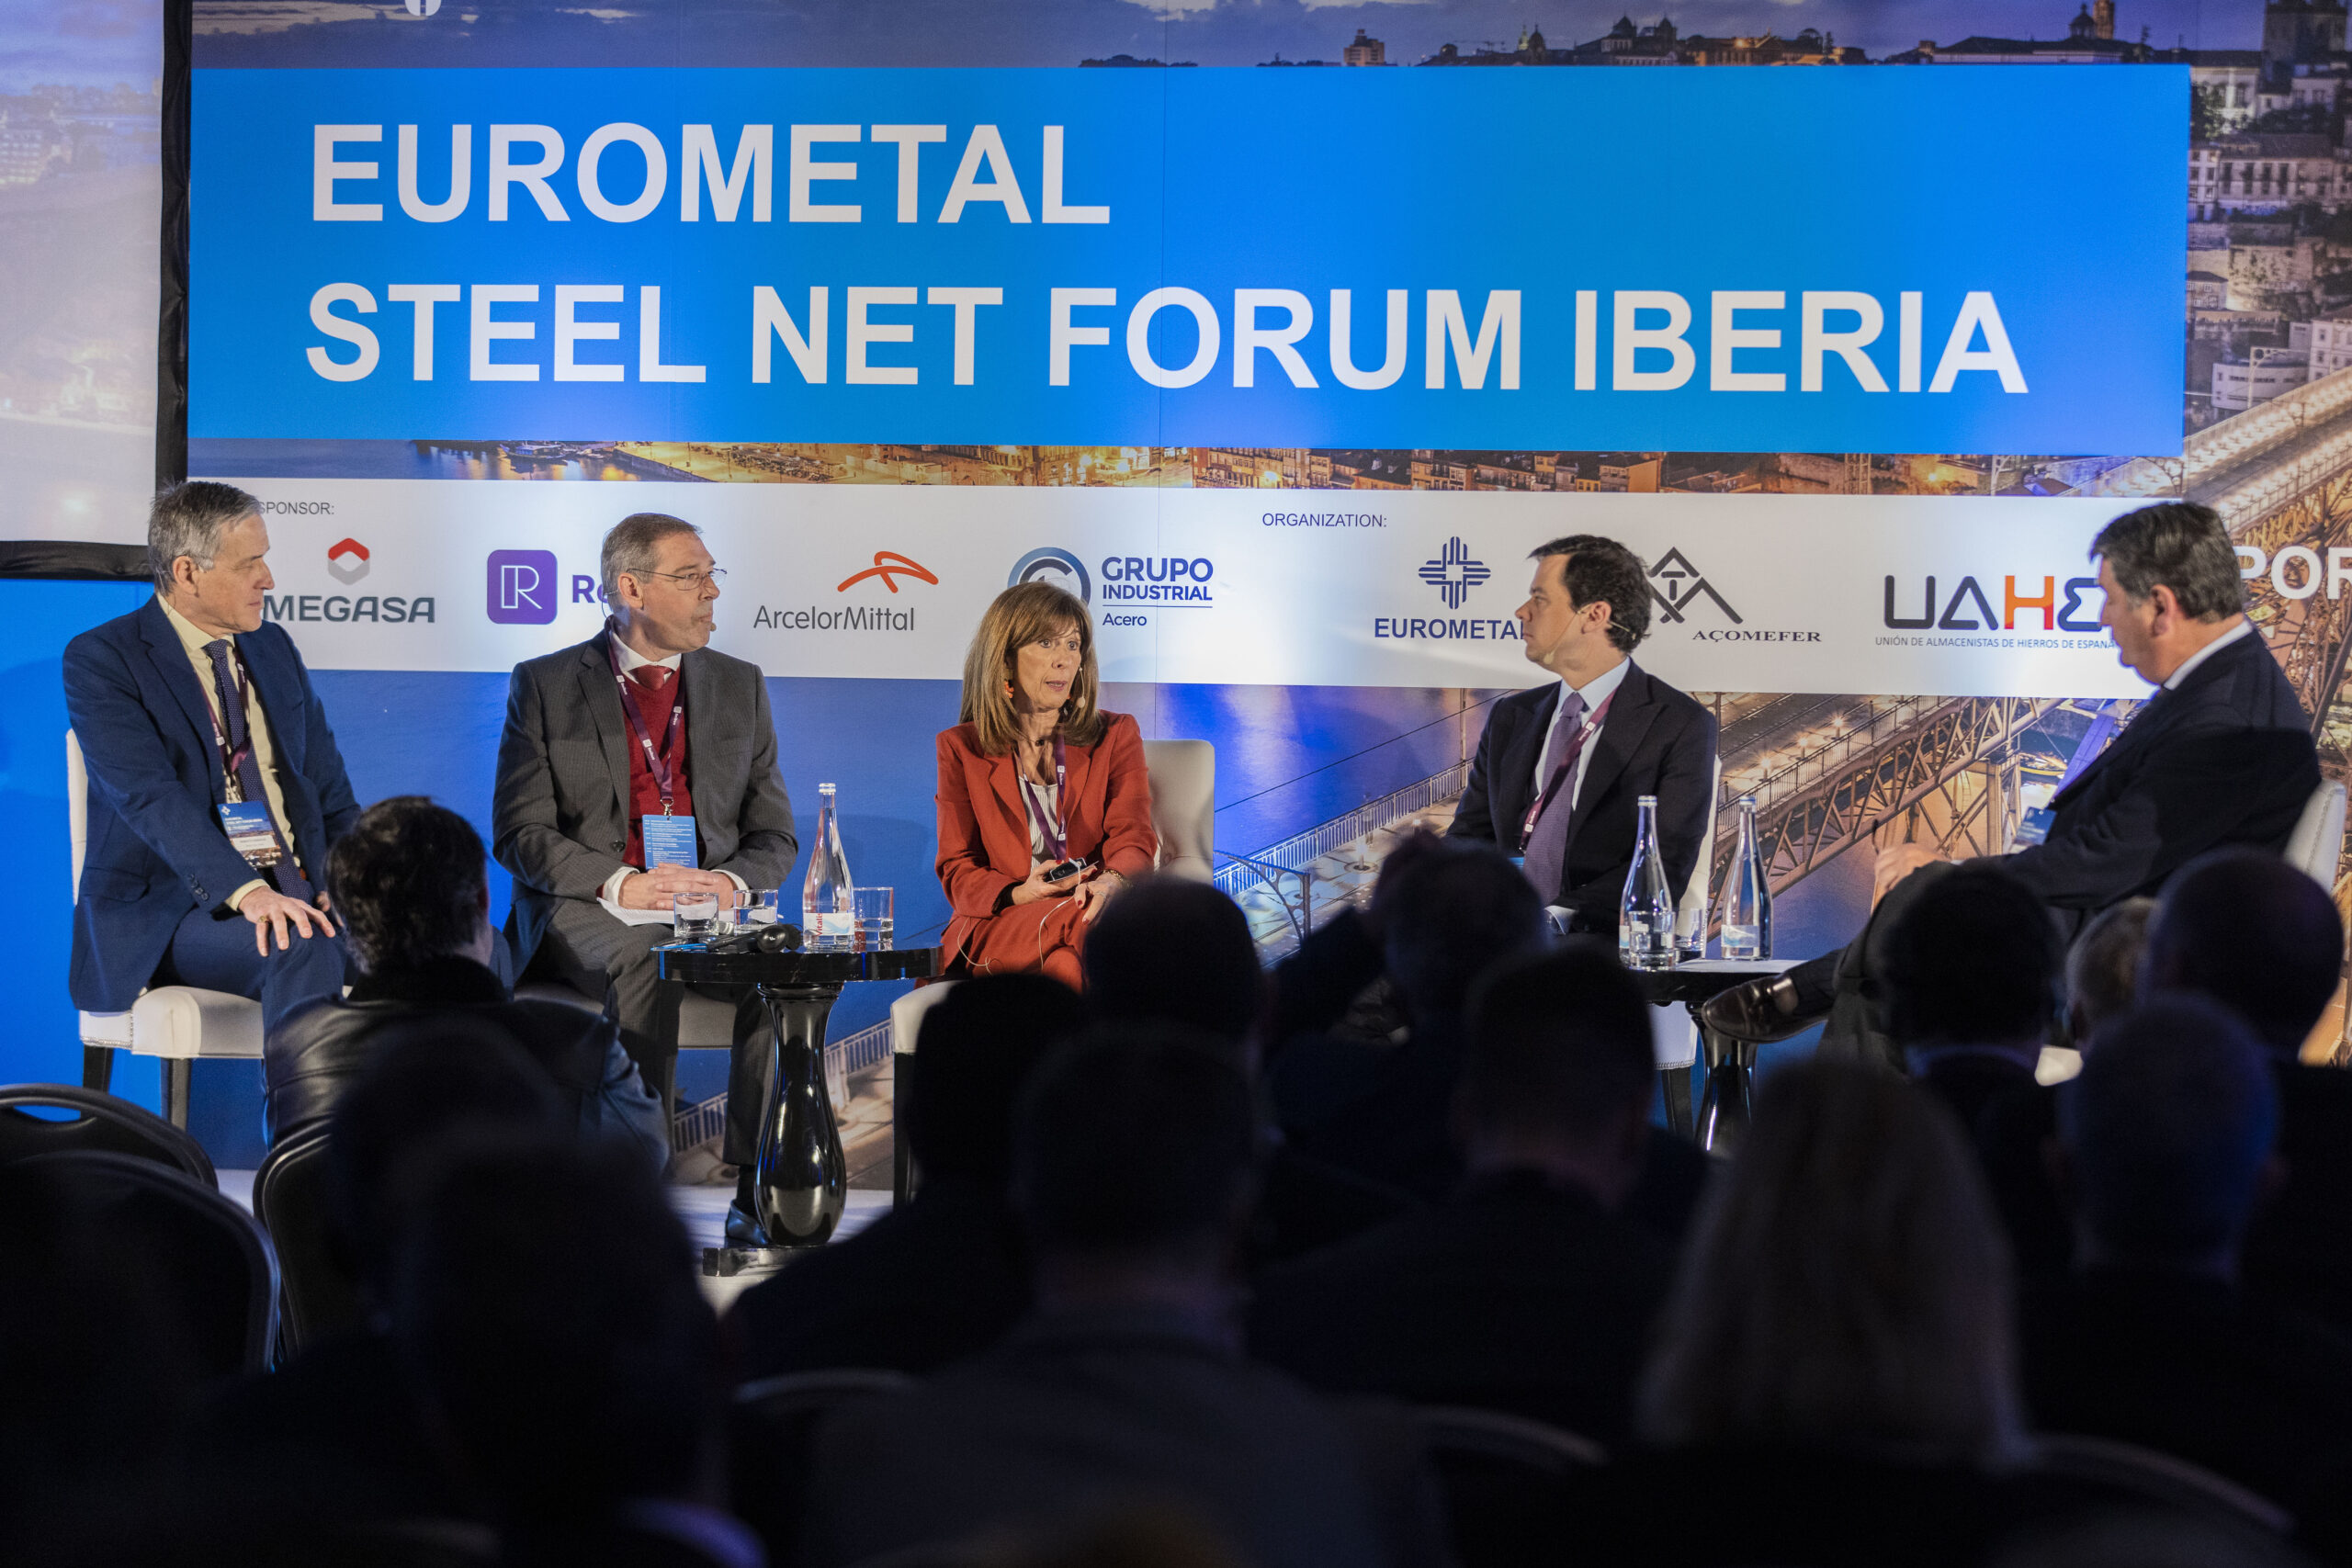
Iberian distributors embrace ‘new normal’, old concerns persist

Spanish and Portuguese steel distributor representatives anticipate certain market fluctuations in the following months, but the market should return to “normal”, Kallanish heard during Friday’s EUROMETAL Iberia Steel Net Forum in Porto.
The new economic reality is seen requiring new solutions from both producers and the distribution chain in the Iberian Peninsula. The sector says some old concerns remain, while it faces a challenging scenario amid high energy and transport prices.
“Good management by companies in the face of the challenging economic panorama does not consist only of selling steel, but also of supplying better and innovative services to customers,” commented Paula Correia dos Santos of J. Soares Correia Group. “Steelmakers and stockists in Iberia have a suitable role in the value chain and thus must understand that giving value to customers can guarantee margins.”
According to Manuel Nobre, president of Portuguese steel distributor association Açomefer, Iberian service centres have been gaining stability since the beginning of the war in Ukraine. “In the last 12 months, we understood that the situation is giving us different opportunities in making business with a profit,” he said. The executive believes distributors have enough capacity to supply the market, but current market demand remains conditioned by high costs and reduced investment.
The president of the Spanish Association of Distributors Union of Iron Stockists (UAHE), Roberto González, said the sector is in the stage of adaptation to the “new market reality”.
“Companies in the sector are undertaking an innovation process because the market demands it. The change of mentality and the greater flexibility attract a young workforce in our distribution centres in an era in which digitisation becomes more and more essential. This improves sustainability and profitability of services,” González observed.
Conference participants agreed that the distribution chain is an essential and fundamental link that completes the steel industry, and manufacturers must understand its important role when making their pricing decisions.
“We have been able to restore supplies and maintain the recovery over the past year, but what mills need to understand is that we are not selling less product because we are out of material. We work in a very dynamic environment and it is difficult to estimate how much stock to maintain. The situation is being dictated by high steel offers, together with the growing competitiveness of the market,” a UAHE delegate added from the audience.
Todor Kirkov Bulgaria

HBIS Serbia restarts BF, plans summer maintenance: reports
HBIS Group Serbia Iron & Steel will resume operations this week at its idled blast furnace, according to media reports. It plans to ramp up production to full capacity this month.
HBIS Serbia did not reply to Kallanish’s request for comment before deadline.
According to reports, the enterprise will operate both blast furnaces, but will suspend one BF in summer for maintenance.
The firm idled blast furnace No.1 at its Smederevo works last July due to low global demand for steel products (see Kallanish passim), saying the unit would be restarted once conditions improve.
The plant in Smederevo can produce about 2.2 million tonnes/year of steel with its two furnaces, while No.1 alone has a capacity of about 900,000 t/y. Product range comprises hot and cold rolled coil, pickled coil and electrolytic tinplate.
HBIS Serbia’s production in January-September 2022 amounted to 901,000t (see Kallanish passim).
The company’s exports to the EU market during the first seven months of 2022, meanwhile, were 397,000t, up by 3.9% on-year.
Serbia’s production of crude steel totalled 100,200t in January, down by 7.4% on-year, according to the latest worldsteel data. In 2022, the country’s output was 1.67 million tonnes, up by 0.3% on-year.
Svetoslav Abrossimov Bulgaria

Market view diverges over effect of Ijmuiden outage
Not quite two weeks ago, Tata Nederland declared force majeure over the malfunction of a cold-rolling mill at Ijmuiden that has failed to run up properly.
The announcement has of course raised concern in the coil market over potential supply shortages. But not across the board. “I do not see it causing any shortage,” an Austrian manager tells Kallanish. “We are far from it, and there are enough of others [suppliers] to compensate.”
Another Austrian however offers a different view. “You do feel that Tata is out of the game; their problems do have repercussions,” he says. Meanwhile, a German trader denies current outages pretty explicitly as “definitely non-existing”. But he, too, concedes they could come further down the road – mainly for automotive coil grades, rather than for commodity DC01 coil. Northwest European mills’ current DC01 CRC transaction values are pegged at €930/tonne ($984).
A differentiated view comes from a person closer to the source of the problem in the Netherlands who observes the overall market’s purchasing behaviour. “European buyers who had so far postponed their restocking will now face trouble,” a Dutch manager believes. He furthermore points at nearby Belgium, where he hears of similar problems at NLMK, which possibly still needs to fully recover from its fire in December.
Christian Koehl Germany

European traders confirm revived interest in Indian HRC
European traders have noted in recent weeks a revival of interest in Indian hot rolled coil, after a year in which orders were significantly below the levels registered in 2021, Kallanish notes.
Indian HRC offer prices are currently increasing (see related story), but they remain the most competitive for EU buyers looking to purchase from third countries.
“I see offers from India now at some €790/tonne [$836] cfr southern Europe, up almost €60/t compared with mid-February,” a trader notes. “This increase confirms that they have had success in booking volumes during the last weeks, for sure.”
According to Eurofer data, last year India supplied around 650,000 tonnes of HRC into Europe, half the volume imported in 2021. This figure was in line with 2020 and the lowest since 2016.
During the first quarter of this year, arrivals of HRC from India have continued to remain slow. According to data compiled by UK Steel, by the end of February only around 10%, or 55,000t, of available EU safeguard quotas had been used for Indian HRC. This trend could nevertheless be reversed in Q2 as volumes ordered during January and February will be arriving in Europe.
Indian sources confirm that mills are currently looking to sell mainly small lots into Europe, to achieve higher prices than when booking bulk volumes.
Emanuele Norsa Italy

Italian rebar market bullish on rising energy costs; prices stable in Spain
Italian rebar producers and buyers alike remained bullish regarding future price increases amid rising input costs.
Despite prevailing optimism about a future uptrend, demand remained slow and market activity was quiet in the week to Wednesday March 15, sources said.
Fastmarkets price assessment for steel reinforcing bar (rebar) domestic, exw Italy was €730-760 ($782-814) per tonne on Wednesday, narrowing upwards by €5 per tonne from €725-760 last week.
Energy costs are expected to rise in the Italian rebar market following an announcement from the Italian government that support provided to steel producers to lower energy costs could be reduced starting from April 1, Fastmarkets heard.
Despite the fact that energy costs have been dropping considerably over 2023, mills in Italy have been provided with ongoing support from the government.
With the government reducing these subsidies, energy costs could weigh heavier on production costs and support price increases, Fastmarkets heard.
“Prices are expected to move upwards in the next two weeks due to sharp and fast increases in scrap prices and significant reductions in energy cost support granted to certain heavy industries by the Italian government starting from April 1 onwards,” a producer source said.
Despite the expected price increases, demand remained subdued.
“The market is quiet, and prices are stable since last week,” another source told Fastmarkets.
“Prices are the same as last week and little has changed in terms of market fundamentals,” a trader source said. “However, scrap prices are increasing a lot, so we expect prices to start rising.”
Spain
Rising input costs could support future price rises in the Spanish rebar market, Fastmarkets heard.
Rebar prices were stable week on week.
Fastmarkets’ price assessment for steel reinforcing bar (rebar), domestic, delivered, Spain was €740-770 per tonne on Wednesday unchanged week on week.
International scrap prices, which have been rising since December 2022, have affected the price of all long steel products.
Fastmarkets’ daily calculation of the index for steel scrap HMS 1&2 (80:20 mix), North Europe origin, cfr Turkey was $459.26 per tonne on March 15, up from $456.26 per tonne last week.
Published by: India-Inés Levy