


ArcelorMittal brings online capture and utilization project at Ghent steel plant
Major European steelmaker ArcelorMittal has started operations its Eur200 million ($210.5 million) flagship carbon capture and utilization, or CCU, project at its Ghent steel plant in Belgium, it said Dec. 8.
The Steelanol plant is the first of its kind in the European steel industry, ArcelorMittal said, adding that it was part of the company’s multi-technology strategy to reduce carbon emissions at the Ghent plant.
The project is due to reduce the Ghent plant’s carbon emissions by 125,000 mt/year.
Platts, part of S&P Global Commodity Insights, assessed the price of Tech Carbon Capture credits at $138/mtCO2 Dec. 7. The assessment has been valued consistently above $120/mtCO2 since early 2022.
The CCU project will use carbon recycling technology developed by partner LanzaTech, which includes using biocatalysts to transform carbon-rich waste gases from the steelmaking process and from waste biomass into advanced ethanol, ArcelorMittal said.
The ethanol will then be marketed by ArcelorMittal and LanzaTech for use in the production of a variety of chemical products, including transport fuels, paints, plastics, clothing and perfume, meaning it will also support the decarbonization efforts of the chemical sector, the company said.
At full production, the Steelanol plant will produce 80 million liters of advanced ethanol, which ArcelorMittal said was almost half of the total current advanced ethanol demand for fuel mixing in Belgium.
ArcelorMittal Ghent is also due to soon bring online its Eur35 million Torero project in the first quarter of 2023, which will process sustainable biomass for use as raw material input into the blast furnace, lowering the volume of coal used, the company said.
The Torero project is due to reduce carbon emissions at Ghent by 112,500 mt/year, with the company panning to double its size over the next two years.
The two projects are therefore due to decrease the Ghent plant’s carbon emissions by 350,000 mt/year once both are completed and at full capacity.
“The imperative to accelerate the road to net zero has never been greater,” ArcelorMittal CEO Aditya Mittal said. “Given the scale of the challenge, it’s important to be open to all technology solutions and certainly, at ArcelorMittal, we are open to all technologies that can take steelmaking to near zero.”
ArcelorMittal Europe CEO Geert Van Poelvoorde added that the CCU project was an important step in reaching the company’s Europe-wide target to reduce its steel’s carbon intensity by 35% by 2030 and achieve carbon-neutral steelmaking by 2050.
“A low-carbon European economy needs low-carbon emissions steel to build its renewable energy infrastructure, low-carbon buildings and electric vehicles…Projects such as Steelanol and Torero will help us to meet that demand through our suite of XCarb products,” Van Poelvoorde said.
To achieve its carbon neutrality goals, ArcelorMittal has to date committed to investing $222.5 million, including an investment of $30 million in LanzaTech.
“This is a steel plant which is embracing the latest innovative technologies; which is using sources of circular carbon; which captures and re-uses as many of its waste products as possible, recycling them into something of value; and which is preparing for a future when green hydrogen will remove the need to use any fossil carbon,” ArcelorMittal Executive Chairman Lakskmi Mittal said.
“The high ambitions of ArcelorMittal for sustainability and circularity fit within the climate targets of the Flemish government: a carbon neutral and circular society by 2050, while safeguarding industrial and economic activities in our region,” Flemish Minister-President and Minister of Foreign Affairs, Culture, Digitalisation and Facility Management Jan Jambon said.
— Jacqueline Holman


Montenegro’s EPCG to acquire Toscelik Niksic steel plant
Montenegro’s state-owned energy company EPCG will acquire the Toscelik Niksic steel mill from Turkey’s Tosyali Holding for Eur20 million ($21 million), EPCG’s Advisor to the Board President Goran Djukanovic told S&P Global Commodity Insights Dec. 8.
Djukanovic confirmed that an agreement between EPCG and Turkey’s Tosyali Holding was due to be signed on Dec. 20.
An initial payment of Eur15 million will be made by Jan. 15, followed by Eur5 million on Feb. 15 after EPCG takes over the full ownership of the mill.
Tosyali acquired Zeljezara Niksic in 2012 for Eur15.1 million through a government auction and renamed it Toscelik Niksic.
Since then, it has invested in the mill to improve and modernize production technologies and achieve high product quality.
Tosyali, however, suspended production at the plant at the beginning of 2021 due to falling orders caused by the coronavirus pandemic, leading to discussions for the sale of the mill.
Tosyali didn’t respond to S&P Global’s request for additional information about the sale.
Niksic produces alloy steel, non-alloy steel, roller-bearing steel, tool steel, and heat-resistant steel.
Platts, part of S&P Global, assessed European medium sections at Eur985/mt delivered Dec. 7, down Eur265/mt since mid-September.
— Cenk Can

UK govt approves new coking coal mine despite environmental opposition .
The UK government late Dec. 7 gave its go-ahead for the UK’s first new coal mine for 30 years amid strong environmental opposition, which could yet derail the project with no start-up date announced
West Cumbria Mining’s Whitehouse Colliery project at Whitehaven in the UK’s North West, with an expected 3.1 million mt capacity to produce coking coal for steelmaking, has been under development since 2014. It gained initial approval from the Secretary of State for Communities and Local Government in early 2021, since when it has been working on sustainability plans and licensing.
WCM said Dec. 8 it was “delighted” with the decision of the Secretary of State to formally approve the Woodhouse Colliery planning application.
“The project can now move forwards to deliver the world’s first net zero mine supplying the critical steel industry with a high-quality metallurgical coal product,” WCM said in a statement.
The new project is contiguous to the last deep Cumbrian coal mine, Haig Colliery, which closed in 1986. A century ago, the UK was a major coal producer but output declined as deindustrialization and globalization made it harder to achieve economies of scale. Premium Low Vol coking coal was assessed flat at $249.50/mt FOB Australia, and CFR China was assessed down $2/mt to $315/mt CFR China Dec. 8, according to the Platts assessment from S&P Global Commodity Insights.
The new mine — located underground on a brownfield site — is expected to produce an average of 2.5 million mt/year of coal and extract and process up to 3.1 million mt/year over a 40-year mine life, according to information previously issued by WCM. The coal is a high-quality high volatile, hard coking coal (HV HCC). It has less than 4% ash, less than 0.001% phosphorous and extremely high fluidity of 30,000 dppm, the miner said.
The product is to be processed at a new preparation plant, then transported via a buried conveyor 2.2 km (1.4 miles) to a train loading facility for rail transportation via an existing link to Redcar Bulk Terminal on the UK’s east coast. This is a deepwater port that can accept Panamax vessels year-round for onward distribution, the company said. Investment in the mine project was initially put at around $224 million.
Political considerations
Despite plans for a low-carbon emissions mining operation, the project is surrounded by controversy. UK integrated steelmakers British Steel and Tata Steel, which currently import coal for their blast furnaces, indicated they would potentially use only a small fraction of the new mine’s output.
“While we could technically use a small amount of coal from the proposed mine in West Cumbria, any potential supply would be a commercial decision,” a British Steel spokesperson said Dec. 8. Chinese-owned British Steel sources its coal from global markets excluding Russia, the spokesperson said.
A spokesperson for Tata Steel said: “We continue to review the origins of all the raw materials used in our steelmaking process to ensure they are high quality, cost effective and ethically sourced. We’re conscious of our role as one of the UK’s biggest industrial CO2 emitters and have made significant progress to reduce our carbon footprint through innovative solutions and new technologies. Constructive conversations with the UK government about the wider decarbonisation of our manufacturing processes are ongoing.”
The government has touted the WCM project as capable of saving transport emissions as it could replace imports of coal: however, steel industry sources heard by S&P Global Commodity Insights indicated much of the new mine’s output would end up being exported, mainly to European mills.
The government’s approval of a new coal mine has clear political overtones at a time when coal usage is to be phased down, according to an international agreement made at last year’s COP 26 climate summit in Glasgow. A government representative told the BBC Dec. 8 the mine project will provide 500 direct jobs and 1,500 indirect jobs in a part of the country favored by the conservative government’s “levelling up” program which aims to improve wealth distribution nationwide.
The coal mine will provide a “transitional, but not a long-term solution” for providing coking coal to domestic integrated steelmakers, which will still need coal for “a period of time” during their decarbonization pathways, the government representative told the BBC. Many blast-furnace-based steelmakers plan to transition in coming years from coal usage to alternative fossil-free fuels, including hydrogen.
Mainly because of its coal usage, steelmaking is considered a “hard-to-abate” industry, responsible for around 9% of total global emissions.
One argument used during the new project’s planning phase was that it could help build a stronger local supply chain to the UK steel industry following the UK’s exit from the European Union.
— Diana Kinch

Liberty’s Galati shuts only working BF for maintenance; no market impact foreseen
Liberty Steel’s decision to suspend operations at a blast furnace (BF) at its Galati plant in Romania for the rest of the year for planned maintenance will have no impact on supply, it said.
BF5, which has capacity of 2 million tonnes per year of pig iron, will close for maintenance work before the end of the current week and will remain idle until the start of 2023, the company said on December 5.
The company expects the BF stoppage to have no impact on the market, considering the weak steel demand and approaching holiday period.
“The timing of the program, with steel demand across Europe impacted by macroeconomic issues, will allow Galati to make the improvements to its production processes without impacting customer delivery,” it said.
The rolling mills will remain fully operational during the BF downtime, apparently using slab from stock, Liberty Steel said.
The maintenance program at Galeti, which produces hot-rolled, cold rolled, hot-dip galvanized coil, plate and welded pipes, will cost 18.3 million Romanian leu ($3.9 million), the company said.
From September, several European steelmakers have announced output cuts and capacity closures, mainly in the flat steel sector, because of weak demand. Liberty Steel shut another BF in Ostrava over the summer without specifying when it will restart.
Published by: Julia Bolotova


European HRC prices mainly flat, mills target increases for Q1
European hot-rolled coil producers expect prices to rebound in the first quarter of 2023, while buyers are less optimistic, Fastmarkets heard on Wednesday December 7. Fastmarkets calculated its daily steel HRC index, domestic, ex-works Northern Europe at €626.88 ($657.70) per tonne on Wednesday, down by €2.50 from €629.38 a day earlier.
The latest calculation of the index is up by €5.63 week on week, but down by €23.54 per tonne month on month.
Both buyers and producers largely believe that a price floor has been reached. Some mills started to adjust their offers for January-February rolling coil upward at the end of last week.
Notably, the price idea from most mills for February-rolling HRC was no lower than €650 per tonne EXW.
Buyers, however, estimated trades would take place between €610 per tonne EXW and €650 per tonne EXW, depending on the tonnage and specifications.
“The market is a bit more active this week [and] there are fewer import offers available. And on top of that, more mills are shutting down blast furnaces and rolling mills. So, the availability of HRC will be reduced,” a buyer said.
HRC offers from an Italian producer to the south of Germany were heard at €670-680 per tonne CPT, compared with €650-660 per tonne CPT last week.
Buyers said they had doubts regarding a recovery in consumption early next year.
Additionally, some distributors still have stock that they bought at higher prices and were focused on selling it off.
Fastmarkets’ calculation of its daily steel HRC index, domestic, exw Italy was €624.50 per tonne on Wednesday, down by €3 per tonne from €627.50 per tonne on Tuesday.
The latest calculation of the Italian index is up by €13.67 per tonne week on week, but down by €41.75 per tonne month on month.
Offer from Italian mills were reported at €630-650 per tonne EXW, while buyers’ estimates of tradeable values were at €620-630 per tonne EXW.
Sources said that Italian mills were mainly sold out for January-rolling coil and were offering February-rolling material already.
HRC suppliers from Southeast Asia were mainly out of the market in the week to Wednesday. Sources suggested that overseas HRC sellers might come back to the market with higher offers next year.
India-origin HRC was the only foreign material available in the market. Notably, offers from India late last week were heard at €600-610 per tonne CFR Italy, while starting this week Indian mills were targeting €620 per tonne CFR minimum, sources said.
At the same time, buyers’ estimates of workable prices for import HRC were no higher than €590 per tonne CFR.
Published by: Julia Bolotova

ArcelorMittal acquires third steel scrap recycler this year
ArcelorMittal is to acquire Riwald Recycling, a Netherlands-based ferrous scrap metal recycling business, the steelmaker announced Dec. 6.
This will be ArcelorMittal’s third scrap processing business acquisition this year, as it seeks to reinforce the role that scrap steel can play in its efforts to decarbonize. The steelmaker, Europe’s largest, is working towards meeting a target to reduce the carbon intensity of the steel it produces in the region by 35% by 2030, it said.
Steelmaking using ferrous scrap produces significantly fewer carbon emissions than steel produced using primary raw materials, including coking coal and iron ore.
Steelmaking — a hard to abate industry — is held responsible for around 9% of total global carbon emissions, although the percentage varies by region.
The parties signed a transaction for the Riwald acquisition Dec. 5, with closing — subject to customary regulatory approvals — expected by the end of January, ArcelorMittal said.
Riwald Recycling was founded in 1989 and processed over 330,000 mt of ferrous scrap metal in 2021. It operates two fully certified scrap metal yards in Almelo and Beverwijk in the Netherlands, both of which have direct port access, and sources material from a wide range of suppliers, including industrial companies, OEMs, demolition companies, traders, car dismantling companies and regional and national government, ArcelorMittal said.
Geert Van Poelvoorde, ArcelorMittal Europe CEO, said the steelmaker looks forward to working with Riwald’s CEO, Gert Huzink, and the scrap producer’s employees, to further develop its business.
“Although it is ultimately the various low-carbon emissions steelmaking technologies which we are developing and deploying which will take us to net-zero, given the urgent need to make progress this decade we are working hard to move forward on all fronts,” van Poelvoorde said. “Therefore, securing access to the raw materials — scrap steel and direct reduced iron — required for low-carbon emissions steelmaking has a very important role to play.”
Earlier this year ArcelorMittal announced the acquisition of several metal recycling facilities from ALBA International Recycling and the acquisition of Scotland-based John Lawrie Metals. Together with Riwald, these three businesses processed over 1 million mt of scrap steel in 2021.
In its second Climate Action report, published in July last year, ArcelorMittal outlined five levers that will enable the company to achieve carbon neutrality by 2050, one of which was increased use of scrap steel. As well as using scrap in an electric arc furnace, the company noted that it can increase the use of low-quality scrap in the blast furnace-basic oxygen furnace steelmaking process by improving steel scrap sorting and classification, installing scrap pre-melting technology and adjusting the steelmaking process to accommodate scrap.
Turkish import deepsea scrap prices continued to rise Dec. 6, as purchasing for prompt and January shipments persisted, amid reports of market tightness.
Platts, part of S&P Global Commodity Insights, assessed Turkish imports of premium heavy melting scrap 1/2 (80:20) at $382/mt CFR Dec. 6, up $2/mt on the day. The assessment has increased $45.50/mt from a recent low of $336.50/mt CFR in mid-November.
— Diana Kinch
Outokumpu partners with Klöckner & Co to supply lower emissions stainless steel
Finnish stainless steelmaker Outokumpu has partnered with German steel distributor Klöckner & Co. to supply its emission-minimized stainless steel and gain industry market share, the companies said Dec. 7.
The first coil made of emission-minimized stainless steel, part of Outokumpu’s Circle Green product line launched in June 2022 to decarbonize the industry sector, had already been delivered, with larger quantities to start from 2023, they said.
According to Outokumpu, the Circle Green product is the first of its kind globally, with no other stainless steel manufacturer producing stainless steel with as low emission levels, taking into account the climate emissions from raw material extraction through the whole production chain.
“Partnering around sustainability offers the possibility to cut emissions and help companies to reach their climate targets,” Outokumpu CEO Heikki Malinen said, adding that both companies had strong aspirations to develop a sustainable metal sector.
“After securing significant quantities of CO2-reduced steel at an early stage, we are now also committed to increasing the availability of other CO2-reduced metals for our customers – Outokumpu’s first CO2-minimized stainless steel coil is another important step for our company in the right direction,” Klöckner & Co. CEO Guido Kerkhoff said.
“With this we enable even more of our customers to build sustainable value chains already today and strengthen our position as a pioneer of sustainability,” he added.
Klöckner had classified Outokumpu’s Circle Green products in its “Prime” category, allowing the distributor to expand its portfolio of CO2-reduced materials under its new umbrella brand Nexigen, it said.
In November, Outokumpu said it aimed to improve its energy efficiency by 8% across the group in 2023 and 2024, compared with the January-September 2022 level, which would save around 600 GWh of energy. It also said it would prioritize related investments amid the energy crisis in Europe.
— Jacqueline Holman
Slovakia’s US Steel Kosice temporarily idles a second blast furnace
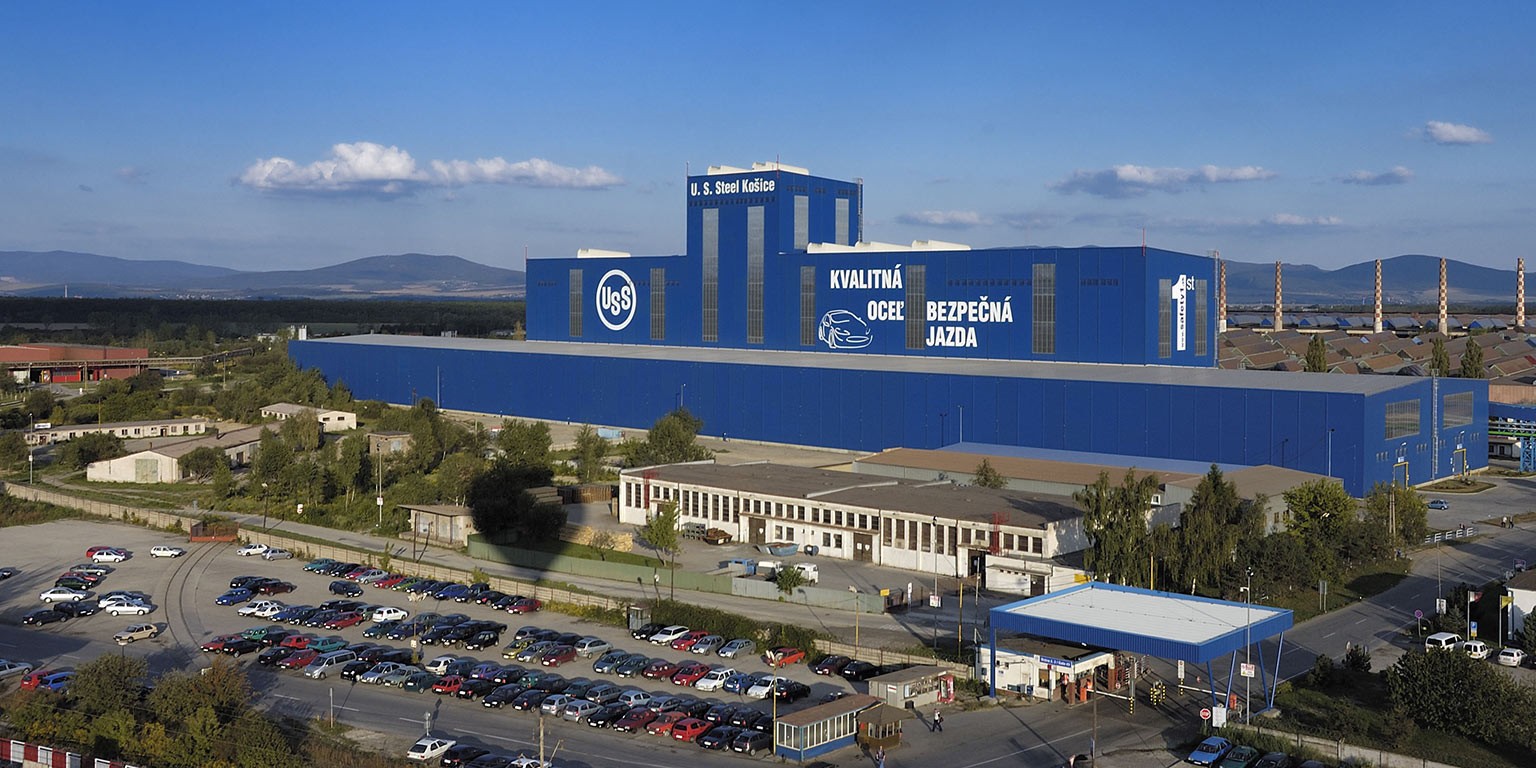
Slovakian steelmaker US Steel Kosice has shut down a second blast furnace until early 2023, a spokesperson for parent company US Steel confirmed to S&P Global Commodity Insights Dec. 7.
“US Steel Kosice made the decision to temporarily idle blast furnace 1 on Dec. 2 as a result of very high energy prices, low market demand and surging imports,” the spokesperson said, adding that the company expected to resume operations at the beginning of 2023.
US Steel Kosice previously idled its BF2 on Sept. 4 for 60 days, keeping BF1 and BF3 operational.
At the time, the company described the BF2 idling as a planned outage and said it would continue to adjust maintenance schedules according to demand.
US Steel Kosice has a crude steel production capacity of 4.5 million mt/year.
A number of European steelmakers have cut production in recent months to realign supply and demand.
Platts, part of S&P Global, assessed domestic HRC prices in Northern Europe at Eur615/mt ex-works Ruhr Dec. 6, down 33.3% since the start of 2022.
— Jacqueline Holman, Maria Tanatar

EU steelmakers target HRC price rise on improving restocking activity
European steelmakers have been aiming for higher domestic hot-rolled coil prices on Dec. 7 as they expect demand to improve in the first quarter due to restocking.
Although some big producers have not officially moved prices up, they refused to give discounts, sources said.
The rising mood of the mills has been supported by anticipated restocking of distributors across Europe, the need to cover high production costs and the withdrawal of competitive import offers from the market this week.
Trading activity, however, has been restricted as distributors continued to focus on destocking by the year-end and the buyers have been evaluating end-user demand before making deals, according to market sources.
“It is expected that coil prices will go up in the first quarter, latest in the second quarter – but there are still no big deals done,” a German distributor said. “I guess customers are aware that prices will go up, but still hesitate to buy due to unclear demand.”
“Mills are holding back from sales, as they understand that the longer they wait the better the chances to get higher prices,” a German service-center source said. “Buyers are trying to talk prices down, but it seems that they do not have control over prices now.”
Platts assessed HRC in Northwest Europe at Eur615/mt ex-works Ruhr Dec. 7, up Eur5/mt day on day.
Distribution sources reported tradable value at Eur620/mt ex-works Ruhr. One distributor reported tradable value lower at Eur610-620/mt ex-works Ruhr. Another reported Eur620/mt ex-works Ruhr as a minimum price.
Official offers have been heard at Eur650/mt ex-works Ruhr.
Platts assessed domestic HRC in the south of Europe stable at Eur620/mt ex-works Italy Dec. 7.
The assessment was based on offers heard at Eur620-650/mt ex-works.
Platts is part of S&P Global Commodity Insights.
— Maria Tanatar, Benjamin Steven

European CRC, HDG markets signal increases, buyers resistant
Mills were heard as indicating higher CRC, HDG prices Dec. 7, though buyers still perceived opportunity to secure competitive volumes before the end of the year.
In the cold-rolled coil market, North European prices were up Eur20/mt on week, assessed at Eur720/mt ex-works Ruhr. South European CRC was stable on week, assessed at parity with the Northern market at Eur720/mt ex-works Italy.
Indications for North Europe were received at Eur710-720/mt ex-works Ruhr and Northern Europe, as reported by distribution sources. Higher offers were heard across Europe, with one Italian mill heard as offering in the mid-Eur800s.
Market participants did not view said price level as achievable, however, given the poor consumption outlook for distributors moving into next year, but did agree that the floor had likely been reached.
As for galvanized coil, the HDG ex-works Ruhr price was up Eur10/mt on week at Eur750/mt, with the Italian assessment increasing by Eur15/mt to Eur740/mt ex-works.
While offers in North Europe were generally heard at a Eur750/mt ex-works minimum, deals were rumored as achievable from German mills at Eur720/mt delivered Ruhr on firm bids.
Platts is part of S&P Global Commodity Insights.
— Benjamin Steven, Maria Tanatar