


European scrap prices expected to increase in January
European scrap prices are seen increasing in January, sources in France, Germany and some Eastern European countries believe.
Large steelmakers are seen increasing prices of finished long products for January and scrap is said to be in short supply in Europe, particularly E40 shredded grade. In Eastern Europe, sources say the snowy weather this week is not helping collection, and sellers also talk about poor availability, particularly for the lower grades. E8 new arisings is meanwhile largely available but not so much in demand.
Meanwhile, German suppliers are offering lower tonnages to Italian mills this month, due to short availability. Import contracts in Italy from France and Germany are stable compared to November. However, Italian mills will have to pay a €10-12/tonne ($10.5-12.6) rail freight increase for scrap delivered from Germany and some €5-7/t increase for scrap delivered with intermodal transport. While the transport increases are still being negotiated, all import contracts have been agreed with the option to pay some €10/t on top for rail transport from 1 January.
Imported scrap volumes are lower this month, also due to Italian mills shutting down for the Christmas holiday break. Contracts from France and Germany to Italy show E8 mixed grade remaining at €360/t, E40 at €370/t, E3 at €350/t and the lower E1 grade at €320-325/t, all on a delivered basis. Like last month, Italian steelmakers are requesting high volumes of E1 and E40, sources suggest.
Import contracts are in the process of being negotiated with Eastern European suppliers. They are forecast however to also remain stable month-on-month. Last month, Italian mills paid €355-360/t delivered for the mixed E8 grade, about €300/t for E1, €370/t for E40 and €330-340/t for E3, Kallanish notes. Importing material from Eastern Europe will also cost some €10/t more from January.
Over the past month, rail operators in various supplier countries have asked for a 30-40% freight tariff increase effective 1 January. While Italian steel companies are trying to negotiate the increases, both scrap suppliers and steel mills will be hit by the move, together with many Italian steelmakers selling coil and long products in Germany and Austria (see Kallanish passim).
Natalia Capra France


Non-China consumption offsets China slowdown, Europe uncertain: Fitch
Steel consumption outside China in 2023 should outpace the managed decline in China by 25-35 million tonnes, mostly due to dynamic growth in India, Southeast Asia and the US, says Fitch Ratings. Despite a swift supply-side response in Europe, competition in unprotected markets is intensifying, with margins visibly coming off post-Covid peaks and set to normalise in 2023.
“Sentiment remains constructive and above mid-cycle in North America, India, Turkey and Brazil, which benefit from protective trade measures, government support for infrastructure spending and/or production cost advantages,” Fitch says in a report sent to Kallanish.
In China, steel production will again decline by a low single-digit percentage in 2023 to above 0.9 billion tonnes, but margins achieved will very much depend on demand growth in China as well as major export markets. Residential housing projects will continue to decline while growth in infrastructure projects may moderate.
“Policy uncertainties continue to cloud the sector outlook,” Fitch comments. “Strict nationwide Covid measures and tight liquidity faced by property developers remain key challenges for steel sector demand recovery. Multiple policies were issued to alleviate funding difficulties for property developers. However, the impact of these measures on property market recovery remains hard to quantify so far, as broader consumer confidence will be the deciding factor for new home purchases.”
Manufacturing activity, such as machinery, automotive and appliances, will continue to grow in 2023 backed by favourable policy support, but this is unlikely to be sufficient to offset the slowdown in construction activities.
Chinese mill margins should improve from 2022 levels as many companies were suffering losses during the third quarter. Any incremental deterioration in margin level would likely result in further production cuts, Fitch says.
In Europe, the outlook for steel companies remains weak, clouded by high and volatile energy costs, waning GDP growth and consumer confidence. Also weighing is the relatively greater need to re-draw supply chains for the steel sector and possibly its end-markets, due to the Ukraine war impact.
European production was curtailed to balance supply with demand but, for now, ample supply remains available to the market. “Stocks are normal to high and there is little prospect of buying for inventory, meaning order books will not receive a boost from restocking,” Fitch says. Steel consumption should rebound slightly in 2023 but uncertainties remain around consumer confidence, inflation and the macro backdrop.
Many steel mills are still benefiting from contracted volumes for 2022, meaning reporting for the full year is likely to reveal robust earnings. “However, orderbooks are running off and prevailing (spot) Ebitda margins will lead earnings to rebase to lower levels in 2023. In addition, countries less affected by the energy crisis compete for European volumes, which will contain prices at lower levels for some time,” Fitch concludes.
Adam Smith Poland

Bilstein contracts low-carbon steel from thyssenkrupp
German cold-roller group Bilstein has signed a letter of intent with both thyssenkrupp Steel Europe and its subsidiary thyssenkrupp Hohenlimburg for the supply of CO2-reduced “Bluemint Steel” from 2023.
On the basis of CO2-reduced wide strip directly from the Duisburg steelworks as well as “Precidur” precision strip made at Hohenlimburg, Bilstein intends to offer CO2-reduced cold-rolled products across its entire product range. Bilstein signed last month a similar supply deal with Swedish venture H2 Green Steel (see Kallanish 2 November).
According to tk Steel, volumes will increase gradually up to 2030, and from 2026 onwards will come from its direct reduction plants and melters in Duisburg, operated with green hydrogen and renewable electricity.
Bilstein manufactures products for highly demanding cold rolling applications in the automotive sector as well as the processing and toolmaking industries, for example in saws and tools, door fittings, coins or vehicle seats.
Christian Koehl Germany

Thyssenkrupp executive to head German steel federation
Bernhard Osburg, ceo of thyssenkrupp Steel, will be the new president of German steel federation Wirtschaftsvereinigung (WV) Stahl as of 1 January. He will be succeeding Hans Jürgen Kerkhoff, who is retiring at the end of this year.
Osburg will be honorary president of WV Stahl for two years, the federation tells Kallanish. The change marks a departure from the former separation of the honorary title and the full-time position, WV Stahl notes, but does not give a detailed explanation of the future personnel set-up.
Kerkhoff became WV Stahl’s second managing director in 2004, with Dieter Ameling as the president and first managing director. Since Ameling’s retirement, Kerkhoff has held both top positions. In its current announcement, WV Stahl does not comment on the position of the managing director.
This also is the first time that an executive from a member company has become the nominal president of the federation.
Christian Koehl Germany

AMP pushes back BF restart, unions express concern
ArcelorMittal Poland (AMP) trade unions have expressed concern that the steelmaker’s pushing back of the blast furnace no.3 restart at Dabrowa Gornicza could result in the unit being shut down for good.
At the turn of November and December, unions were informed that BF3, which was idled at the end of September due to deteriorating demand, would be restarted between 10 and 20 December. They have now been told this will happen in early January, but no date has been specified.
“It’s starting to resemble the situation at AMP’s Krakow works, which also saw the blast furnace restart pushed back a few times in 2020, before ultimately it was closed for good,” Lech Majchrzak, chairman of the Solidarnosc trade union at AMP, says in a note seen by Kallanish.
AMP says the market situation does not warrant the BF restart before year-end. Since the BF was idled, “we have been closely observing the market, the forecasts in terms of a possible rise in demand, the long-awaited improvement of European activity”, an AMP spokesperson says. “Unfortunately, this is not yet happening. And we do not see any signs of market recovery in the coming weeks. We still see that our order book continues to be at a level that remains below the minimum working point of two blast furnaces.”
“Regrettably, due to the mentioned reasons, we will not be able to restart the BF before the end of this year. We continue to be prepared for a restart of BF3; however, the exact date will depend on the market situation,” the spokesperson adds.
“This does not imply any changes to the commitments we have made related to the temporary stoppage. We continue to prepare a two BF operation and the BF3 will certainly be restarted before BF2 will be stopped for its modernisation,” she observes.
In early October, trade unions signed an agreement with the steelmaker that guaranteed BF3 will be restarted again in future and there will be no job losses as a result of the stoppage (see Kallanish passim). BF3 is to be restarted no later than when BF2 begins the shutdown process to carry out its long-awaited maintenance. This is most likely to happen next February or March. AMP management also confirmed it will strive to maintain the operation of both blast furnaces.
According to Majchrzak, because of the time required to restart and stabilise BF3 production, and then shut down BF2, the whole procedure has to be initiated by mid-January in order to be ready for March.
Adam Smith Poland

French rebar market resumes activity
The French rebar market is finally shaking off its long-lasting stagnation. Sellers in the north and south of the country report some restocking and an improved level of demand over the past week. Prices remain steady and some sources believe a slight uptick is possible in the coming days.
Like in November, in the south of the country, particularly, competitive import offers from Spain are being reported. November was a particularly slow month for sales but December is bringing some dynamism, with customers ordering material for January, Kallanish notes.
Including size extras, domestic contracts are concluding at an average of €720-730/tonne ($760-771) ex-works delivered, sources suggest. Sellers, also in Germany and Italy, are reporting higher order intake over the past ten days following a long period of slow sales. French buyers however remain cautious and do not believe demand for rebar will remain strong in January.
Meanwhile, French and Luxembourg domestic scrap prices are flat again in December after the stability seen in November. Some large merchants have lowered their scrap intake, but this is not pressuring availability as mill demand for scrap remains poor due to the European long steel downturn (see Kallanish 9 December).
Natalia Capra France

Northwest Europe coil shows meagre price recovery signs
Some initial signals are being seen for attempted price increases in Europe, north of the Alps, but they are still too weak to result in a rebound of coil prices.
According to a southern German manager, hikes of €50/tonne ($53) announced by a Czech mill for February rolling/delivery are actually meant seriously. “We would have ordered at January’s prices, but they [Czech supplier] refused,” he tells Kallanish. The hike would take the offer price from €630 to €680/t, he says.
This would be in support of the offer prices of northwestern mills, which have been held “above €650 for most of the time, give or take a tenner,” one buyer in North Rhine-Westphalia says. But while he has not bought for a long time, others did, and tell of deals well below that mark when a transaction came about.
The former manager confirms so, but finds that discounts are not granted as easily any more as they were a couple of weeks ago still. “I feel that a certain pride in the pricing is coming back,” he observes. Regarding the relatively clear increases that have been seen in Italy, he notes that the Italian market works by a different logic, largely due to the influence of imports. “Import prices rose two weeks ago, and the Italian mills followed up,” he comments.
Higher import prices are meanwhile also being registered in the north, and could have an influence. “Last week, some volumes were offered for Q2, and were sold very quickly, and now mills in Taiwan and Indonesia have gone up $20-40,” the NRW buyer says. This takes import prices close to the level of northwest EU mills, “which will then be encouraged to go up, too”, he predicts.
Christian Koehl Germany

Tata Steel UK’s blast furnace improvement program aims to cut 160,000 mt of CO2
Tata Steel’s Port Talbot iron and steel works in South Wales, UK is implementing an improvement program for its blast furnaces, which will reduce the site’s carbon footprint by 160,000 mt/year, the company said Dec. 12.
This reduction is equivalent to the annual emissions from 100,000 cars or those from the energy used by 50,000 households, according to the company.
The two Port Talbot furnaces, which produces 3.6 million mt/year of liquid iron, are powered by high pressure blast air that is heated to over 1,100 degrees Celsius, it said.
Recycled on-site process gases — the blast furnace gases enriched with some coke oven gas and natural gas — will be used to heat the air in seven refractory brick-lined stoves, before it is injected into the blast furnaces, the company said.
As part of the improvement program, burners in three of the seven stoves are being upgraded with two new best available technology units, Tata said, adding that it would also be replacing many of the refractory bricks that store heat and make hot blast air.
The work is being carried out while the remaining operational stoves are in use, Tata said.
The upgrade work is due to make a significant difference to the mill’s carbon footprint, its energy costs and operational stability and efficiency, Tata Steel Project Manager Andrew McGregor said.
“Stoves are critical to the running of our blast furnaces,” McGregor said. “Any loss of efficiency in heating the air means we either have to use more gas than optimum, or replace that lost energy by using more metallurgical coke to chemically reduce the iron ore inside the furnaces.”
Tata Steel UK has a crude steel capacity of 5 million mt/year and aims to reduce its total CO2 emissions by 30% by 2030 and be a carbon-neutral steelmaker by 2045, in line with the UK’s ambition to be net-zero by 2050.
In November, Tata announced it was installing digital scanning technology at its no. 5 blast furnace at Port Talbot to reduce the amount of coke used in the furnace, assisting decarbonization, similar to the technology installed at the works’ no. 4 blast furnace in 2021.
In October, the company said it was cutting the energy use and the carbon footprint of the hot rolling mill at the plant by using laser technology at the site’s two slab re-heating furnaces.
Platts, part of S&P Global Commodity Insights, assessed the weekly UK hot-rolled coil price at GBP615/mt ($755.29/mt) DDP West Midlands Dec. 8, down 25.9% from the start of 2022.
— Ekaterina Bouckley


UK metal exports mostly increase on year in Oct: ONS
The UK saw exports of most metal categories rise in October 2022 on a year-on-year basis, with the EU27 remaining a major destination, according to non-seasonally adjusted figures published Dec. 12 by the Office for National Statistics.
Total exports of iron and steel for the month totaled GBP479 million ($588.7 million), rising 11.1% year on year, but down 2.4% month on month, according to the figures.
The UK’s largest iron and steel customer in October was the EU at GBP305 million, dropping 1.3% on the year and down 8.1% from September.
Main EU destinations were Ireland at GBP51.9 million and the Netherlands at GBP47.5 million.
Another major iron and steel destinations in October was the US at GBP62.9 million.
The UK’s exports of metal ores and scrap rose 2.8% on the year in October to GBP593 million, which was 1.2% lower than September’s volume, the data showed.
The largest destination of metal ores and scrap from the UK in October was the EU at GBP184 million, dropping 8.5% year on year, but up 3.4% from September, followed by India at GBP173.1 million.
Large EU destinations included Belgium at GBP57.35 million and Germany at GBP41.4 million.
Nonferrous exports up 42.6%
Exports of nonferrous metals also rose 42.6% on the year to GBP1.4 billion, although this dropped 34.1% month on month.
The largest taker of the UK’s nonferrous exports was the EU at GBP502 million, rising 61.9% year on year and up 4.8% from September. This included GBP200.8 million to Germany.
The UK also sent GBP270.4 million worth of nonferrous metals to India in October, down 3.4% year on year and falling 60.8% from September.
Other large nonferrous metal destinations during the month were GBP173.3 million to the US and GBP111.7 million to North Macedonia.
The UK also exported GBP676 million worth of miscellaneous metal manufactures in October, up 11.6% on the year and up 8.5% from September, of which GBP357 million went to the EU.
However, coal, coke and briquette exports for the month fell 6.7% year on year and were down 30% on the month to GBP14 million.
The ONS noted that it had excluded non-monetary gold and other precious metals in its statistics, due to gold movements tending to be large and highly volatile, distorting underlying trends.
Metal exports for the January-October period were higher year on year, with iron and steel exports totaling GBP4.97 billion, 29.7% higher on the year, the stats showed.
Coal, coke and briquette exports for the period rose 38.1% on the year to GBP156 million, while metal ores and scrap exports were 4.4% higher at GBP6.5 billion.
Nonferrous exports for the first ten months totaled GBP16.7 billion, up 24.5% year on year, while the UK exported GBP6.07 billion worth of miscellaneous metal manufactures, rising 12.1% on the year.
Iron and steel imports lower on year
The UK’s imports of iron and steel in October fell 11.1% year on year to GBP674 million, although this was up 18.2% from the previous month.
Imports came mostly from the EU at GBP408 million, up 7.7% year on year and rising 6% from September.
Major EU suppliers included Spain at GBP57.7 million, Germany at GBP53.8 million, the Netherlands at GBP49.3 million and Belgium at GBP44.5 million.
Turkey was another large iron and steel importers to the UK outside the EU28 in October at GBP86.1 million, the data showed.
Iron and steel imports for the January-October period rose 26.7% year on year to GBP7 billion.
The UK’s nonferrous metal imports in October edged 1.1% lower year on year to GBP1.15 billion, which was 24.4% higher month on month, according to the statistics.
The UK’s main nonferrous metal importer was the EU at GBP487 million, rising 21.4% year on year, but down 0.8% month on month.
Top EU suppliers were Germany at GBP131.05 million and Belgium at GBP103.4 million.
The UK also received GBP111 million worth of nonferrous metals from Switzerland and GBP166.3 million from South Africa in October.
Nonferrous metal imports for the January-October period dropped 19.9% year on year to GBP12.4 billion.
The country’s imports of metal ores and scrap totaled GBP407 million in October, climbing 13.1% year on year, but down 23.8% from September.
The metal ores and scrap were imported mostly from the EU at GBP180 million, jumping 73.1% on the year and up 10.4% month on month, with GBP110.1 million coming from Germany.
The UK’s metal ores and scrap imports for the January-October period fell 6.1% year on year to GBP4.5 billion.
Imports of coal, coke and briquettes for October totaled GBP219 million, up 87.2% year on year, but down 2.7% month on month, with South Africa the top supplier at GBP61.4 million, followed by Australia at GBP35.7 million.
This brought January-October imports of coal, coke and briquettes to GBP1.9 billion, climbing 139.3% year on year.
Imports of miscellaneous metal manufactures for the month totaled GBP1.2 billion, up 16.4% year on year and rising 6.9% from September. The January-October total was GBP11.8 billion, up 24.5% year on year.
— Jacqueline Holman
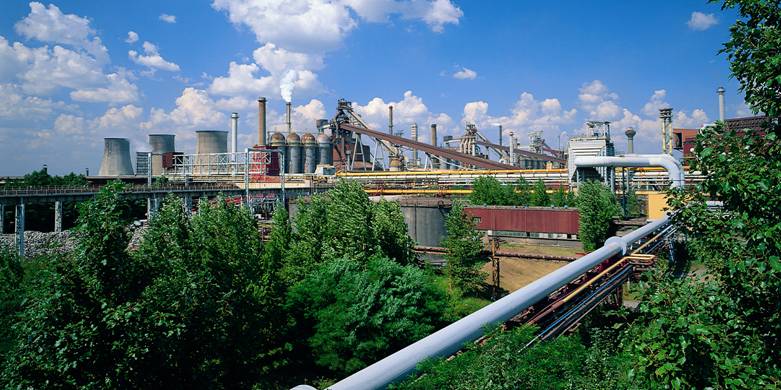
ArcelorMittal Poland postpones Dabrowa Górnicza BF restart amid still-weak market fundamentals
ArcelorMittal Poland has postponed the restart of its blast furnace (BF) No3 in Dabrowa Górnicza due to poor market fundamentals, Fastmarkets heard on Tuesday December 13.The company idled BF3 in September amid high costs and weak demand for steel products, Fastmarkets reported.
According to several market sources, the blast furnace was expected to be restarted in December, however ongoing weak steel demand, high production costs and high levels of steel imports into the EU have made the restart impossible this year, the company said.
“We have been closely observing the market, the forecasts in terms of a possible raise in demand, the long-awaited improvement of European activity. Unfortunately, this is not yet happening. And we do not see any signs of market recovery in the coming weeks. We still see that our order book continues to be at a level that remains below the minimum working point of two blast furnaces,” the company’s spokesperson told Fastmarkets.
“We continue to be prepared for a restart of BF3, however the exact date will depend on the market situation,” the spokesperson added.
The Dabrowa Górnicza site operates two BFs with a combined capacity of 2.7 million tonnes per year of pig iron. Only BF2 will remain operational at Dabrowa Górnicza before the end of 2022.
Dabrowa Górnicza steelworks has installed capacity to produce 5 million tpy of crude steel. The company can manufacture 3 million tpy of steel slab and about 3 million tpy of billet and bloom. Dabrowa Górnicza also produces merchant bars and long rails.
The site has also supplied slab to ArcelorMittal’s rolling mills in Krakow since 2020, when the company permanently shut down the hot area there.

Published by: Julia Bolotova
