


Beltrame Romania announces rebar prices while mill revamp continues: CEO
European long steelmaker Beltrame Group has received all certifications and technical approvals required to sell rebars from its newly acquired Donalam SBQ rolling mill in Targoviste, Romania, and has announced price levels, Beltrame CEO for Romania and France Carlo Beltrame told S&P Global Commodity Insights Sept. 20.
Beltrame estimated the sale price of the rebar at Eur900-940/mt ($899-939/mt) ex-works Romania, taking into account the current economic context.
“We have decided on this price range in particular after having taken into account the current electricity and gas prices,” Beltrame said.
Beltrame acquired the Targoviste plant in March with the aim of resuming local production of rebar steel.
The company also launched an investment plan to modernize the steel plant, which produces hot rolled steel bars and special steels for use in the construction sector.
Beltrame told S&P Global that the company had revamped rolling mills No. 1 and No. 2, which had restarted production in June and August, respectively, allowing it to produce around 40,000 mt of rebars by October.
The electric arc furnace was supposed to restart production by October, but this has been delayed to March or April 2023 due to high energy costs, Beltrame said, adding that the company was using billets shipped from the company’s other sites.
The new mill’s emissions are expected to be below the 50 kg CO2/mt limit, Beltrame said.
In July, the company pledged to invest around Eur300 million to build a 600,000 mt/year greenfield steel plant in Romania and a 100 MW solar farm.
The company’s board has yet to give the new investments the green light, which is expected by the end of September, Beltrame said.
Platts assessed TSI Northwest Europe rebars at Eur975/mt ex-works Sept. 16, up from Eur790/mt ex-works at the start of the year, but down from the intra-year high of Eur1340/mt ex-works on March 30, according to S&P Global data.
— Annalisa Villa


High stocks, limited demand, rising energy costs fuel negative sentiment in EU HRC market
Negative sentiment persisted in the European hot-rolled coil market on Sept. 20 while trading activity remained minimal and mills failed to transfer surging energy costs onto steel prices.
Platts assessed hot-rolled coil in Northwest Europe at Eur740/mt ex-works Ruhr on Sept. 20, unchanged day on day.
The lowest HRC prices in the region have been heard in Germany at Eur720-750/mt ex-works Ruhr.
“Germany accumulated most of the coil stock in the European market and when it comes to the commodity coil, distributors struggle to move stocks down,” a German distributor said.
Prices in other regions of Northern Europe have been reported between Eur740-800/mt ex-works.
Surging energy costs have had limited impact on HRC produced by steelmakers operating blast furnaces, but the cost of downstream coil production has sharply risen, reaching around Eur200/mt for HRC transformation into CRC. The cost was even higher for coated flat steel. As a result, some mills preferred to focus on HRC sales. This partially offset the positive impact from the production cuts introduced by European mills.
In addition, rising energy prices hit service centers and forced them to operate at reduced rates and therefore, consume less steel, market sources said.
“The market is very calm, nobody is interested in making deals now as distributors are sitting on high volumes of material they need to get rid of by the year end,” a service center said.
Demand from end-consumers has also been below usual for this time of the year, according to market sources.
“There is some activity in end-consumers, but to be honest, it is far from normal, and it would not solve a problem of high stocks this year,” a German source said.
Platts assessed hot-rolled coil in the south of Europe at Eur760/mt ex-works Italy Sept. 20, up by Eur5/mt day on day.
No deals have been reported. Tradable values have been heard at Eur750-770/mt ex-works Italy.
Italian steelmaker Arvedi planned to stop production at its Cremona plant this week due to high energy costs and weak demand.
Platts is part of S&P Global Commodity Insights.
— Maria Tanatar
BF decarbonisation necessary but will take time: Basson
Saudi Arabia will find it much easier than other regions to roll out hydrogen-direct-reduced-iron-route steelmaking but a solution will still need to be found to decarbonise blast furnaces globally, says worldsteel director general Edwin Basson.
At last week’s Saudi International Iron & Steel Conference in Riyadh, for which Kallanish was programme partner, Basson said Saudi has the right conditions to accelerate hydrogen-based DRI-EAF steelmaking development. However, this route alone will not be able to produce enough steel to meet global demand.
A solution must therefore be found for making low-carbon steel in blast furnaces, which will take a lot of time and research and development, Basson noted.
Also important will be the efficiency of how steel is used. Particular attention must be paid to the way buildings are designed for easy deconstruction and re-use of steel, Basson concluded.
Adam Smith Poland


Vallourec forecasts continued growth this year
French pipemaker Vallourec continues to foresee positive market dynamics thanks to higher drilling and OCTG prices, driven by global demand recovery and the inflationary environment, the company says in an investors’ presentation obtained by Kallanish.
Thanks to continued improvement in its tube division, particularly in North America, which is forecast to offset lower performance at Vallourec’s iron ore mine, the firm is targeting increased Ebitda this year in a range of €650-750 million ($648-748m). However, “with normalised iron ore mine production, Ebitda would have been approximately €1 billion in 2022,” the company says.
Vallourec continues to enact a drastic transformation plan. With its financial restructuring now completed, it reports a €1.7 billion debt reduction and the refinancing of residual debt with five-year maturity. The pipemaker is pursuing a “strategy of value over volume via reduction of 700,000 tonnes of unprofitable rolling capacity in Europe” transferring some of its European output to low-cost production regions, it says.
In 2021 and 2022, Vallourec divested its non-core assets, which include Valinox Nucleaire and Vallourec Bearing Tubes. It rationalised its European output by shutting down its German and some French assets, and transferring its O&G activities to Brazil. It acquired the minority interests in its strategic assets in VSB, Vallourec Star and VAM USA in 2021. Such actions have led to the full ownership of Brazilian and North American assets (see Kallanish passim).
The firm says it now benefits from a “stronger balance sheet and simplified organisation”. By 2024, the firm will reach a 750,000 tonnes/year steel and rolling capacity in North America, and 950,000 t/y steel capacity and 1.1 million t/y re-rolling capacity in South America. In China, it plans to reach 600,000 t/y of re-rolling capacity.
The group’s first-half-year revenue stood at €2 billion, up 33% year-on-year, driven by the price mix effect and sales volume hike in the Oil & Gas division in North America and EA-MEA. H1 Ebitda stood at €205m versus €228m in H1 2021.
Natalia Capra France
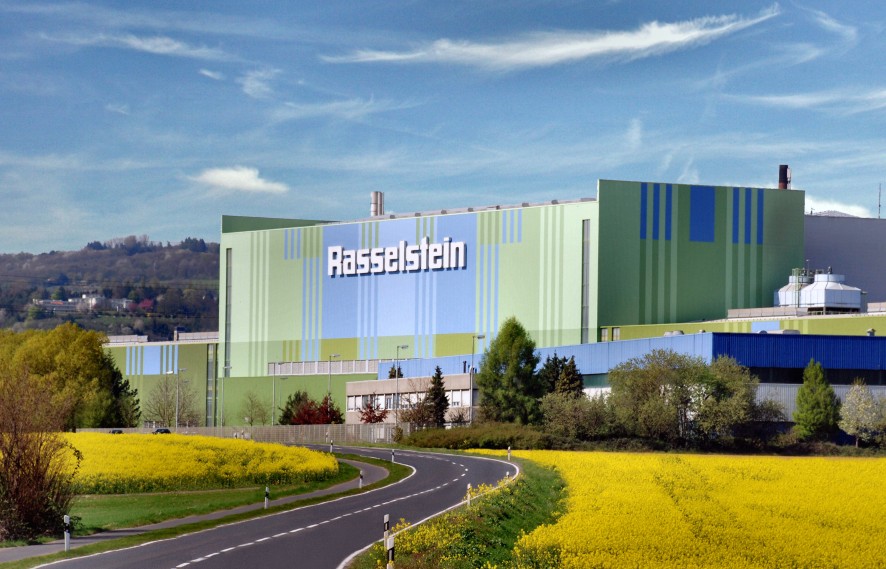
Thyssenkrupp Rasselstein starts new tinplate coating line
After three years of construction and an investment of €120 million ($120m), thyssenkrupp Rasselstein has commissioned its tinplate coating line 13.
The new plant uses chromium(III) in the manufacturing process instead of the chromium(VI) previously used, Kallanish learns from the company. Thus, the new manufacturing process fully complies with the requirements of EU REACH regulation. The new production plant is the largest single investment at the Andernach site in around 15 years.
The new coating line enables the chrome-plating of even wider and thinner sheets, the company explains. It claims that, technologically, line 13 is the most modern plant of its kind – also because more efficient and energy-saving processes are realised with a digitalised workflow. Chrome-plated material is used for lids and bases for pet food cans, valve disks on aerosol cans, crown corks or printing ink cans.
“This major investment marks an important and very special milestone in the history of thyssenkrupp Steel,” says Bernhard Osburg, chief executive of Rasselstein parent thyssenkrupp Steel. He adds that the world’s largest production site for packaging steel adheres to the highest sustainability standards.
Christian Koehl Germany
Metinvest Italian mills secure Europe, Asia slab supply
Metinvest’s Italian plants are receiving slab feedstock for rolling from European, Asian and Latin American suppliers, says the company’s general director, Yuriy Ryzhenkov.
“Semi-finished products are also coming from Zaporizhzhia, where one of the group’s assets – the Zaporizhstal plant – is located,” he noted in an interview with Ukraine’s NV newspaper. “Before the full-scale Russian invasion of Ukraine, the company’s Italian enterprises received slab from Azovstal in Mariupol, which now is occupied.”
According to Ryzhenkov, the enterprise is now buying slab in Southeast Asia, looking at Brazilian slab and also purchasing European slab, including from Acciaierie di Italia. Negotiations are also underway with US Steel Kosice and Liberty Steel, he adds. “We are looking for slab in small batches,” Ryzhenkov observes.
The process of setting up production of slab is still ongoing at Zaporizhstal. “This is a rolled slab, but we already have the first successes. We make an ingot from converter steel at Kametstal; after that we roll it into a slab at Zaporizhstal,” he explains. The slab then goes to European units for rolling.
In addition, Ryzhenkov talked about the situation with the supply of coke to Ukrainian plants. Following the shutdown of the Avdiive coke plant, Metinvest is using other available capacities for its production. In particular, there are two plants in Kamiansk and one in Zaporizhzhia.
“There are two more coke plants, where we deliver our coal for processing – ArcelorMittal in Kryvyi Rih and the former DMZ in Dnipro,” the general director says. “At the current steelmaking utilisation, we have enough of these capacities. If we increase production, we will have to look for additional coke.”
Earlier this month, Metinvest delivered a new batch of Italian hot rolled coil to its metal centre in Ternopil, Ukraine from its Italian subsidiary Metinvest Trametal SPA (see Kallanish passim).
In August, the Ukrainian steelmaker arranged the import into Ukraine of scarce thick plate and HRC from its assets in Italy. The total volume of planned deliveries to Ukraine is about 3,500 tonnes.
Svetoslav Abrossimov Bulgaria

Low steel demand brings down Spanish scrap prices
Spanish scrap prices are seeing a downward correction, Kallanish learns from local market sources. After reaching a three-month high in the last days of August, prices have so far fallen €20/tonne ($19.95/t) in September. This trend is set to continue as values are impacted by softening domestic demand, production cuts at certain large mills, and a relatively quiet international scrap market.
“The deceleration of local demand could force Spanish prices to move down a further €30/t in the week,” a local merchant says. “It is difficult to predict how the market will evolve by the end of this month. What is really certain is that the planned shutdown of one of ArcelorMittal’s two blast furnaces in the Asturias region since 28 September will further worsen the already difficult situation for the Spanish steel industry and consequently the scrap supply chain, which is forced to lower its prices.”
Spanish scrap prices are also expected to fall to align with lower international market levels, another source comments. “Turkey does not have much demand and prices in Europe are still higher than they are there, so it is understood that scrap levels will drop by at least €30/t in the next weeks. This adjustment equals the difference in freight we have compared to Turkey,” says a market participant.
New E8 quality in the domestic Spanish market is now offered at €410/t delivered. E40 and demolition quality grade (E3) are at €360/t and €345/t delivered, respectively. E1 quality is delivered at €290-300/t.
Todor Kirkov Bulgaria

Benelux scrap market questions price recovery
Market participants in the Benelux are seen questioning a possible price recovery following an EU-origin scrap deal in Turkey.
On Friday, a western long steel mill bought an EU-origin cargo comprising 18,000 tonnes of HMS 1&2 80:20 at $344/tonne, 12,000t of shredded at $364/t and 10,000t of bonus grade at $364/t cfr Turkey.
Compared to the latest UK-origin HMS 1&2 80:20 deal done at $342/t cfr by the same producer the previous week, this new European deal points to a recovery in prices.
However, although suppliers are interpreting this as an increase in prices, most market participants in Turkey question if other mills will also accept paying these values as most were resisting prices above $340/t cfr and preferred to wait.
A Turkish mill tells Kallanish: “The producer might have paid this price due to the high tonnage of shredded and bonus in the cargo. If this was just an HMS 1&2 80:20 cargo, no one would accept to pay this price.”
Another mill says: “I think scrap should be at around $300/t cfr levels. When you look at the prices of billet and slab in the international market, obviously Turkey has no competitive power with the current finished and semi-finished steel prices.”
A Benelux scrap supplier comments: “I agree that steel sales are not doing well but, on the other hand, collection is interrupted at these prices due to higher collection costs. Scrap prices cannot fall further.”
Dock prices in the Benelux, meanwhile, decreased to €275-290/t ($275-290) delivered on Monday, down from €285-295/t on Monday last week. Material flow, however, remains quite weak at these levels.
In the Indian sub-continent, demand for scrap remains subdued, putting pressure on prices. While the Pakistani economy is suffering in the aftermath of flooding, weak finished steel demand and the arrival of previously booked bulk cargoes in India are hampering new scrap demand. Containerised shredded offers were seen standing at $440-450/t cfr Nhava Sheva on Monday.
Burcak Alpman Turkey

Thyssenkrupp to build new metals service center in Mexico
Thyssenkrupp Materials Services will invest $37 million to build a new metals service center in Mexico that will serve automotive customers in North America, the company said Sept. 19.
The new site in San Luis Potosí, which is expected to start operations in mid-2023, will specialize in supplying lightweight steel and aluminum products to support lower-emission automobiles and electric vehicles, according to a statement. Products will include aluminum and high-strength steel blanks that will be cut at the plant’s Schuler blanking line, Thyssenkrupp MS added.
“The needs and requirements of the industry are changing rapidly,” CEO Martin Stillger said in the statement. “Against the background of the major transformation themes of electro-mobility, sustainability, and supply chain resilience, Mexico is a clear growth market for us.”
Thyssenkrupp MS, a subsidiary of diversified German industrial group Thyssenkrupp, said the project in Mexico represents a key expansion of the company’s footprint in North America, where it has invested over $100 million in the last 12 months.
The materials and service provider already operates three service centers in Mexico located near automotive OEMs and automotive industry suppliers. The company’s new San Luis Potosí location and existing Silao service center will be the only facilities in the country to offer aluminum blank cutting services, according to the company.
Parent company Thyssenkrupp also operates steelmaking assets in Europe.
— Nick Lazzaro
Polish rebar mills cut offer prices to stimulate buying activity
Steel rebar prices in Poland declined modestly in the week to September 16, with producers starting to give discounts to try and encourage buying activity, sources told Fastmarkets.
Fastmarkets’ price assessment for steel reinforcing bar (rebar), domestic, exw Poland, was 4,200-4,300 zloty ($889-910) per tonne on Friday, down by 50 zloty per tonne from 4,250-4,350 per tonne on September 9.
Rebar offers from two local producers came in at 4,200-4,300 zloty ($922-932) per tonne delivered exw during the assessment week, down from 4,300-4,350 zloty per tonne exw the previous week.
Deals, however, were done closer to the lower end of the price range, sources said.
In the secondary market, rebar was offered and traded at 4,350-4,400 zloty per tonne delivered, down from about 4,400 zloty per tonne delivered seven days ago.
Weak demand for rebar from end-users continued to undermine buyer confidence, sources said.
“The problem is that the real demand [for rebar] is very weak – there are no big projects under construction,” one trader said.
He also suggested, however, that the impact of surging energy costs on the steel sector might not be as dramatic as expected, due to anticipated aid from the Turkish government.
“There are [suggestions] that energy consuming industries will get some aid from governments to make up for surging energy prices,” he said.
In addition, falling scrap prices in Europe and elsewhere have been putting pressure on rebar prices in Poland.
Market participants told Fastmarkets they expect domestic rebar prices in Poland to sink even lower in October.
“We expect to offer October rolling rebar at 4,150-4,250 zloty per tonne [delivered],” another trading source in Poland told Fastmarkets.
Published by: Julia Bolotova
