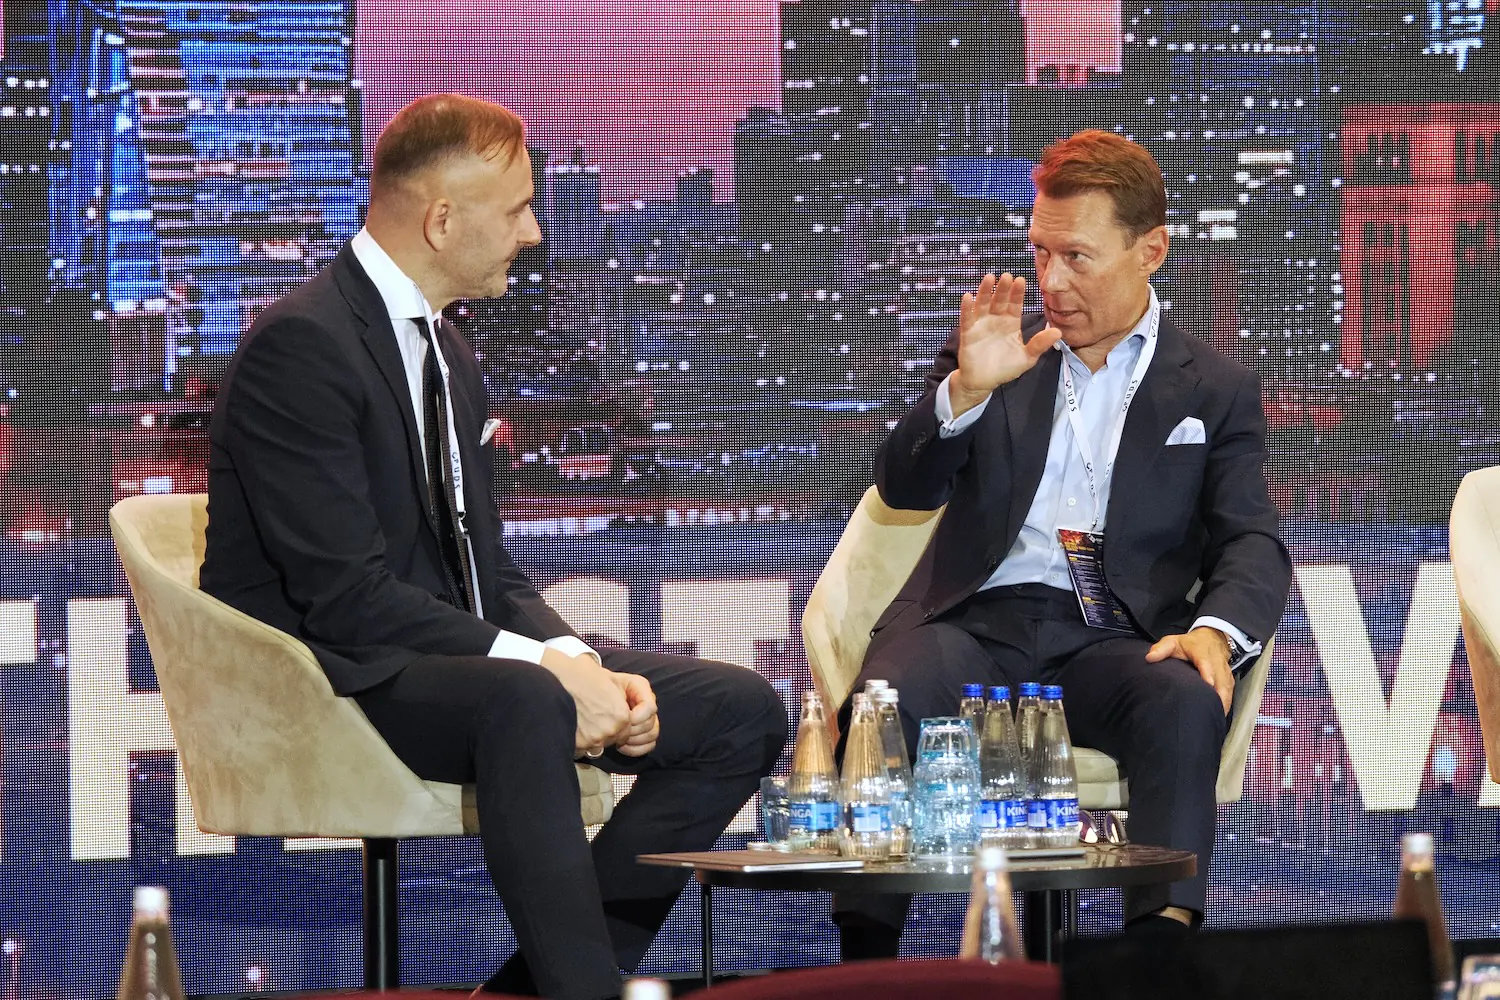
Europe will need to go in the direction of the United States to protect its entire steel value chain if it wants to keep manufacturing, jobs and wealth within Europe, while authorities should commit to implementing melt and pour, said panellists at the EUROMETAL Regional Meeting Central Europe in Warsaw on Wednesday.
Much of the discussion centred around the need to extend CBAM and tariff-rate quotas to downstream, steel-containing manufactured goods, a message Eurometal drove home a week earlier during its rally in Brussels.
“If we want to have a fair Europe, that means we will end up similar to the United States … We will need to focus on Europe as a sales market but it also means we will need to close our doors completely. Not only … on the raw material side when we talk about steel, but also on the product side. At least we are saving the manufacturing jobs here in Europe. That means we can still live with the value chain in Europe,” EUROMETAL president Alexander Julius said at the event attended by Kallanish.
Steelmakers are more aware than ever before about the need to secure the whole value chain in Europe, added Eurofer deputy director general, international affairs Karl Tachelet. Integrated steel production in Europe is no longer sustainable. But the continent has a big manufacturing industry and market, plentiful scrap supply and high-tech steel production capability that it should utilise, he added.
Trade barriers support supply but “what about the demand? What about our customers? What about steel use?” he asked. The European Commission should be applauded for recognising this and introducing a provision to expand the scope of measures, he added.
Julius added that in recent discussions, an EU mill official revealed that 80% of the firm’s steel is being sold in a range of 500km. “If the demand is fading away, that means if it’s being replaced by incoming [imported] products, then there is no need to keep up these steelmaking capacities [in Europe],” Julius pointed out.
European export competitiveness is yet to be addressed by any measure, however. Based on the EU’s cost-competitiveness, if it wants to continue exporting steel, this will likely be limited to niche products like tin mill products and electrical steel that the US does not make sufficient quantities of thus far.
However, these products are “not representing the mass steel sector. So, honestly speaking, countries like China have covered the world already with exports. So … it’s more than naive to think that we can really be competitive in those markets,” Julius warned.
As for melt and pour, although “it makes sense” to prevent circumvention, there is no firm commitment yet from European authorities to introduce the clause. Tachelet noted. Their attitude is “we are open for bringing in melt and pour as a principle of quota allocation, but not yet. Let’s see what the monitoring tells us,” he added. The European Commission has to be convinced to “take the second step”.
Sławomir Czajka, EY, partner remarked of the CBAM regulation: “We’re kind of building the plane while we fly it”. Nobody except “the large multinationals that have … big teams of lawyers” probing suppliers will be able to use actual emissions data for their CBAM calculations. “All the mid-cap companies are not ready to use the … actual emissions data to calculate CBAM. We will use the default values, which we know are … higher.” He added CBAM is “one of the most complex ones [systems] we have in the EU, and it’s not getting stricter. I’m afraid.”
Author: Adam Smith