


EUROMETAL participated in a visit to the Liège tramway terminal


Last Tuesday, June 14th, Infosteel organized a visit to the Liège tramway terminal in Bresseux.
The City of Liège will have a tram serving 23 stations. On the Bressoux site, at one end of the route, are located the maintenance center, the washing station, the tram storage center and a P+R car park.
The 4.200 m2 maintenance center is a metal structure of approximately 300 t made up of gantries supporting runways and maintenance walkways.
The 3.900 m2 storage center is 234 m long for approximately 150 t and consists of metal beams resting on one side on a metal column and on the other against a concrete building of the P+R car park.
The washing station is made up of concrete walls raised by steel columns and beams supporting the roof sheets and the glazed frames. Railings and steel walkways complete the set.
In addition to the economic and aesthetic nature of the material, the choice of a steel structure was logical due to the ease and speed of implementation.
In this event, participants were welcomed at the Public Transport Museum of Wallonia, where they attended presentations made by InfoZinc (Mr. Bruno Dursin), TEC/Tram of Liège (Mr. Daniel Wathelet), Architecture office Greisch – BAG (MR. Pierre-François Geenen), Lemaire design office (Mr. Hugues Wilkin) and Ateliers Mersch (Mr. Thierry Mersch).
Active in Belgium and the Grand Duchy of Luxembourg, Infosteel focuses on promoting the qualitative use of steel in construction.
During these site visits Infosteel tries to bring together and connect people from all steel sectors: the steel industry, construction companies, design and architecture offices, surface treatment manufacturers, traders, software companies etc.

European flat steel prices stable to softer amid zero activity
The downstream prices for steel coil products across Europe have been stable or slightly weaker over the past seven days, although buying interest remained weak, sources told Fastmarkets on Wednesday June 15.
Continued weak demand from end-user sectors, notably the automotive and white goods industries, have been putting pressure on prices for both cold-rolled coil (CRC) and hot-dipped galvanized coil (HDG) across the region.
Due to lower order intake from consumers, distributors still had quite high inventories of CRC and HDG, sources said.
“There is no point in cutting the price because it wouldn’t help to revive buying activity,” a mill source in Germany told Fastmarkets.
CRC
Fastmarkets’ weekly price assessment for steel cold-rolled coil, domestic, exw Northern Europe, was €1,050-1,070 ($1,095-1,116) per tonne on Wednesday, narrowing downward by €10 per tonne from €1,150-1,200 per tonne a week earlier.
Buying interest for CRC in the region was minimal, with very few transactions completed recently, sources said.
Offers from mills in the region were reported at €1,070-1,080 per tonne exw, while buyers estimated the workable level to be no higher than €1,050 per tonne exw.
“The market is still oversupplied. The level of stock is reducing very slowly,” a distributor in Germany told Fastmarkets.
The market fundamentals in Southern Europe were similar.
Fastmarkets’ weekly price assessment for steel cold-rolled coil, domestic, exw Southern Europe, was €970-1,000 per tonne on Wednesday, widening downward by €30 per tonne from €1,000 per tonne a week earlier.
CRC offers from mills in Italy were heard at €1,000 per tonne exw, but producers were ready to give discounts to secure transactions.
The real demand, however, was very poor in the region.
“The demand for downstream steel in Italy is completely dead [with] almost no sales done,” a steel service center in Italy told Fastmarkets.
HDG
Fastmarkets’ weekly price assessment for steel hot-dipped galvanized coil, domestic, exw Northern Europe, was €1,080-1,090 per tonne on Wednesday, narrowing downward by €10 per tonne from €1,080-1,100 per tonne a week earlier.
One transaction for a limited tonnage was heard in Germany at the lower end of that range during the week, although some HDG offers were still heard at €1,090-1,100 per tonne exw from mills in the region.
Fastmarkets’ weekly price assessment for steel hot-dipped galvanized coil, domestic, exw Southern Europe, was €1,000-1,050 per tonne on Wednesday, down by €30-50 per tonne from €1,050-1,080 per tonne last week.
The assessment was based on deals, offers and buyers’ estimates of achievable prices during the week.
Published by: Julia Bolotova

Italian re-rollers update price lists
Italian re-rollers are updating their welded tube price lists, adapting values to the new reduced average prices of hot rolled coils and freight costs, Kallanish learns from local tubemakers.
Many re-rollers are reducing tube prices but increasing and adapting transport costs that remain extremely high on the domestic and European markets. The new June price lists are effective this week, Kallanish is told.
Large re-roller Marcegaglia is also updating its June price lists for both welded tubes and black, pickled, polished and galvanized strips. While the June list takes into account the revised price of HRC, it also shows an average 10% hike for transport costs in the domestic market and about a 15% increase for shipping material to the rest of Europe.
Demand for welded tubes is currently weak in Europe particularly from certain sectors such as automotive. Tubes prices however are seen reaching rock bottom possibly in July.
Natalia Capra France

EU steel sections prices continue to drop amid quiet demand, weak scrap
European domestic steel sections prices continued to soften in the week to June 15, as buyers held back from booking orders expecting prices to move further down.
Platts’ European medium sections price (category 1, S235 JR) was assessed at Eur1,350/mt delivered June 15, down Eur10/mt on week.
One Benelux-based distributor source put mill offers for beams around Eur1,350/mt delivered but indicated that it might be possible to book tonnages like 500 mt and above around Eur1,300/mt delivered. The source noted that demand was extremely weak in the market and mills were willing to accept any counteroffers they receive. Meanwhile, buyers were not in a hurry to buy as prices seemed to be trending lower.
Another distributor in the Benelux region noted that prices for long steel products were following movements in scrap levels, highlighting that scrap prices in Europe had decreased significantly since the end of May.
“There is demand, but people are careful because prices are moving lower,” he said, adding that buyers are being cautious and only buying what they need.
The source put a tradable value for medium sections category 1 at Eur1,300/mt delivered, depending on the mill.
“No transactions are happening in the market,” one European mill source told S&P Global, adding that the last deal the mill booked during the week starting June 13 was at around Eur1,370/mt delivered. The source also put mill offers for medium sections category 1 at Eur1,400/mt delivered, while buyers were asking for Eur1,350/mt delivered. He noted that along with weak demand, softening scrap is also putting pressure on prices.
In Northern Europe, Platts’ June assessment for domestic shredded scrap was at Eur397.50/mt delivered June 10, down sharply from Eur500/mt in May. The assessment for Southern European shredded scrap was at Eur400/mt delivered to the mill for June on June 10, down sharply from Eur510/mt delivered in May.
Elsewhere, Northwest European domestic rebar prices also softened week on week to June 15. Platts TSI Northwest Europe Rebar was assessed down Eur10/mt to Eur1,165/mt ex-works June 15.
— Rabia Arif, Staff

EU downstream coils market optimistic on positive automotive demand
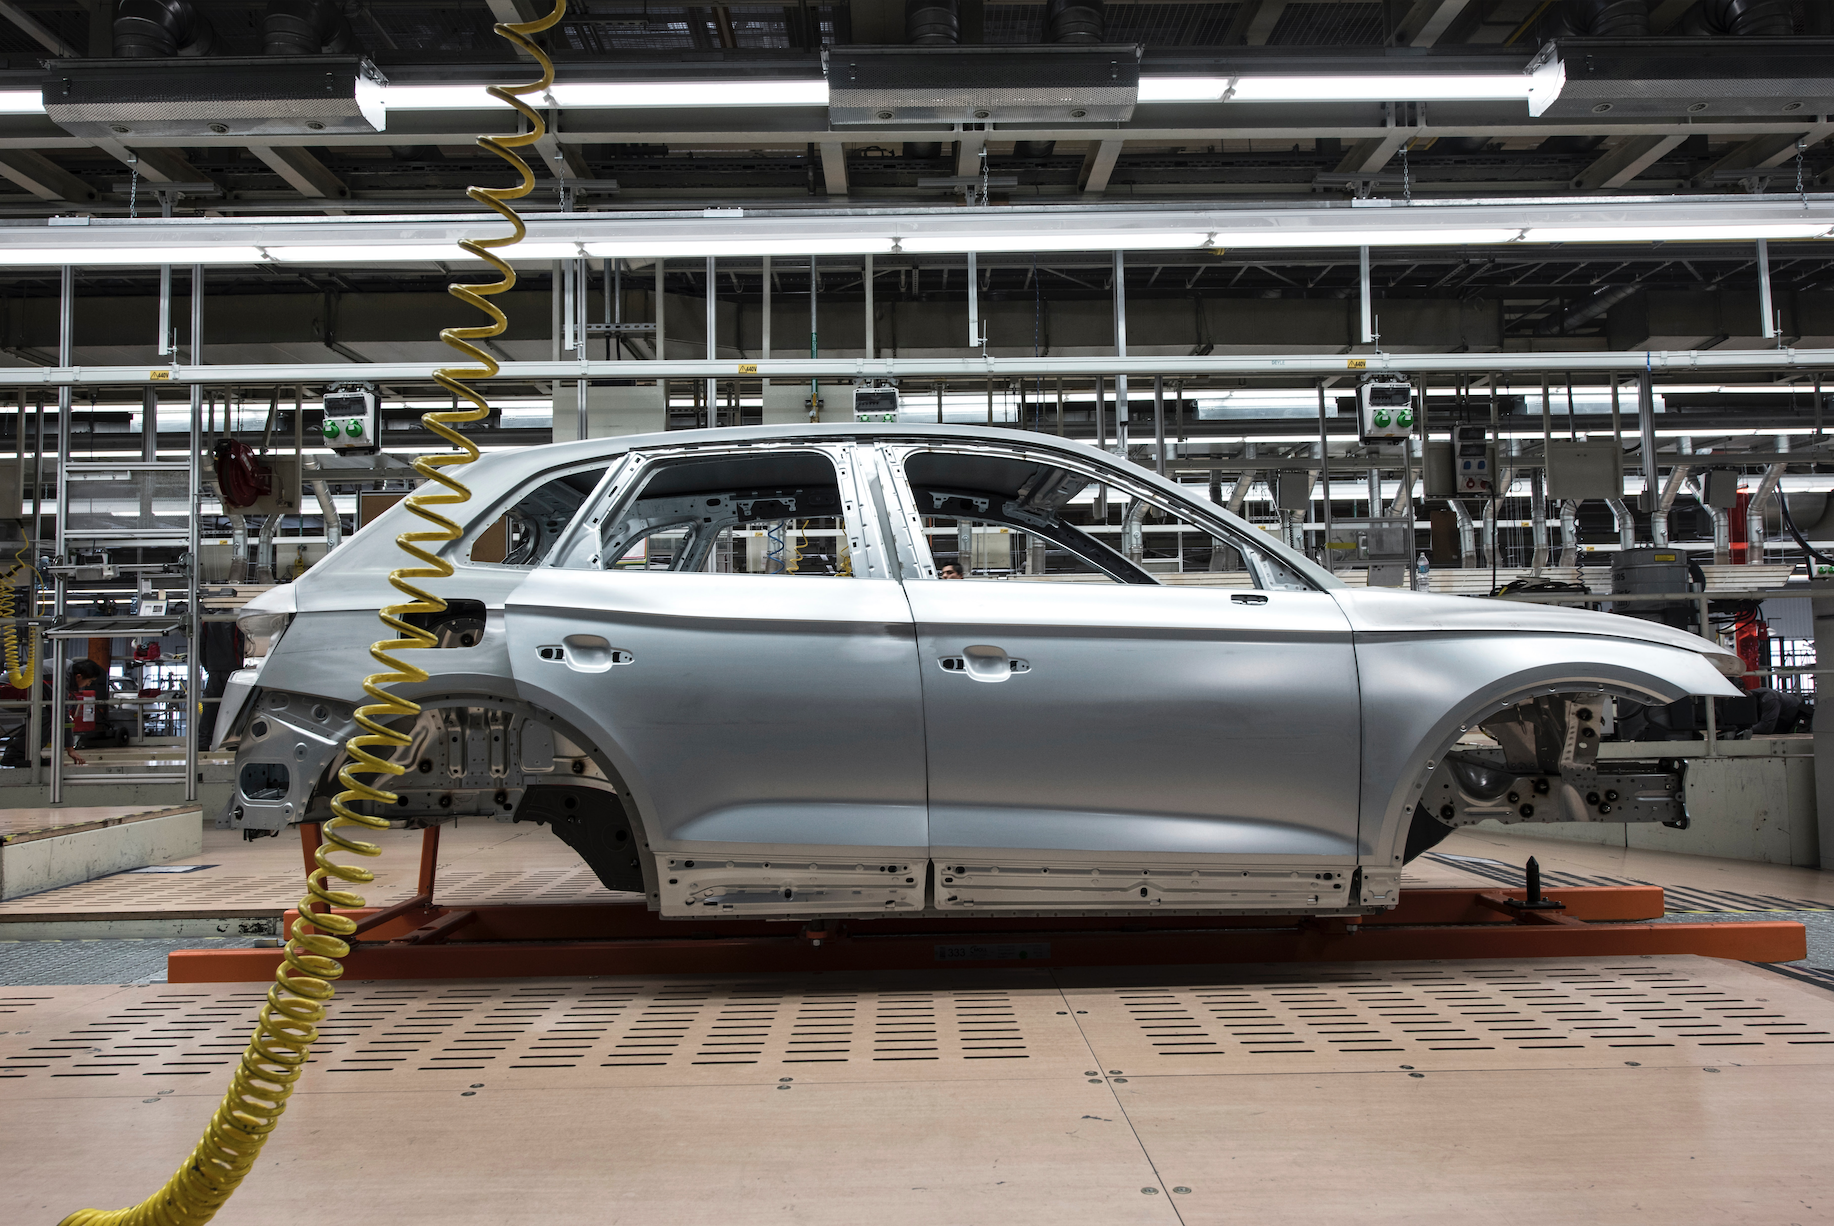
Sources reported positive signs from the automotive sector June 15, and downstream coil prices fell further on scarce transactional activity.
General demand for downstream coils remained muted June 15 as buyers refrained from restocking against high inventories and pricing downtrends.
For cold-rolled coil, Northern European prices fell Eur25 on the day to Eur1020/mt ex-works Ruhr. Italian CRC followed the slide, assessed down Eur65 on the week at Eur960/mt ex-works Italy.
Galvanized material also moved lower across Europe on muted demand, assessed in Northern Europe at Eur1,075/mt ex-works Ruhr, down Eur45 on the week. In the Southern market, HDG fell Eur50 to Eur1,000/mt from Eur1,050/mt ex-works.
Despite little transactional activity heard in the wait-and-see market, sentiment was more optimistic given signs of recovery from the automotive sector. A trader source reported semi-conductor supply chain issues were largely resolved, but emphasized that positive demand from OEMs had to be regarded on a case-by-case basis. The source heard one large automotive company was approaching factories directly, increasing production levels to near-full capacity.
A mill source agreed that indications could not be taken for granted.
“There are mixed messages in the market, but on our end automotive is looking absolutely positive,” the mill source said. “The sector hasn’t been as reliable as we would like in previous years, but the signs of recovery are there, demand for forward volumes is looking good – though negotiations are still ongoing.”
The same source reported production capacities were sufficient for current demand due to planned maintenance and improvement projects postponed from 2021. Downstream coil prices were heard to be particularly sensitive to automotive demand, making the return of the sector the key to market stability.
General stockholder demand had all but collapsed given high stock levels in the market due to panic buying and logistical delays in receiving import material, a trader said. The source had not received inquiries for imported downstream material for some time, with apparent demand expected to decrease even further into the traditionally quieter summer period.
— Benjamin Steven, Maria Tanatar
Northern European HRC producers cut prices to settle deals
Northern European steelmakers decreased hot-rolled coil prices on June 15 in an attempt to spur buying activity in slow market.
Platts assessed HRC in Northern Europe at Eur900/mt ex-works Ruhr, down Eur30 day on day, according to data from S&P Global Commodity Insights.
Few deals have been reported at Eur900/mt ex-works Ruhr. Market participants estimated achievable prices at Eur890-950/mt ex-works Ruhr, but the majority of the sources reported prices of Eur890-910/mt ex-works Ruhr.
The market had mixed outlooks on sentiment — some participants believed that the prices had moved close to bottom, while others claimed that, as demand was unlikely to see substantial recovery, prices would drop further.
“Market price is at bottom already, at Eur900ish/mt ex-works,” a producer said. “Steel mills need to be smarter this time and not drop prices further.”
Bids, however, had already been reported at Eur800-850/mt ex-works Ruhr.
“Buyers are in wait and see mode until prices reach bottom,” a German distributor said. “And there is no rule that the bottom should be at the price at which mills still would get margins.”
Although demand remained low, more buyers have been showing more interest in making deals to restock. The demand revival, however, was unlikely to be strong enough to support domestic HRC prices.
“Demand expected to revive in July, buy predicted restocking constantly delayed, hard to make predictions in wait and see market when prices in freefall and demand so low,” a Northern European trader said.
Volumes consumed by the automotive industry – a key end user for coil – were expected to be substantially below normal volumes in 2022 due to components shortages putting strains on car manufacturing.
Steelmakers aimed to finalize negotiations with carmakers for the third-quarter and the second-half 2022 contracts by the end of June.
Lower import prices have also been contributing to the bearish sentiment in the market.
Offers of HRC from Taiwan have been heard at Eur850/mt CFR Antwerp, down by Eur20-30 compared with offers from the end of the prior week.
Hot-rolled coil in Southern Europe was assessed at Eur850/mt ex-works Italy June 15, unchanged day on day.
The latest deals and achievable prices have been heard at Eur850/mt ex-works, but bids have been reported around Eur800/mt ex-works.
The next round of deals was expected to be settled at lower prices, as producers need to fill July order books, market sources said.
Import offers have been heard at Eur770-790/mt CFR Italy from Asia and Turkey, including anti-dumping duties. However, bids were reported at Eur750/mt CFR Italian ports.
— Maria Tanatar, Benjamin Steven

Be bold in your digital transformation: C4L and LCL conference


EUROMETAL participated in the conference “Digitalising logistics and supply chains to reinforce resilience” of the Cluster for Logistics and the Luxembourg Centre for Logistics and Supply Chain Management that took a good look at innovation and what to take into consideration when planning new projects.
The Masters of ceremony, Malik Zeniti, C4L Director, and Joachim Arts, Associate professor of the LCL welcomed over 50 guests on June 13th 2022 at the Chamber of Commerce Luxembourg.
One major takeaway, was that Luxembourg actors need to be bold in their vision but flexible in their implementation. Getting ready for the future is not just about digitization or digitalization but having a plan for a digital transformation: the process of devising new business applications that integrate all the digitized data and digitalized applications.
The presentations of the day included:
– Prof. Benny Mantin, Director of the Luxembourg Centre for Logistics and Supply Chain Management (LCL) launched the celebration of the five-year anniversary of the LCL and presented the team behind the Master program.
– “Leveraging topographical data to reduce carbon emissions and fuel consumption in transport” by Poulad Moradi Shahmansouri, PhD Candidate at the Luxembourg Centre for Logistics and Supply Chain Management.
– “Leveraging the CAVE Lab for data-driven decision making in logistics and supply chain management” by Professor Pascal Wolff, Professor at the MIT Global SCALE Network’s Ningbo China Institute for Supply Chain Innovation (NISCI)
– “Procurement in uncertain times: challenges, and is going digital an opportunity, or threat?” by Mr Marcel Dinu, Vice President, Vendor Management, Procurement and Supply Chain, SES Satellites, on their DP challenges
– “On platforms and digitalization of transportation procurement” by Mr David Waroquier, CEO of Shipsta, and dialogue with LCL PhD candidate Ms. You Wu, on a project in collaboration with Shipsta
– Keynote speech on “the Ups and Downs of Digital Transformation of Supply Chains” by Maria Jesus Saenz, PhD, Executive Director, MIT SCM Masters Programs Director, MIT Digital Supply Chain Transformation (online)
– Introduction and Presentation of the Survey Digital Transformation in Transport and Logistics by Mr Malik Zeniti
– “The untapped value of innovation in Supply Chain 4.0” by Mr Arnaud Lambert, Director at Luxembourg Digital Innovation Hub
– Practical Case: How digitalization can generate revenue using mobility devices: The LuxairCARGO case by Mr Francois Dolisy, Managing Director at 4i
– Practical Case: New trends in InfoSec, Cybersecurity, and Supply Chain Attacks by Dr Carlo Harpes, Managing Director at itrust
– Panel Discussion: The Ups and Downs of Digital Transformation of Supply Chains revisited moderated by Prof. Benny Mantin, Director of the Luxembourg Centre for Logistics and Supply Chain Management (LCL) with Mr Arnaud Lambert, Director at Luxembourg Digital Innovation Hub, Mr Francois Dolisy, Managing Director at 4i, Mr Christian Wilhelm, CEO at Shipsta, Dr Carlo Harpes, Managing Director at itrust.