


Hydrogen-based steelmaking’s adoption will depend on competitiveness: report
A research paper into the best use of hydrogen has suggested that its role in steelmaking should only be considered if it is the most competitive option for decarbonisation, Kallanish notes from the report published in the science journal Nature.
The paper highlights that research has begun to clarify sectors where hydrogen is unlikely to be competitive, such as home heating and light vehicles, and develop areas in which hydrogen has better prospects, such as hydrogen-based green steelmaking.
Available evidence suggests that support for clean hydrogen should be prioritised in unavoidable applications, such as petroleum refining and fertiliser production, and other competitive applications including steelmaking, long-haul heavy transport and long-duration energy storage. It adds that hydrogen strategies should prioritise and support these areas to achieve the greatest impact.
“Hydrogen’s versatility means that it can power many applications; however, clean hydrogen should be strategically deployed in areas where it seems likely to have greatest potential for cost and sustainability benefits compared with alternatives such as direct electrification with clean power sources,” it says.
“In the short term, renewable electricity could achieve greater emissions abatement if used directly to displace fossil fuels in power generation, heating or transport, instead of being used for green hydrogen production. In the longer term, hydrogen could instead facilitate renewables uptake by integrating excess generation into power systems,” it adds.
While the paper sees a rapid transition towards renewable electricity and battery electric vehicles, vital progress is slower in sectors where electrification alone cannot mitigate emissions, particularly in industry, shipping and aviation.
However, other options should be explored first, it notes. Technology-neutral policy designs, such as supporting clean steel or low-emission transport, should be adopted where possible, favouring hydrogen only when it has the potential to become the most competitive decarbonisation option.
It also highlights that while hydrogen holds potential in industry, long-duration energy storage and long-haul transport, its competitiveness depends on large-scale deployment yielding substantial cost reductions.
The paper adds that the climate impact of hydrogen production is uncertain, with production from electrolysis or methane gas with carbon capture potentially increasing system-wide or upstream emissions, alongside water scarcity and persistent organic pollution.
“Future research must resolve these uncertainties, with strategic focus on deploying hydrogen in priority areas where it is most competitive,” it says. It also notes uncertainty over which sectors will see the highest uptake of hydrogen with conflicting assessments of where it is best suited.
Carrie Bone UK


Germany faces zero growth in 2025
Germany’s economy will continue its flat development this year before possibly seeing growth of 1% in 2026, the German economy ministry says.
This means a downward correction from the modest 0.3% growth previously forecasted for 2025 and will make this year the third in a row without any growth, Kallanish notes. Export-driven German industries are suffering most from erratic US customs duties announcements and their global repercussions. The insecurity over international business relations comes on top of a lull in demand and lack of competitiveness due to high domestic production costs.
“The German economy faces great challenges, but it has stood that test before,” says outgoing economy minister Robert Habeck. “We have been in a crisis mode since 2020 – through Covid, the Russian aggression on Ukraine, energy prices and inflation. Now our next challenge is the unpredictable trade policy of the United States.”
The big task of the moment is finding a solution between the EU and US to settle the trade conflict. The EU must take a clear stance and not give in easily, and be prepared to impose effective counter measures, Habeck adds.
Private investment in Germany will remain subdued for now, but start recovering over the course of the year, possibly encouraged by the framework of the new government, the ministry says.
Christian Koehl Germany

Assofermet sees no recovery for service centre sales
Italian service centre sales of coil derivatives are not forecast to recover in April following a subdued March, Italian trade association Assofermet says in a market note seen by Kallanish.
Since April, the EU’s safeguard amendments have been enacted, which, in conjunction with both new and existing anti-dumping duties, are considered a considerable barrier to steel imports.
This will compel service centres to redirect a significant portion of their coil purchasing volumes towards EU producers, establishing the conditions for a rise in coil prices.
“However, it is important to ask whether the downstream sector, specifically the steel end-users, can sustain these elevated prices in light of the relatively weak demand, without compromising their competitiveness in international markets,” the association comments.
The ongoing trade conflict, especially between Europe and the United States, is generating significant apprehension. The potential impact could lead to a notable deceleration in the already complex recovery of steel consumption.
Confindustria, the association representing Italian industrialists, recently revised its economic growth projections for Italy, lowering the estimate to 0.4% for 2026 following 0.6% growth in 2025, Assofermet reveals.
The distribution sector remains under a cloud of uncertainty.
The performance of all steel product categories is predominantly negative, with the exception of seamless tubes. This product, however, accounts for a negligible portion of the sector’s sales volumes.
In March, sales of both flats and long products experienced a double-digit decline year-on-year.
However, welded tube demand has demonstrated resilience, with prices trending upward.
The tariffs implemented by the US administration are likely to negatively impact the investment strategies of end-use sectors, particularly in agriculture and mechanical engineering, Assofermet concludes.
In a recently released position paper on the enhanced protectionist policies by the US, Assofermet stated the trade war could potentially lead to significant market distortions for Europe. The execution of US policies may lead to an important redirection of global steel exports to the EU, potentially prompting it to consider countermeasures aimed at Asian countries.
Natalia Capra France
EU end-users need protection, industry firmer action: conference
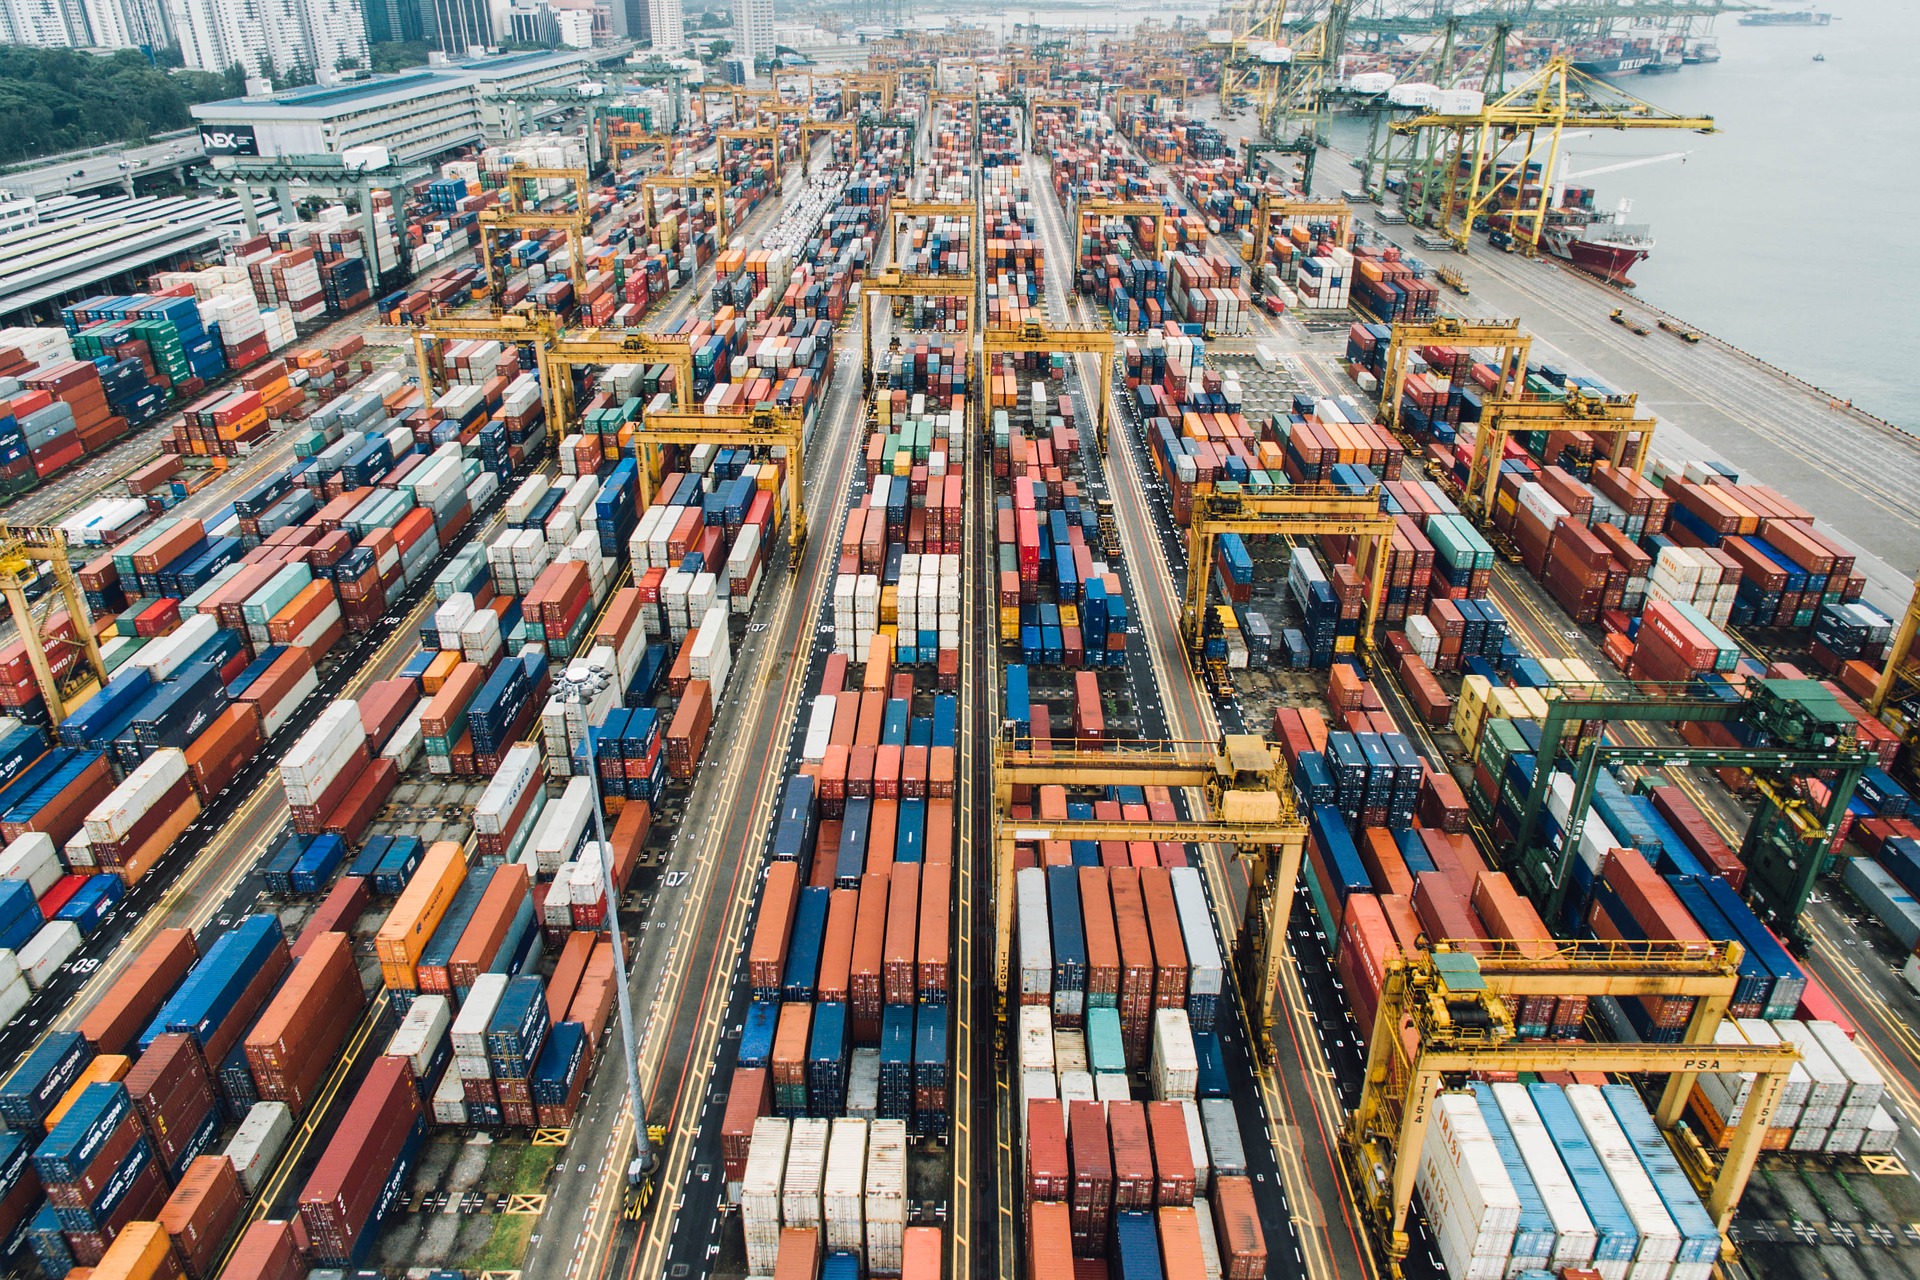
EU protection against imports must be extended to downstream steel-using goods to avoid the collapse of Europe’s end user industries, while the government, although now finally taking steelmaking seriously, must move immediately to save the industry, concluded Polish industry representatives during Friday’s European Economic Congress in Katowice.
Opinion was however mixed on whether governments need to nationalise the steel industry to support it through hard times.
While EU safeguards curtailed imports of steel, countries changed tack and started to supply steel-containing end products to the EU, such as telecom towers and nails, with most of these coming from China, Polish Steel Union of Distributors’ (PUDS) chief executive Iwona Dybal said at the meeting attended by Kallanish. 2024 data show Polish end-use production dropped due to these imports, “and this is just the beginning”, Dybal warned, pointing to the risk of US tariff-induced trade diversion.
Grzegorz Jagielski from the Polish industry ministry’s mining and metallurgy department said that while government has had its finger on the coal market pulse for a while, it has only recently started closely consulting with steelmakers. The focus on defence has made the industry even more critical. Authorities are preparing a plan that will define a national industrial policy to support steelmaking, he added.
Despite running a first-class business, distributor Stalprofil is “helpless” against the environment it finds itself in, high energy costs and “unfair” steel imports, all factors which lie in the control of government, said the firm’s ceo, Henryk Orczykowski. With a war on, the government must act with military efficiency to save industry, he demanded.
Although US President Donald Trump is not a good example in all cases, “when it comes to the speed of making a decision, and effectiveness, we really have to go with the geopolitical current that is currently happening,” Orczykowski asserted.
The proposed melt and pour rule for EU trade defence instruments (TDIs), while not solving everything, will help increase effectiveness of trade, having implications for TDIs, for Russian sanctions and for the carbon footprint of imports, said Polish Steel Association (HIPH) ceo Moryslaw Motyka.
Carbon capture, utilisation and storage (CCUS) will undoubtedly be part of the EU steel industry’s future, with ArcelorMittal Poland (AMP) planning to install a unit later at its “very heavily invested into” blast furnace, said ceo Wojciech Koszuta.
Asked about whether and how the state should intervene in private business in today’s difficult economic conditions, Cognor ceo Przemyslaw Sztuczkowski said that although he is a liberal at heart, “globalisation has been broken for a simple reason – we’ve been tricked.” Globalisation only works when all players operate under the same conditions, which is not the case with subsidies for the steel industry in countries like China, he added.
This process has led to the election of Trump and will likely also lead to big changes in the EU, he continued. The EU was very careful for years not to give any state aid to industry. “Now we’ve totally lost control – that’s the drama of globalisation,” he asserted.
“Nationalisation is not the solution to all problems,” pointed out state-owned Weglokoks ceo Tomasz Slezak. It will not change energy prices or demand on the market. The current trend is a recognition by governments of the importance of certain sectors for national security, he added, after the moderator had brought up the recent example of British Steel being taken over by UK government. There is a parrel between this and Weglokoks which recently took over Huta Czestochowa in Poland.
The state does not necessarily need to own industrial assets to ensure their survival, said Polish coke producer Koksownia Czestochowa Nowa ceo Marek Serafin. Trump has shown it is possible in the US to have certain control over regulation and resources, to dictate the direction of the economy, without state ownership, he added.
Adam Smith Poland

EUROFER and EUROMETAL convene to support the European Steel Supply Chain
In April 2025, EUROFER and EUROMETAL leaders convened to discuss potential collaboration areas for strengthening messaging and initiatives to support the European steel and steel-using industries.
This initial exploratory meeting was prompted by the Steel Dialogue on 4 March 2025, hosted by the European Commission, during which EUROMETAL raised concerns regarding the impact of imported steel derivatives on European distribution, processing, and manufacturing industries.
Both EUROFER and EUROMETAL acknowledged that a robust manufacturing base is essential for strategic autonomy and involves the entire steel supply chain — including both steel production and processing. The Steel and Metals Action Plan represents a strong starting point, where the European Union recognizes industry challenges and importance, but this requires concrete translation into effective regulatory frameworks. Sharing knowledge and perspectives across the value chain will enhance the design and implementation of such policies and measures.
EUROMETAL represents a significant portion of the intermediate steel processing market in Europe — comprising nearly 50% of deliveries in the EU. These processors face substantial challenges to remain competitive and require stronger, more targeted support. A steel industry confronted with a shrinking customer base, particularly in downstream sectors, poses broader risks for the entire European industrial ecosystem, as the same accounts for the European steel customer base that requires a viable steel industry in Europe.
The two associations underscored that the weakening of this vital supply chain puts at risk 13.6 million direct jobs across steel processing, intermediate suppliers, and manufacturing sectors in the EU. The consequences go far beyond economics — this situation threatens a wider European deindustrialization, with the relocation of R&D capacities, loss of innovation hubs, and increased dependence on external markets.
The meeting marked an excellent beginning for further analysis and discussions and will be followed up in due course.
Axel Eggert, Director General of the European Steel Association (EUROFER), stated: “Both EUROMETAL and EUROFER have a strong interest in a vibrant European steel value chain at the benefit of the EU’s economic resilience and strategic autonomy as well as investment, innovation and quality jobs in Europe. We therefore appeal on EU policymakers to support our joint efforts.”
Alexander Julius, President of EUROMETAL, commented: “The EU steel using and steel making industries are at stake. The focus of European policymakers needs to be expanded to the complete supply and value chain of our industry. Joint efforts of EUROFER and EUROMETAL will form a solid basis approaching this important topic sustainably.”
 Joint Statement –