


EU steel industry calls for policy clarity amid weak demand, CBAM uncertainty
Market participants gathered in Luxembourg at the 75th Anniversary conference of European steel distributor association EUROMETAL July 3 voiced growing frustration with the pace and predictability of European steel policy.
As the region struggles with weak demand, rising regulatory burdens, and ongoing uncertainty around the Carbon Border Adjustment Mechanism, or CBAM, participants warned of over-regulation and inadequate protection for the downstream sector.
The mood at the conference was one of cautious realism, with calls for decisive EU action on trade defense and decarbonization targets amid volatile prices and geopolitical risks.
CBAM rollout raises concerns over cost visibility, compliance
While many agreed CBAM is structurally important to Europe’s climate ambitions, traders and distributors expressed concern over the current lack of clarity around emissions benchmarks, pass-through costs, and the long-term financial burden on supply chains.
“Right now, nobody can make estimates about how much margins they will make once CBAM kicks in,” a Germany-based distributor told Platts, part of S&P Global Commodity Insights, on the sidelines of the event. “It could vary by as much as Eur100/mt, which makes planning extremely difficult.”
Participants noted that downstream buyers, particularly in sectors like automotive and white goods, are asking for fixed prices but are unwilling to absorb potential CBAM-related volatility. Several speakers highlighted the danger of delivery slipovers into the first quarter of 2026 — when full CBAM cost implications are expected to materialize — forcing buyers to pay unexpected premiums.
Platts assessed Northwest European hot-rolled coil (HRC) at Eur555/mt ex-works Ruhr on July 3, and Southern European HRC at Eur540/mt ex-works Italy.
Distribution demands stronger role in policy
A Germany-based service center source warned that overregulation and indecision are damaging confidence in Europe’s ability to execute its climate and trade goals.
“Sometimes we just need a yes or no on the regulatory side,” he said. “CBAM doesn’t help in its current form, and 80%-90% of this industry is built on small and medium enterprises that can’t manage this uncertainty alone.”
Other distributors echoed this sentiment, arguing that while green steel presents real decarbonization potential, customer demand remains weak due to unclear value perception and the absence of downstream incentives.
“Increasing steel prices by 50% would only raise the price of a car by 0.6%, but reduce emissions by over 20%,” a buyer source told Platts on the sidelines. “Yet nobody’s paying a premium unless they see utility in the final product. The state needs to step in with tools like subsidies or green procurement rules.”
Participants noted that downstream buyers, particularly in sectors like automotive and white goods, are asking for fixed prices but are unwilling to absorb potential CBAM-related volatility. Several speakers highlighted the danger of delivery slipovers into Q1 2026 — when full CBAM cost implications are expected to materialize — forcing buyers to pay unexpected premiums.
Market players warned that existing safeguard mechanisms are inadequate to defend against underpriced imports.
“We need to move beyond crude safeguards,” another distributor told Platts. “We should start protecting semi-finished and downstream products that are 100% steel, like clutch plates.”
Many distributors are relying on large trading firms to calculate CBAM and landed costs for imports.
“We’re outsourcing the compliance burden, but it comes at a price. We need Delivered Duty Paid (DDP) prices that include the cost of CBAM,” the sources said.
Fragmented Europe, global competition
Luxembourg Prime Minister Xavier Bettel addressed the event, warning of growing global instability and Europe’s reliance on external partners.
“We rely on America for security and Russia for gas,” he said. “China’s oversupply is a major threat — and the EU must start acting more like a unified bloc.”
Several participants referenced Ilva and the failed sale to Liberty as an example of Europe’s fragmented approach.
“We don’t have strong regional champions,” the prime minister said. “We have too many mid-sized players trying to compete globally.”
European mills emphasized the need for a clear industrial policy to rival US support mechanisms.
“We export 90% of our scrap. The US has used policy to revitalize crude steel — we can do the same,” a mill source said. “CBAM should protect products made with EU steel, not just steel itself.”
Sentiment remains steady, but outlook clouded
Despite weak order intake and summer slowdown trends, most sources said current business levels were not catastrophic.
“Volumes are down 2%-3% from last year, but it’s not all bad,” the buyer source said. “The real issue is confidence and long-term visibility.”
A sense of realism pervaded the event, with broad consensus that if the EU wants to maintain its industrial base, it must back it with clear regulation, financial support, and pragmatic trade defense.



EUROMETAL Presidency Meeting held in Luxembourg on the eve of 75th Anniversary
On Wednesday, 2 July 2025, the EUROMETAL Presidency met in Luxembourg, on the eve of the 75th Anniversary celebrations. The meeting gathered 13 participants in person and 2 online for strategic discussions on current and upcoming priorities.
The agenda included the presentation of the 2024 Annual Balance Sheet, updates on the 2025 Action Plan and final preparations for the 75th Anniversary Conference.
Additional points discussed:
- Planning of the next National Federations Meeting
- EUROMETAL’s input to the public consultation on new EU trade measures
- Progress from the Working Group on Steel Safety
- Activities of the Working Group on Low-Carbon Steel
A second face-to-face Presidency Meeting is planned to take place on the eve of the EUROMETAL Steel Trade Day, scheduled for early December 2025 to prepare for the upcoming General Assembly 2025 and to follow up on key action points.

Tata Steel UK to extend lives of two continuous casters in Port Talbot
Tata Steel UK, a subsidiary of India-based steelmaker Tata Steel Limited, has announced that it has signed a contract with local company Systems Group for the first phase of the refurbishment of its two continuous casters in Port Talbot, South Wales. Systems Group will carry out critical structural work on the casters and replace over 1.5 miles of pipework, extending the casters’ lives.
The life-extension of the continuous casters will support the company’s efforts on sustainable low-carbon steelmaking as it prepares for the commissioning of a new state-of-the-art electric arc furnace by the end of 2027. Once operational, the EAF is expected to reduce Port Talbot’s carbon emissions by approximately 90 percent.
“This work will ensure our existing casters are in the very best condition to handle steel from our new electric arc furnace in the volumes and qualities demanded by our customers,” Ian Ellis, engineering project manager at Tata Steel UK, said.


EUROFER concerned over viability of new 90% emission reduction target
The European Commission has proposed an amendment to the EU Climate Law, aiming for a 90 percent reduction in net greenhouse gas (GHG) emissions by 2040, compared to 1990 levels. While the announcement signals a strong climate commitment, it has also raised serious concerns within the European steel sector, which plays a crucial role in decarbonization efforts.
Commenting on the amendment, the European Steel Association (EUROFER) has stated that the European steel industry is already doing its part, but it faces mounting challenges due to insufficient support mechanisms and unclear economic incentives. The association said that the EU needs to implement the Steel and Metals Action Plan much more decisively, delivering a highly effective trade protection against global overcapacity, access to internationally competitive low carbon energy and scrap, and a watertight Carbon Border Adjustment Mechanism (CBAM).
Pointing out that the EU steel industry has plans for over 60 industrial scale projects that could reduce emissions significantly by 2030 if they receive timely and effective support, EUROFER stated that many projects have already been delayed, and some have been stopped altogether due to the lack of support. “In this light, a 90 percent headline target for the entire EU by 2040 risks becoming an illusion,” said Axel Eggert, director general of EUROFER, stressing the unrealistic pace of decarbonization expected from energy-intensive sectors.

Long steel prices in Europe stable to down on approaching holidays
Long steel prices in Europe were stable or slightly lower, varying by region, in the week to Wednesday July 2.
In Northern Europe, rebar prices were largely unchanged, but demand was said to be slowing due to the approaching summer holiday period.
Fastmarkets’ price assessment for steel reinforcing bar (rebar), domestic, delivered Northern Europe, was €615-640 ($726-755) per tonne delivered on July 2, static week on week.
Some of the highest prices were in Denmark, with some offers as high as €640-645 per tonne delivered. Market sources explained this by the lack of domestic supply and limited access to imports.
Prices in Germany were heard in a lower range of €615-630 per tonne delivered.
The cheapest prices were in the south of France, where sources reported a strong effect from supply out of Italy.
Fastmarkets’ price assessment for steel reinforcing bar (rebar), domestic, exw Italy, narrowed to €510-550 per tonne on July 2, from €500-560 per tonne on July 25.
Prices at the lower end of the range related to the north of the country, where availability of material is higher, while the higher end was for prices in the south of the country
Market sources reported that infrastructure development was driving demand in the south of Italy.
Wire rod
The latest price indications for mesh wire rod in Italy came in a wide range of €580-615 ($694-726) per tonne delivered, depending on supplier, which kept Fastmarkets’ weekly price assessment for steel wire rod (mesh quality) domestic, delivered Southern Europe, unchanged on July 2 at €580-615 per tonne.
In Northern Europe, meanwhile, prices softened over the week, with market sources estimating the workable price within the range of €600-610 per tonne delivered, with some suppliers saying that the upper end was sometimes hard to achieve.
Fastmarkets’ weekly price assessment for steel wire rod (mesh quality) domestic, delivered Northern Europe, was €600-610 per tonne on July 2, down from €610-615 per tonne on June 25.


European heavy steel plate prices pulled down by sluggish trade, weak demand
Heavy steel plate prices in Europe widened downward in the week to Thursday July 3, amid persistently sluggish trading and weak demand.
Italy
Italian commodity-grade plate prices were under pressure over the past seven days, with many market participants estimating prices to be either stable or slightly lower, with mills looking to attract bookings amid a weak demand environment.
“Demand has not improved,” one trader source said.
Fastmarkets’ weekly price assessment for steel domestic plate, 8-40mm, exw Southern Europe, was €590-620 ($693-728) per tonne on Thursday, widening downward by €10 per tonne from €600-620 per tonne a week before.
Stockholders and end-users have only been buying on a hand-to-mouth basis, a second market source said.
And there was still no interest in imported material because there were sufficient stocks at low prices and short delivery times available.
Northern Europe
In Northern Europe’s heavy plate market, prices also widened downward amid slow trading for commodity-grades.
“Customers and end-users are still only purchasing what they absolutely urgently need,” the second source said.
Fastmarkets’ weekly price assessment for steel domestic plate, 8-40mm, exw Northern Europe, was €640-675 per tonne on Thursday, widening downward by €10 per tonne from €650-675 per tonne a week earlier.
Market participants noted that the only consistent demand has been for specialist plate grades, including those used in foundations for offshore wind-power installations or monopiles.

European steel CRC, HRC prices stable on seasonally low demand
Downstream flat steel prices fell in Europe in the week to Wednesday July 2, due to depressed demand and recent market slowdowns, trade sources told Fastmarkets.
Market participants attributed the current lack of demand to low interest among buyers during the summer lull.
Northern Europe
Market sources estimated the workable price for domestic cold-rolled coil in Northern Europe at €650-660 ($764-776) per tonne ex-works, compared with €690 per tonne ex-works in mid-June.
Deals were also heard at €660 per tonne ex-works this week.
Fastmarkets’ weekly price assessment for steel cold-rolled coil, domestic, exw Northern Europe, was €650-660 per tonne on July 2, falling from €660-670 per tonne the week before.
Meanwhile, import prices for CRC remained stable this week.
Fastmarkets’ weekly price assessment for steel cold-rolled coil, import, cfr main port Northern Europe, was €630-640 per tonne on Wednesday, unchanged week on week.
Domestic prices for hot-dipped galvanized coil also fell this week, with industry sources estimating the workable market in Northern Europe at €670-680 per tonne ex-works, compared with €680-690 per tonne in the previous assessment.
Deals were also heard at €670-680 per tonne ex-works this week.
As a result, Fastmarkets’ weekly price assessment for steel hot-dipped galvanized coil, domestic, exw Northern Europe, was €670-680 per tonne on Wednesday, narrowing downward from €670-690 per tonne the previous week.
HDG import prices also remained stable this week.
Fastmarkets’ weekly price assessment for steel hot-dipped galvanized coil, import, cfr main port Northern Europe, was €690-700 per tonne on Wednesday, unchanged week on week.
Southern Europe
Domestic CRC prices in Southern Europe remained stable in the week to Wednesday, according to market sources.
Market sources estimated the workable price for domestic CRC at €660-680 per tonne ex-works on Wednesday, compared with €670-700 per tonne ex-works last week.
Fastmarkets’ weekly price assessment for steel cold-rolled coil, domestic, exw Southern Europe, was €660-680 per tonne on Wednesday, unchanged week on week.
CRC import prices also remained stable this week.
Fastmarkets’ weekly price assessment for steel cold-rolled coil, import, cfr main port Southern Europe, was €590-630 per tonne on Wednesday, unchanged week on week.
At the same time, domestic HDG prices also remained stable, with trade sources estimating the workable price at €680-690 per tonne ex-works, the same as last week.
Consequently, Fastmarkets’ weekly price assessment for steel hot-dipped galvanized coil, domestic, exw Southern Europe, was €680-690 per tonne on Wednesday, unchanged week on week.
HDG import prices were also stable this week.
Fastmarkets’ weekly price assessment for steel hot-dipped galvanized coil, import, cfr main port Southern Europe, was €670-700 per tonne on Wednesday, unchanged since mid-May.

ArcelorMittal Poland fires hydrogen furnaces, builds new galvanizing line
ArcelorMittal Poland, the Polish arm of global steel giant ArcelorMittal, has announced that it has launched new hydrogen furnaces at the annealing line of its cold rolling mill at its Kraków site, taking a significant step toward sustainable steelmaking.
With a total investment of PLN 52 million ($14.45 million) under a broader PLN 100 million ($27.79 million) modernization plan, these furnaces mark a key milestone in reducing the environmental footprint of steel production. The new hydrogen furnaces are expected to yield multiple operational and environmental benefits such as increased steel purity and quality by optimized annealing, 50 percent reduced annealing time, increased productivity, lower energy consumption, and the elimination of ammonia.
Alongside the furnace project, ArcelorMittal Poland is constructing a new galvanizing line at the Kraków site. This development aims to reduce zinc consumption and enhance product durability and corrosion resistance.
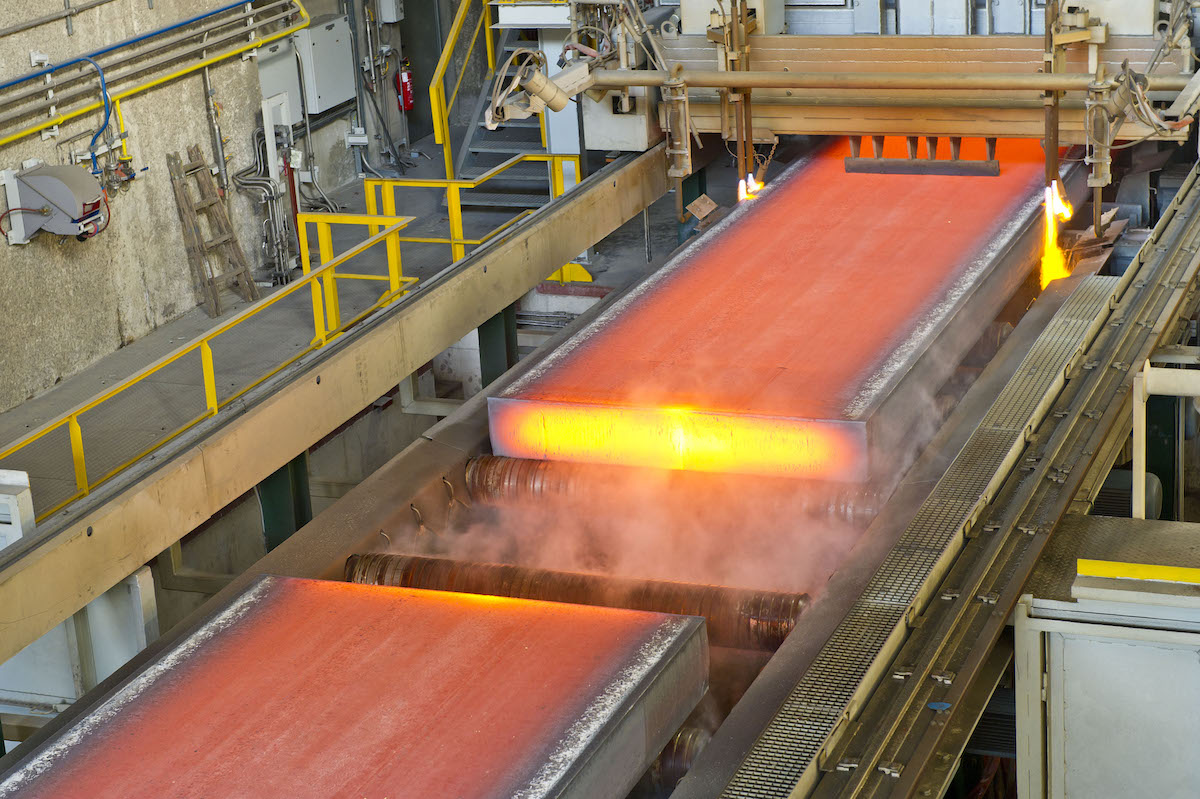
Most local Bulgarian offer prices soften amid lower demand
Over the past month, Bulgarian domestic longs prices have mostly fallen by BGN 10-50/mt (€5-26/mt), being under pressure from lower local demand ahead of the summer season. However, local beam prices have increased by BGN 50/mt (€26/mt) due to the current lack of supply. Most Bulgarian buyers are exerting pressure for additional discounts as the market seems unstable at the moment and specifically in the import segment the positions of suppliers seem rather weak. The general outlook on the demand side in Bulgaria is negative, while overall stocks seem to be at medium levels at the moment.
In the import segment, Turkish rebar and wire rod export offers to Bulgaria for July shipments are respectively available at $550-560/mt CFR, down by $20-25/mt, and $555-565/mt CFR, down by $25-30/mt over the past month, with the freight rate from Turkey to Bulgaria estimated at around $15-20/mt. North African mills are offering at $545-555/mt FOB for both rebar and wire rod depending on the supplier, with freight estimated at a minimum of $20-25/mt.
Local prices for long products in Bulgaria, BGN/mt (€/mt) CPT
| Product | Price, CPT | Monthly change | ||
| BGN/mt | €/mt | BGN/mt | €/mt | |
| Rebar | 1,160-1,180 | 593-603 | -30/-50 | -15/-26 |
| Wire rod | 1,220-1,250 | 624-639 | -30/-10 | -15/-5 |
| Merchant bars | 1,300-1,350 | 665-690 | -50/-50 | -26/-26 |
| Beams | 1,520-1,600 | 777-818 | +50/-10 | +26/-5 |
€1 = BGN 1.956
$1 = €0.85
EU HRC prices inch lower amid import pressure, mixed outlooks
European hot-rolled coil prices inched down July 3 as further pressure from imports and mixed outlooks dampened sentiment within the market.
Many participants reiterated the subdued market conditions at the outset of the European summer holidays as the industry converged at the EUROMETAL 75th Anniversary conference in Luxembourg.
A distributor source said a favorable euro/US dollar exchange rate was making raw materials slightly cheaper for mills, giving them some relief in times where prices have fallen around Eur100/mt since the end of April.
A mill offer was reported in Northern Europe at Eur550/mt ex-works Ruhr, with tradable values in a range of Eur540-560/mt on the day, as sources at the event reiterated the wider conditions, and referred to the potential for lower prices to be attained for high tonnage enquiries.
In Southern Europe, market participants said activity was limited. An offer was reported at Eur545/mt ex-works Italy, with a tradable value being reported at Eur540/mt.
On the import side, prices fell further in both Northern and Southern Europe as offers from Turkey and Indonesia continued to get more competitive.
In Southern Europe, offers for Turkish HRC were reported at Eur500-505/mt CIF Italy duty paid, and for Indonesian material at Eur470/mt CIF Italy.
Indonesian material in Northern Europe was offered at Eur470-480/mt CIF Antwerp.
“Most people are stocking up on imports now,” a trader source said. “Indonesia and Saudi Arabia seem to be alternatives for now – people are always trying to find different sources for material not subject to safeguards,” he added.
Platts assessed imported HRC in Northern Europe at Eur480/mt CIF Antwerp, down Eur10 day over day, and in Southern Europe at Eur475/mt, down Eur15 day over day. Both prices assessed are at their lowest levels since 2021.
Platts assessed domestic HRC in Northern Europe at Eur555/mt ex-works Ruhr, down Eur5 day over day, the lowest level since December 2024. In Southern Europe, HRC was assessed at Eur540/mt, stable day over day and the lowest level since October 2024.
Platts is part of S&P Global Commodity Insights.