

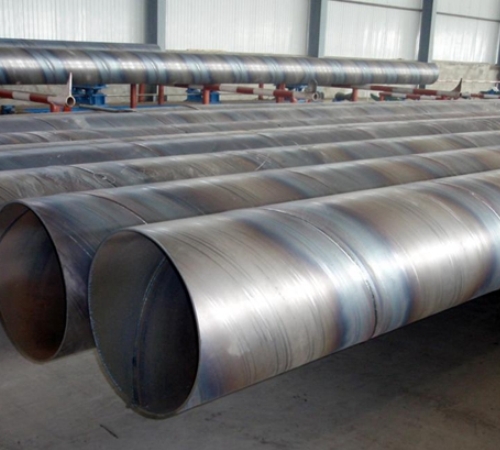
Interpipe supplies pipes for North Sea offshore wind farm project in the United Kingdom


European longs producers implement further hikes
Several European long steel producers are implementing or considering price increases of €20-50/tonne ($23.37-58.43/t) across rebar, sections and wire rod, driven by rising costs linked to the US-Iran conflict.
According to sources, ArcelorMittal is increasing its values by €50/t across its range of longs.
Despite the ceasefire in Iran, energy price volatility remains elevated and the outlook for costs remains highly uncertain. ArcelorMittal is said to be limiting the validity period of its quotes in response to the ongoing uncertainty around input costs.
Turkish HMS 80:20 prices are also rising sharply, causing scrap increases in several Western European countries. Last week, an increase of some €10/t also emerged in Germany. Strong export demand and high volumes of material leaving northern ports have prompted scrap suppliers to push through increases of up to €15/t compared to March settlement levels, with mills forced to pay the hikes given their substantial procurement needs this month.
The Tube and Wire trade show in Düsseldorf this week will be used as a focal point for announcements, with both producers and buyers telling Kallanish they are awaiting the event to assess market sentiment. While buyers confirm there is no panic buying at present, some apparent demand is resurfacing across most long products thanks to supply uncertainties linked the conflict.
One long products producer notes that scrap is not the only pressure. He also reports significantly higher logistics costs.
A southern European producer adds that price increases implemented in March have proved insufficient to cover the rising input costs. A Western European mill is said to be finalising the level of its next price increase, which is believed to be at least €35-40/t.

German Steel Federation: Automotive package welcome while high energy costs continue to burden industry

EU HRC quota filled by India ahead of expected safeguard changes
The quota for European hot-rolled coil under category 1A has been exhausted by India following the start of the new quota period on April 1, according to the latest data published by the European Commission.
India had a total quota of around 225,305 mt that appeared to be over-subscribed in the first few days, a similar trend to the quota from the prior quarter.
The exhaustion comes ahead of the widely expected safeguard measure changes from July 1, which would see the European Commission cut quotas by almost 50%, increase the out-of-quota duty rate to 50% from the current 25%, and look at introducing a melt-and-pour origin rule.
Any additional material from India that is cleared before June 30 will now incur a duty of 25%. Importers will also need to budget for the purchase of CBAM certificates in February 2027 to cover for embedded emissions in material that has been imported in 2026.
After the first quarterly CBAM price was confirmed at Eur75.36/mtCO2e, importers at least have a firmer basis to calculate their 2027 costs using default values, but uncertainty still surrounds the use of actual emissions values, in particular with the speed of the verification process for exporting mills.
The quota for Turkey has also seen high rates of utilization since April 1, with a balance of 169,607 mt from a total allocation of 398,355 mt, not including over 18,000 mt that is awaiting clearance.
Taiwan has a balance of around 71,100 mt from a total allocation of 111,491 mt, but other country-specific quotas are largely untapped in a time of import uncertainty.
Since the start of the Middle East war, fresh import deals have been scarce as freight cost volatility and longer lead times for certain routes dampen interest, which, sources said, has shifted focus into sourcing some material domestically instead.
With a two-week ceasefire announced by the US and Iran, importers will be evaluating the situation to see whether the risk of ordering material from certain regions will be reduced.
Platts, part of S&P Global Energy, last assessed imported HRC in Northern Europe at Eur550/mt CIF Antwerp, and in Southern Europe at Eur540/mt CIF Southern Europe, both up Eur35 month over month.
Author: Riley Waters


New EU Rules reinforce steel safeguards on rebars and merchant bars
The European Commission has published today an Implementing Regulation providing further clarification on the classification of rebars and merchant bars within the EU steel safeguard regime.
This clarification is intended to ensure that these products are consistently classified and imported under the correct tariff rate quota categories, thereby reinforcing the effectiveness of the existing measures.
The Regulation enters into force immediately and will also apply under the new steel import regime from 1 July 2026.

French longs prices rise despite demand easing
French long products transaction prices have risen sharply since early March compared to pre US-Iran conflict levels, Kallanish hears.
After an initial wave of restocking driven by buyer concerns of further price increases following the outbreak of the conflict, demand has since eased across most product categories over the past two weeks.
Rebar demand is showing signs of recovery after the Easter break, however, with buyers returning to the market amid fears of supply disruption linked to the conflict.
Sources confirm that longs procurement during the March restocking phase has created inventory levels that will take time to deplete. The general demand landscape remains challenging. The French economy has been weak in the first half of the year and inflation is rising. The country is now entering an extended period of reduced commercial activity, with the Easter break, mid-term school holidays and several public holidays in May set to dimmish sales in the weeks ahead.
Longs prices have risen by around €40/tonne ($46.16/t) on average against pre-conflict levels. Apart from rebar, for which consumption remains dynamic, general market activity is stalling as distributors struggle to absorb the increases and pass them on downstream.
A large buyer notes there is no panic buying in the market, while a distributor warns that demand has turned very weak following a solid March.
First-category section prices is now at €800/t delivered. Rebar has increased steadily over the past weeks to €660-690/t delivered. Merchant bar prices have also increased significantly, by some €40/t on average reaching €300/t delivered from €260-270/t to a level of €700-720/t including size extras.

Italian rebar prices jump further
Italian rebar producers have pushed prices up by a further €20/tonne ($23.08/t) this week, with some mills suspending sales as offers move to €430/t base ex-works compared €410/t the week before the Easter break, Kallanish learns.
The sharp and successive price increases seen in Italy began shortly after the outbreak of the US-Iran conflict and are driven by surging energy costs linked to the hostilities.
At the beginning of March, buyers were purchasing material at €270-280/t depending on order size. New transactions are now at €410/t base ex-works.
However, the steep increases and repeated sales stops by producers are impacting market activity. Multiple sources confirm transactions are minimal at current price levels, with buyers limiting purchases to very small tonnages, one or two truckloads at a time, to cover immediate needs only.
Distributor stocks are described as high, with weak downstream demand allowing only a slow depletion. Construction companies are said to be delaying new building projects in response to soaring prices, by several months until there is greater market clarity. One large distributor says he will not purchase a single tonne in April at current prices, having covered his needs before the successive rounds of increases began. With the market so sluggish April is seen as a slow month.
Sources are also pointing out the payment defaults and delays that are now more and more frequent both in the north and in the south noting that companies cannot afford to buy at high prices. Including size extras of €260-270/t, effective transaction prices for Italian rebar are currently assessed at €670-680/t ex-works, up from an average of €540/t at the beginning of March.
Mesh prices have also risen sharply, from contract levels of €340/t base ex-works at the start of March to €460-470/t, excluding approximately €300/t in extras.
Author: Natalia Capra France


7 Steel Nordic expands sales into Czech Republic
Czech-owned 7 Steel Nordic Manufacturing is preparing to send its first shipment of steel to a customer in the country, marking an expansion of its European footprint, Kallanish learns.
The material has been produced at the rolling mill in Mo i Rana, Norway and marks the beginning of what is intended to become a new long-term market channel for the company’s low-emission steel. This is produced at Mo i Rana using recycled scrap steel, electric arc furnaces and hydroelectric power.
The first batch consists of approximately 1,200 tonnes of reinforcing bars and coils. Mill owner Sev.en Global Investments says the steel will be used in the completion of the D11 and D35 motorways and in residential projects in Prague, Brno and Ostrava, in the Czech Republic.
The supply process started with a homologation approval programme carried out during the fourth quarter of 2025 to ensure the products meet the technical and regulatory requirements of the Czech market, the group says.
“This is an important milestone for us. The first shipment to Czechia marks the start of developing a new market channel step by step, and we see good opportunities to build a long-term presence there as production in Mo i Rana increases in the coming years,” says Halvard Meisfjord, sales manager at 7 Steel Nordic Manufacturing.
The company aims to position itself as a supplier capable of contributing to the transition towards lower-carbon construction as demand for more sustainable construction materials grows across Europe.
“For us it is important to bring low-emission steel to the Czech Republic and increase awareness of sustainable construction materials in the region. This is a natural step as the European construction sector gradually increases its focus on reducing CO₂ emissions,” Meisfjord adds.
The company says the Nordic and Czech markets complement each other and do not compete directly, making the Czech Republic a suitable channel for gradual growth.
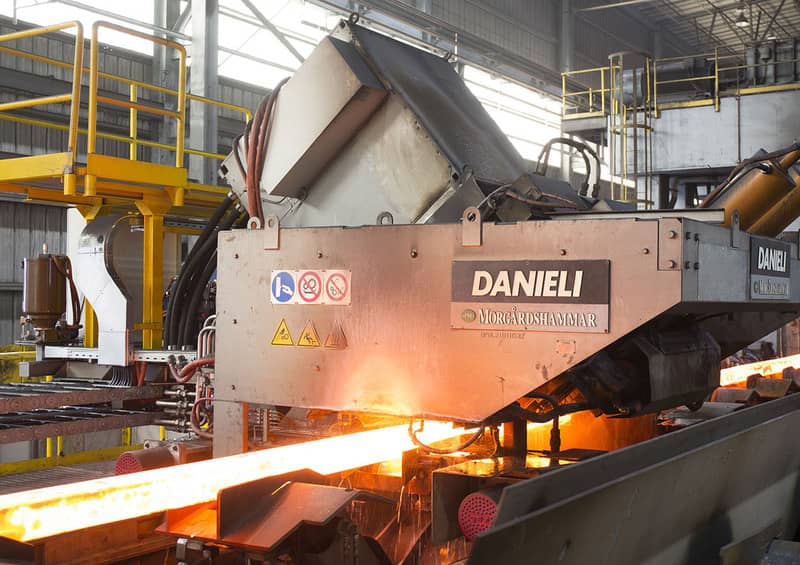
Italy’s Acciaierie Bertoli Safau starts building Hybrid Digital Green Plant
Acciaierie Bertoli Safau (ABS), the steelmaking division of Italy’s Danieli Group, has officially begun construction of its Hybrid Digital Green Plant. This €400 million operation – €355 million of which is dedicated to machinery and digital systems – promises to position the Pozzuolo del Friuli facility among the global leaders in special steel production.
According to a statement from ABS, “For the first time in the world, a single plant will integrate as many as 12 steelmaking process innovations designed by Danieli, ranging from scrap management to continuous casting solidification, including melting, secondary metallurgy, flue gas cleaning, water recovery, and full automation.”
With an estimated annual capacity of 730,000 mt, the new line aims to redefine the concept of industrial efficiency. The plant inherits and enhances the path established ten years ago with the Saturno-QWR line, confirming ABS’s strategy centered on high-quality specialty steels.
The Hybrid Digital Green Plant serves as the cornerstone of a broader industrial plan. Between 2023 and 2028, ABS will invest a total of €817 million. The goal is to achieve a transformation that reduces emissions by 30 percent by 2030 and completes the modernization of the two active furnaces at the site in Cargnacco province.
Thanks to these measures, the group’s production capacity will increase from the current 1.4 million mt to over 2.1 million mt per year.
This announcement follows the guidelines set in May 2024, when Danieli Group communicated a €600 million investment over two to three years dedicated to the development of ABS, with the aim of driving its turnover to €3 billion.
Author: SteelOrbis Editorial Team

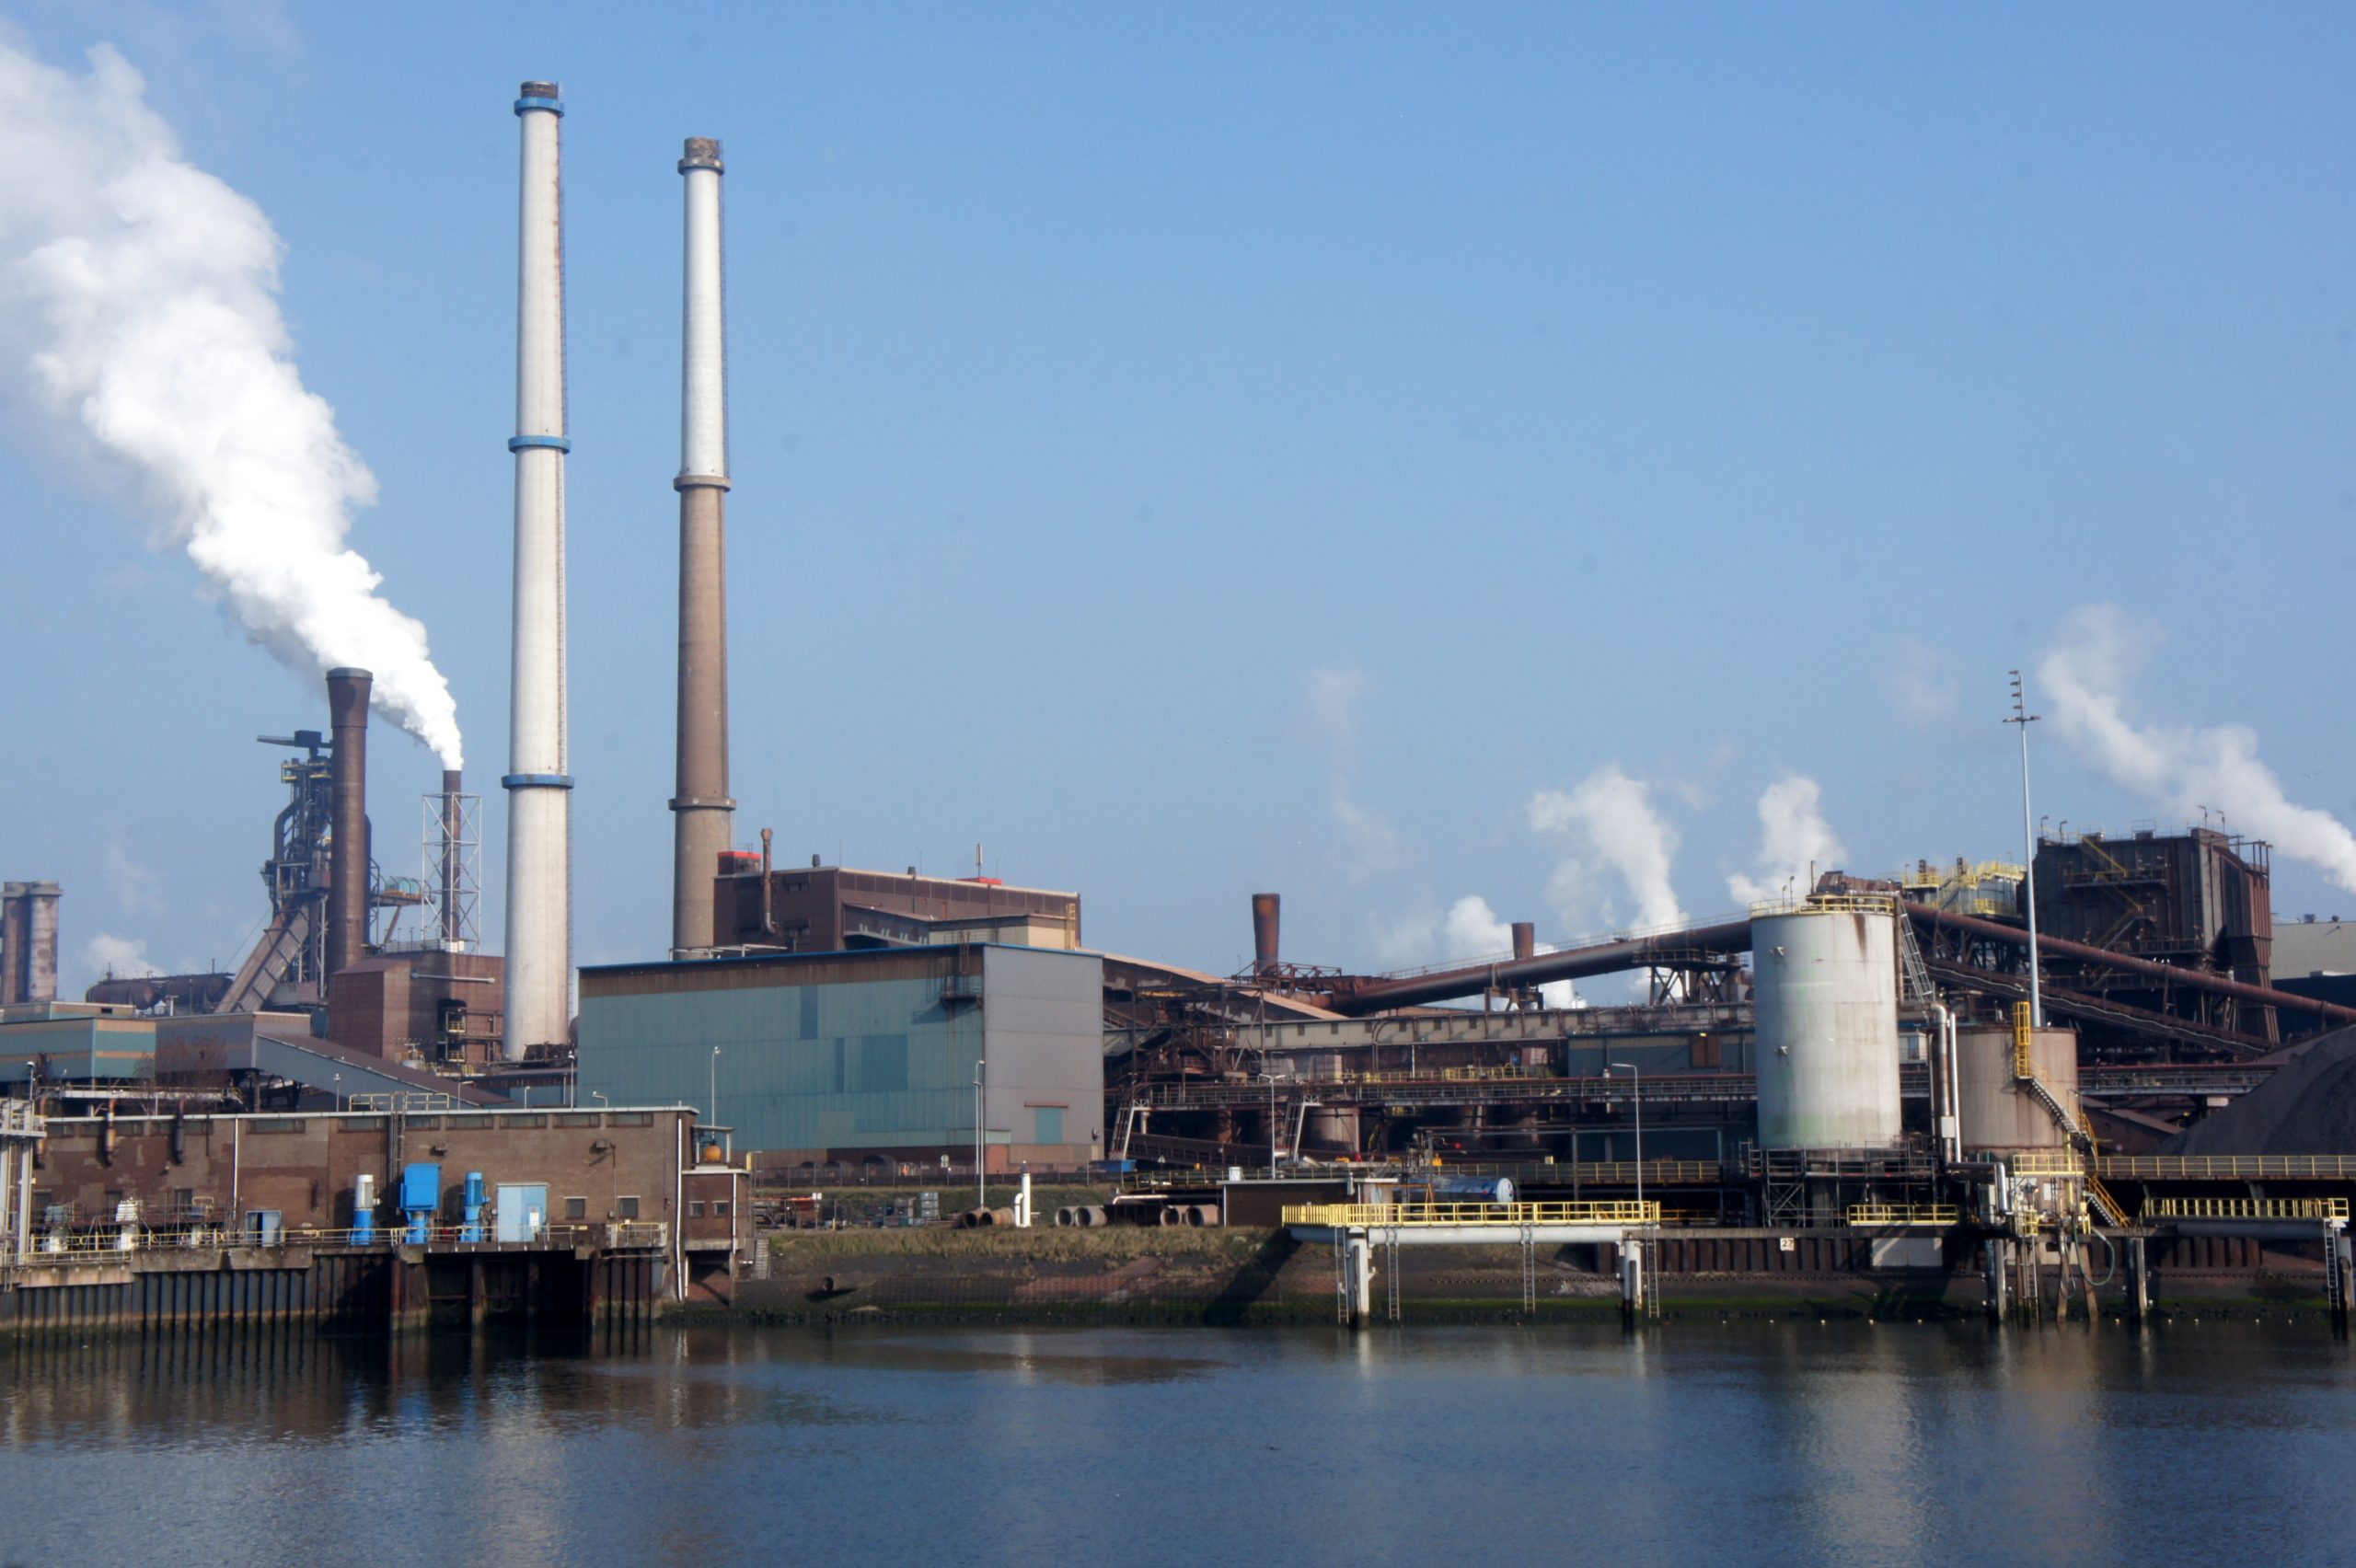
Dutch parliament considers €2 billion support for Tata Steel Nederland decarbonization
The Dutch parliament has announced that it debated a proposed subsidy of up to €2 billion for Tata Steel Nederland, aimed at supporting the company’s transition to lower emissions. The proposal follows provisional agreements between the Dutch cabinet and the company, setting out conditions for financial support.
Funding linked to emissions and performance targets
Under the plan, subsidies would be disbursed in installments and tied to specific milestones, with the government retaining the right to withdraw funding if conditions are not met.
Tata Steel Nederland is required under the agreement to achieve climate neutrality by 2045, while additional incentives, including €200 million, are linked to reducing natural gas usage.
The proposal has faced criticism from several lawmakers, who questioned the company’s ability to meet its commitments. Some called for stricter enforcement measures rather than negotiated agreements, while others emphasized the need for binding conditions, including clear emissions targets, employee involvement and guarantees to maintain domestic production.
Strategic importance of domestic steel production
Supporters of the subsidy highlighted the strategic importance of maintaining steel production in the Netherlands. They pointed to its role in employment, industrial capacity and European strategic autonomy, as well as the need to ensure resilient and diversified supply chains.
Health concerns were a central topic in the debate, with lawmakers calling for measurable targets to reduce harmful emissions and for transparent, independent monitoring. Environmental issues such as steel slag management were also discussed, with a temporary ban currently in place until mid-July pending further decisions.
Competitiveness and regulatory challenges
Lawmakers raised concerns that stricter climate regulations in the Netherlands could create an uneven playing field compared to countries with less stringent policies. In response, the government stressed the importance of stimulating demand for green steel to support both decarbonization and industrial competitiveness.
The total investment required for the transition is estimated at between €2.3 billion and €4 billion, with Tata Steel expected to contribute a significant portion alongside public funding.
The Dutch parliament is scheduled to vote on motions related to the proposal on April 14.