

Solines joins EUROMETAL as Stockholding Member
EUROMETAL is pleased to welcome Solines B.V. and Solines GmbH as new Stockholding Members. Solines is an international stockholder and distributor specialising in steel tubes and pipes.
Read more: solines.nl and solines.de
Swiss Steel targets 1 million mt of annual low-carbon steel supply from Canada starting in 2030
Swiss Steel Group has announced that it has signed an agreement with Canada Nickel Company outlining a potential long-term strategic partnership for the supply of low-carbon semi-finished steel products from Canada.
The agreement aims to combine Canada’s mineral resources and low-carbon energy advantages with Swiss Steel Group’s specialty steel production capabilities and established European customer network. Under the proposed partnership, Swiss Steel Group would secure exclusive access to approximately 1 million mt of low-carbon semi-finished steel products annually starting in 2030. The products, including billets and blooms, would be further processed at the company’s specialty steel production facilities.
Frank Koch, CEO of Swiss Steel Group, stated that the planned cooperation would support the company’s strategy of optimizing its industrial footprint while securing flexible access to competitive, low-carbon semi-finished steel products. He added that the companies would continue working toward establishing a commercially and technically viable long-term partnership.
NetZero Metals to supply low-carbon semi-finished steel
Canada Nickel intends to supply the products through its wholly owned subsidiary NetZero Metals, which plans to process concentrates from the company’s Crawford Nickel project into finished nickel products.
NetZero Metals also plans to convert nickel-chromium magnetite concentrate into low-carbon, potentially net-zero-carbon, semi-finished stainless and specialty steel products.
Author: SteelOrbis Editorial Team

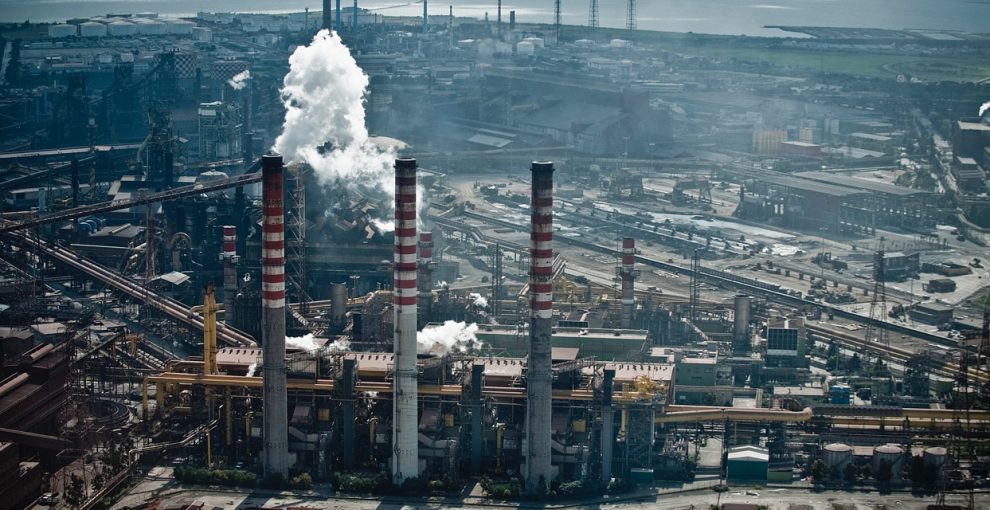
Former Ilva faces restructuring and new legal challenges amid uncertainty over steel production
A new phase of uncertainty is unfolding at the former Ilva steelworks in Taranto, amid corporate restructuring and further legal developments. Acciaierie d’Italia (ADI), currently under extraordinary administration, has initiated a collective redundancy procedure affecting 40 executives, while a new investigation by the Taranto Public Prosecutor’s Office is targeting several former company executives. On the production front, the hot-end facilities remain in preheating mode pending a ruling by Italy’s Court of Cassation.
Corporate restructuring and upcoming deadlines
In a statement issued on October 23, ADI announced the launch of a collective redundancy procedure involving 40 of its 51 permanent executives, as part of a restructuring process linked to the reduction of production activities. The procedure does not entail immediate dismissals but initiates a consultation process with trade union representatives.
Meanwhile, following the October 25 deadline for the shutdown of the hot-end facilities, a government legislative measure allows the plants to remain in preheating mode until December 15, pending the Court of Cassation’s decision. As previously reported by SteelOrbis, the court ruling ordering the shutdown of the facilities has raised serious concerns over production continuity at the site. The extension of the preheating period will help preserve the plants’ operational readiness, although it does not guarantee the resumption of production.
A new meeting between the government and trade unions is also scheduled for today, October 27, at Palazzo Chigi, the Italian prime minister’s office, to discuss the group’s industrial and employment prospects. Regarding the sale process, the deadline for potential investors to submit binding offers remains set for November 8.
New legal proceedings involving former management
Separately, the Taranto Public Prosecutor’s Office has requested that Lucia Morselli, former CEO of Acciaierie d’Italia, and two other individuals be placed under house arrest as part of an investigation into the management of the steelworks between 2019 and 2024. The allegations concern suspected environmental offences and irregularities in the management of emissions and CO₂ emission allowances. The requests for precautionary measures are to be assessed by the judge for preliminary investigations, with preliminary questioning scheduled for November 3.
The former Ilva’s crisis therefore continues to be marked by uncertainty over production, employment and legal matters, as key deadlines approach that could determine the group’s future industrial structure.
Author: SteelOrbis Editorial Team

EU lowers antidumping duties on CR flat steel from Turkey
The European Commission has reportedly revised down its proposed definitive antidumping duties on imports of certain cold rolled (CR) flat steel products from Turkey following objections submitted by Turkish exporters, according to a document circulated by the European Commission.
The reported revisions lower the proposed duty for Borçelik from 9.7 percent to 7.8 percent and for Tatmetal from 5.6 percent to three percent. The rate for other cooperating Turkish producers has reportedly been reduced from 7.3 percent to 4.9 percent, while the residual rate for all other Turkish producers has been lowered from 9.7 percent to 7.8 percent.
| Turkish exporter | Initially disclosed rate in August | Reported revised rate on October 16 |
| Borçelik Çelik Sanayi Ticaret A.Ş. | 9.7 percent | 7.8 percent |
| Tatmetal Çelik Sanayi ve Ticaret A.Ş. | 5.6 percent | 3.0 percent |
| Other cooperating Turkish producers | 7.3 percent | 4.9 percent |
| All other Turkish producers | 9.7 percent | 7.8 percent |
According to the reports, Tatmetal and Borçelik challenged assumptions used in inflation adjustments, CIF and ex-works price calculations, and freight costs. The Commission reportedly accepted some of these objections and adjusted its calculations, resulting in lower proposed duty rates.
The revised disclosure does not constitute the imposition of definitive duties. The deadline indicated for the publication of definitive measures is November 16, 2026. Any definitive duties would take effect in accordance with the final regulation published in the Official Journal of the European Union. The reported revised rates therefore remain proposed measures at this stage.
The Commission initiated the antidumping investigation on September 18, 2025, following a complaint lodged by the European Steel Association (EUROFER) on August 4, 2025. The proceeding covers imports of certain cold rolled flat steel products originating in India, Japan, Taiwan, Turkey and Vietnam. Imports from the five countries were subsequently made subject to registration under a regulation dated December 3, 2025. Registration does not itself impose antidumping duties, but allows for possible retroactive collection if the relevant legal conditions are met.
Author: SteelOrbis Editorial Team
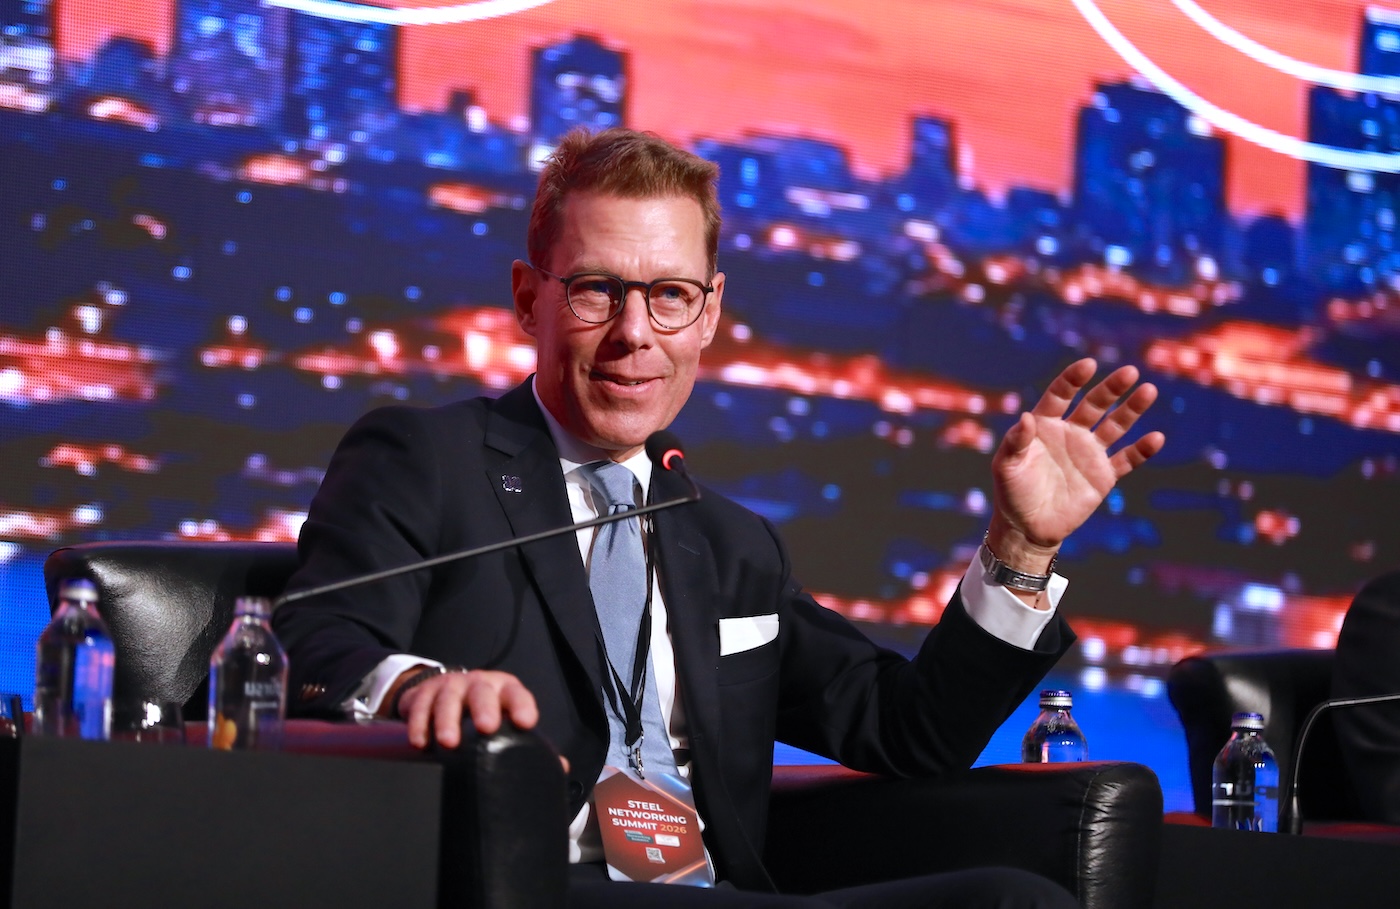
Steel Networking Summit 2026 discusses trade barriers, overcapacity and competitiveness challenges
At the second and third sessions at Steel Networking Summit 2026 conference, organized by the Turkish Steel Exporters’ Association (ÇİB) on October 26, industry representatives examined how trade barriers, geopolitical uncertainty and high energy and financing costs are reshaping steel markets, focusing on demand prospects, transatlantic trade and competitiveness across the steel value chain.
Speaking at the second session titled “The Future of Steel in a Fragmented World: Trade Wars, Economic Developments and New Challenges”, Dr. Yusuf Emre Akgündüz, deputy governor of the Central Bank of the Republic of Turkey (CBRT), noted that higher energy costs were putting pressure on inflation and Turkish steel producers’ costs, while inflation could fall relatively rapidly in the first half of 2027. CBRT would remain focused on disinflation and macro financial stability despite higher energy costs and uncertainty surrounding the Middle East conflict. Turning to geopolitical risks and energy security, Mehmet Öğütçü, chairman of Global Resources Partners, said geopolitical risks and energy security were shaping steel trade and investment. He stressed the need for economically viable decarbonization and strategic partnerships, highlighting defense, energy infrastructure and reconstruction as potential sources of steel demand. Focusing on the outlook for European steel demand, Alessandro Sciamarelli, director of market analysis and economic studies at EUROFER, has shared forecast for EU apparent steel consumption growth of just 0.1 percent in 2026 and 2.3 percent in 2027. He said 2025’s 4.5 percent increase largely reflected purchases brought forward ahead of CBAM and the new EU steel trade measure. High energy costs, overcapacity and weak demand remained key pressures, with capacity utilization below 70 percent.
During the panel moderated by Dr. Barış Esen, director of Yatırım Finansman, the participants, namely Dr. Yusuf Emre Akgündüz, Mehmet Öğütçü, Alessandro Sciamarelli, Fabrizio Di Gianni, senior partner at Van Bael & Bellis, and Matthew Nolan, counsel at ArentFox Schiff LLP, discussed how geopolitical fragmentation, trade barriers and high costs are reshaping steel trade and investment, emphasizing flexible supply chains and financial stability. They also examined the balance between industrial protection and open markets, stressing that global overcapacity requires international cooperation beyond unilateral trade measures, as they will provide only short-term relief.
Trade restrictions and CBAM reshape transatlantic steel markets
Meanwhile, speaking at the third session titled “Transatlantic Steel Outlook: Navigating Trade, Policy and Growth”, Alexander M. Julius, president of EUROMETAL, said EU steel import restrictions and CBAM were raising European manufacturers’ costs, while imported steel-containing goods faced fewer barriers. He called for a level playing field, warning that higher steel and carbon costs were weakening European manufacturers’ competitiveness in both domestic and export markets. Assessing global steel supply and demand, Philipp Englin, CEO of World Steel Dynamics (WSD), said weak demand and rising Chinese exports were pressuring steel prices and profitability, with inflation and energy costs adding risks for 2027. He highlighted US import opportunities despite 50 percent tariffs. Examining the challenges facing steel importers, Julian Verden, general manager for Europe at Stemcor Group, warned that tighter quotas, tariffs and CBAM uncertainty were increasing EU and UK trading risks. He said higher European prices would be needed to absorb additional duties on Turkish HRC, while weak investment confidence and the potential relocation of downstream manufacturing clouded the demand outlook. From the perspective of European steel producers, Mathieu Spoidenne, head of international trade at ArcelorMittal, identified global steel overcapacity as the main challenge facing European producers. He backed EU quotas, CBAM and trade defense measures, calling for downstream protection, closure of CBAM loopholes and a solution to carbon costs affecting EU exports.
During the panel moderated by Stanislav Zinchenko, CEO, GMK Center, Henrik Adam, former president of EUROFER, Mr. Julius, Mr. Englin, Mr. Verden and Mr. Spoidenne examined the diverging outlooks for the US and European steel markets, focused on Europe’s weakening export competitiveness and the effects of tariffs and carbon policies on trade, investment and supply chains, highlighting tensions regarding decarbonization investment. They emphasized supply chain cooperation to share costs and manage risks, while noting financing constraints for smaller companies.
Author: SteelOrbis Editorial Team
Overcapacity creating protectionism, trade barriers say Turkish producers
Turkish steel industry leaders have warned that global overcapacity and a wave of protectionist measures risk fragmenting the steel market, and have called for fairer treatment.
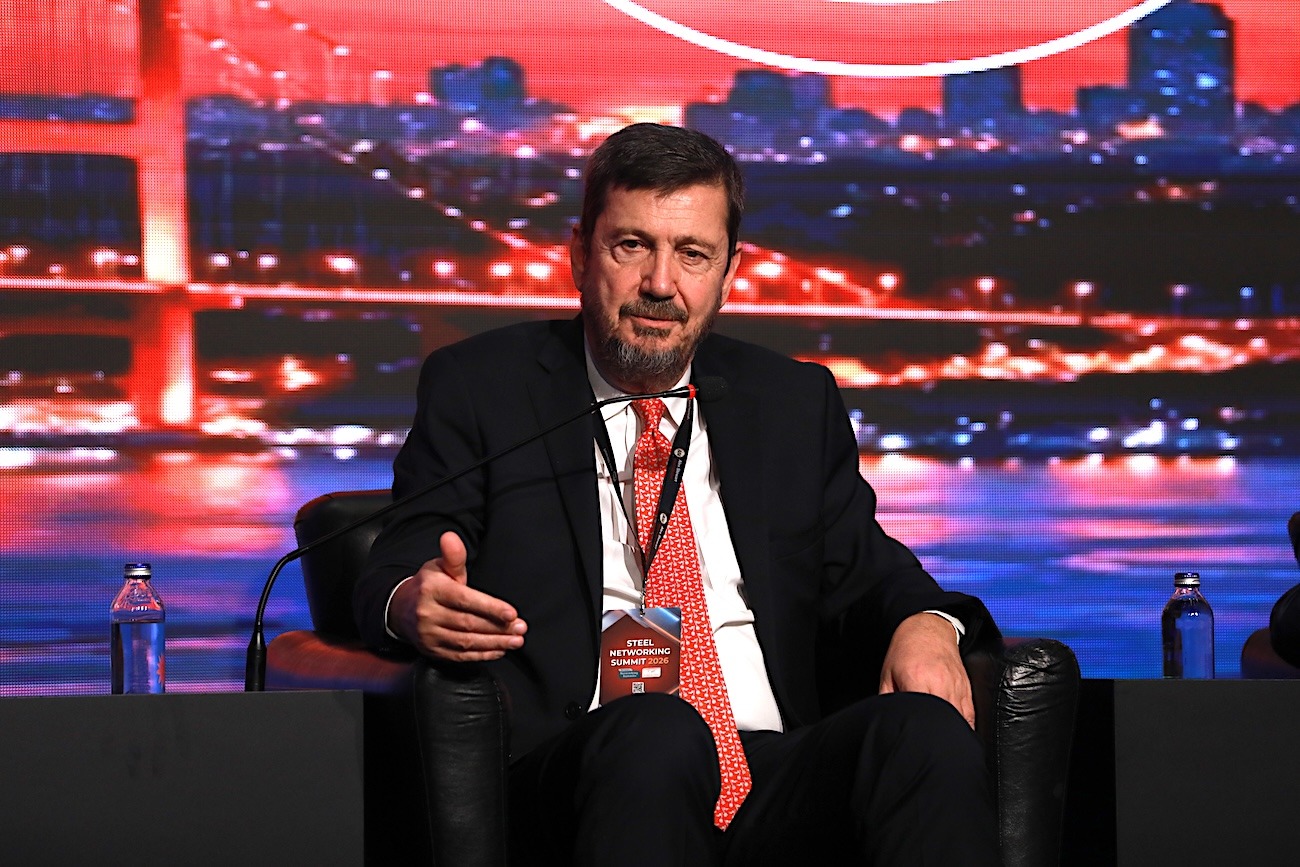
Fuat Tosyalı, chairman of Tosyali group and of the Turkish Steel Producers’ Association, and Uğur Dalbeler, chairman of the Turkish Steel Exporters’ Association (CIB), made keynote speeches at the Steel Networking Summit in Istanbul. The first edition of the event was organised by CIB and attended by Kallanish.
Both speakers identified global overcapacity as the sector’s core structural problem. Capacity created without matching demand does not stay within national borders and inevitably pressures world markets, Dalbeler said. This creates a cycle in which more capacity brings additional export pressure and more protectionism.
Tosyalı said overcapacity and the state-backed production model was making competition destructive in many markets. “The rules of the global steel industry are being rewritten. Decisions on where production will take place, with which technologies, which energy sources, and under what trade conditions are being redefined. Steel is not just an industrial product. It is a country’s production power, its infrastructure, its energy consumption and therefore its energy security, its defence industry, and the foundation of its economic independence.”
“Protecting your industry against unfair competition is one thing; turning the world into closed production zones cut off from each other is another,” he continued, adding that protectionism alone could not be a lasting industrial strategy.
Tosyalı added that it was not right for Turkey to be assessed “from the same perspective as other third countries” in Europe’s steel policies, given decades of integrated value chains with European automotive, machinery, energy and infrastructure sectors.
Meanwhile, Dalbeler called for fairer, more transparent and more predictable trade rules.
The EU’s Carbon Border Adjustment Mechanism (CBAM) and its quota measures on steel imports directly impacts the competitiveness of Turkish producers, Tosyalı noted. If producers lack access to the energy, technology and finance needed for the transition, carbon rules could “stop being a tool of the green transition and turn into new trade barriers”, he said.
Dalbeler echoed this and said decarbonisation policies must reflect differences in producers’ access to energy, finance and technology.
Tosyalı also called for countries that have affordable energy and strong infrastructure to play a larger role. He cited Turkey, Algeria and other regional production centres as offering opportunities in this regard, saying this could lower costs, make supply chains more resilient and cut total emissions faster.
“I believe we should now take our industrial relations with Europe to a more advanced level. By leveraging advantages in energy, raw materials, technology and industrial infrastructure across different geographies, we can develop new, complementary partnerships”, Tosyali added.
He set out three priorities for the sector: protecting domestic capacity against unfair competition, fair and predictable policies from trade partners led by the EU, and mechanisms to finance the move to low-carbon production.
Turkish steelmakers have been seriously affected by high energy costs, financing conditions and trade barriers, but would continue to produce, develop export markets and strengthen international partnerships. The steel sector’s problems are global, but the responses we give to them are becoming increasingly national. The future of the world’s steel sector will be decided not only by our production capacity but by our capacity to work together, he concluded.
Author: Burak Odabasi Türkiye


Lower imports support European HRC producers’ order books despite muted demand
Market participants said European hot-rolled coil producers’ order books are well-filled for 2026 despite muted demand in recent weeks. Reduced imports following the introduction of a stricter safeguard system in July this year were one of the key factors supporting local producers.
In these conditions, mills in Northern Europe are gradually testing the market with higher prices. The market leader was heard voicing offers at €800 ($896.27) per tonne delivered, equivalent to €780-785 per tonne ex-works. Another seller from Northern Europe said he expects the price to reach €800 per tonne ex-works by the end of the year.
These levels, however, have not yet materialized in transactions, with the highest price heard achieved at €760 per tonne ex-works during the day.
A buyer source reported a recent transaction in the region at €750 per tonne ex-works, while another buy-side source provided an indication at €740-750 per tonne ex-works.
Fastmarkets’ daily steel hot-rolled coil index, domestic, exw Northern Europe, was calculated at €753.75 ($844.456) per tonne on Monday, October 26, up by €4.75 per tonne day on day from €749 per tonne on Friday, October 23.
The index was up by €5 per tonne week on week and by €12.08 per tonne month on month.
In the Italian market, suppliers were also trying to achieve higher prices.
“Everyone is trying to increase to €760-770 per tonne delivered (€740-755 per tonne ex-works),” a buyer from Italy said, adding that the lowest sales prices available now are €740 per tonne ex-works.
Another market source estimated tradeable levels in Italy within a wider range of €730-750 per tonne ex-works.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €741 per tonne on October 26, up by €1.94 per tonne day on day from €739.06 per tonne on October 23.
The index was down by €0.88 per tonne week on week but up by €3.5 per tonne month on month.
Several market sources reported that Northern European suppliers were increasing activity in the southern region due to reduced availability of material, caused by production issues that local suppliers encountered over the past few months, as well as lower imports.
One source said transactions took place at €780-790 per tonne delivered, but this information could not be confirmed by the time of publication.


Polish domestic rebar prices narrow amid weak demand, exports to Ukraine
Polish domestic rebar prices narrowed in the week to Friday October 23, amid high production costs, weak demand and exports to Ukraine, sources told Fastmarkets.
“There is some deficit of the material in the market, but demand is traditionally low,” a seller source told Fastmarkets.
One market participant reported an offer for rebar from local producers at €636 ($714) per tonne CPT, equivalent to 2,780 zloty per tonne.
Another source reported an offer at 2,800 zloty per tonne, while a seller source reported offers at 2,840 zloty per tonne.
As a result, Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, CPT Poland narrowed to 2,780-2,840 zloty per tonne, from 2,773-2,850 zloty per tonne the previous week.
“Demand remains weak, and customers say that ‘the season is over.’ Our mills are attempting to raise prices, but without success,” another distributor source told Fastmarkets.
“A lot of material is being exported to Ukraine,” another market participant told Fastmarkets.
The increased exports to Ukraine followed Russian attacks on Ukrainian steel mills in August and September this year, which caused critical damage to infrastructure.
Workable levels for drawing quality wire rod were heard from market participants at 2,900-3,150 zloty per tonne. Another source reported an offer at 3,000 zloty per tonne.
Fastmarkets’ weekly price assessment for steel wire rod (drawing quality), domestic, delivered Poland, widened downward to 2,900-3,150 zloty per tonne from 2,950-3,150 zloty per tonne the previous week.

Liberty Steel Newport enters liquidation
Liberty Steel Newport has entered voluntary liquidation following a petition to wind up by a creditor, Kallanish learns from public record, The Gazette.
A petition to wind up was initially launched in July by Siemens Financial Services. This was followed by a meeting of creditors.
A further petition to wind up was launched by the same company on 12 October, when the meeting of creditors took place. The resolution saw Iain Hunter, director of the company, confirm that it was to be wound up voluntarily.
A notice to creditors was issued on the same day, naming TG Begbies Traynor and Kroll Advisory as joint liquidators of the company.
According to Companies House, its accounts have been overdue since 31 March 2021, with the last accounts made up to 31 March 2019.
Production at the site is believed to have been idled for several years.
A Liberty Steel spokesperson declined to comment when approached by Kallanish.
This insolvency follows GFG-owned UK business Speciality Steel (SSUK) business being placed into compulsory liquidation by the high court in London in August 2025.

European coil hike attempt defies continued lull
Despite demand from European steel users remaining modest, one attempt for a bold increase was made in the run-up to the Euroblech fair in Hanover last week.
The market leader lifted its offer for hot-rolled coil by some €60/tonne ($67/t), on its customer portal and in some direct correspondence, Kallanish hears from German and Scandinavian buyers of HRC.
“That’s an attempt as a prelude to the trade fair; this is not unusual,” a Scandinavian buyer says. He concedes that paid market prices currently can be above €750/t ex-works, but doubts that many people will currently pay anything above €800/t.
The move was not communicated widely, and not echoed by other mills. One other mill source at the time of the fair still indicated the market price at €740-750/t and did not mention any noteworthy hike attempt from his firm.
A German service centre manager believes that the attempt has gone up in smoke. “It does not make sense other than confusing the market,” he says.
Still, many sources do believe that mills in the longer run can bank on rising prices and demand, although at a slower pace. Lead times are seen at three months now although one mill manager tells of some residual rolling capacities in December.
It should be noted that spot prices are now at least €120/t above those one year ago. This is largely attributed to the EU’s measures on imports, but also considers hefty hikes of costs. According to the mill manager, costs for HRC production have risen by €100/t within one year, and for hot-dip galvanized by as much as €130/t, with the zinc price roughly tripling in that period.
Still, these factors stand against the ongoing lack of demand, and the difficulty of handing down price hikes to steel consumers. “With the end of the year in sight, many European steel buyers remain cautious about their purchases… and prefer to keep their inventories low,” a Dutch service centre manager states.