


Trasteel targets acquisition opportunities ahead of Nasdaq listing
Steel trading and processing group Trasteel is growing through selective acquisitions as part of the group’s opportunistic strategy and low-risk trading model, chief executive Gianfranco Imperato has said.
During a podcast by investment analysis firm SPACInsider, monitored by Kallanish, Imperato describes Trasteel as sitting in the middle of the steel supply chain, acting as a customer to producers and supplier to end-users.
Despite being considered a mature market, steel in reality is imperfect, with price differences existing not only over time but also geographically, while industrial assets can at times become available at undervalued prices.
“Therefore, there is a significant possibility to make capital gains out of buying and selling companies, not only buying and selling products,” he says.
On acquisitions, Imperato says the group targets specific opportunities as they arise rather than following a fixed strategy. He points to three recurring scenarios: European companies in a succession phase where founders have no heirs involved in the business, companies struggling to finance their working capital, and companies where partners are in dispute.
He notes that the steel sector’s high working capital intensity makes it unattractive to private equity and financial institutions, creating an opening for operators with the right management skills. When evaluating targets, the group prioritises cost efficiency and management quality.
“Obviously revenues are necessary, but you are a winner if your costs are under control. And this is the key two points of the cost efficiency and the management skills that we are searching before entering into a deal,” Imperato adds.
He is also keen to remain independent from steel production. “Steel production is very cyclical. It takes much more capital, it takes a totally different approach. In reality, we manage a spread between a semi product and the product and we manage a service to many customers that are populating our market.”
Additionally, he argues that the return of trade barriers and supply chain disruptions has restored the value of skilled intermediaries after years of disintermediation during the globalisation era. He highlights when a small entrepreneur from Milan could fly to Vietnam and source coils directly.
“Complications in the world are generating the need [for] operators like us, believed to be able to run around the obstacles that are put in by the politics or geopolitics or by the international trade complications,” he says.
Imperato is clear that Trasteel does not speculate on prices and points to the Iran crisis as an example. Some orders coming from Oman had to be sourced from a different mill when the original supply was disrupted at short notice without taking direct price exposure. “We believe it’s better to have a small but constant margin rather than running risks on speculations which are by definition not always right,” he says.
During the podcast Jamie Carson, vice chairman of Sizzle Acquisition Corp 2, says Trasteel’s hedged business model, global customer base and low inventory risk approach were the key attractions of the deal.
Trasteel is going public through a merger with Sizzle Acquisition Corp. II, a Cayman Islands-based special purpose acquisition company listed on Nasdaq under the ticker Szzl. It will list on Nasdaq through a $1.3 billion ($1.5 billion) business combination.

NW European sections price stabilisation accepted by market
Players on the northwestern European sections market find the latest price hike announcement from the market leader to be fair and believe that it will take root in the market.
The announcement, intended to cover a variety of long products, will mean less of a resurge but rather a stabilisation after shaky pricing over the summer.
Prices in some cases have softened to €800/tonne ($930/t) for Category 1, S235 sections delivered. The €20/t target should bring the level back to €820/t where it was previous, which observers say is “absolutely realistic”.
In July, the market leader had tried for a bigger hike of €40-45/t, but in vain. “So now they are trying more moderately and will be satisfied if it works. That’s often their approach,” one observer tells Kallanish.
Some players are now preparing for prices to head towards €840/t, others say the mills will be happy if they can secure €820/t across the board. One mill manager points at the continuously high power costs in EAF production, which he says, “will not get better going forward”. And he is sure that scrap prices will resurge following the drop in the last two months.
The price will differ slightly by region, he says. And he warns that southern European mills could intervene with lower offers. “They are a factor that’s prone to disturb the prices every now and then,” he says.
European convoy brings industry’s call for competitiveness to Brussels
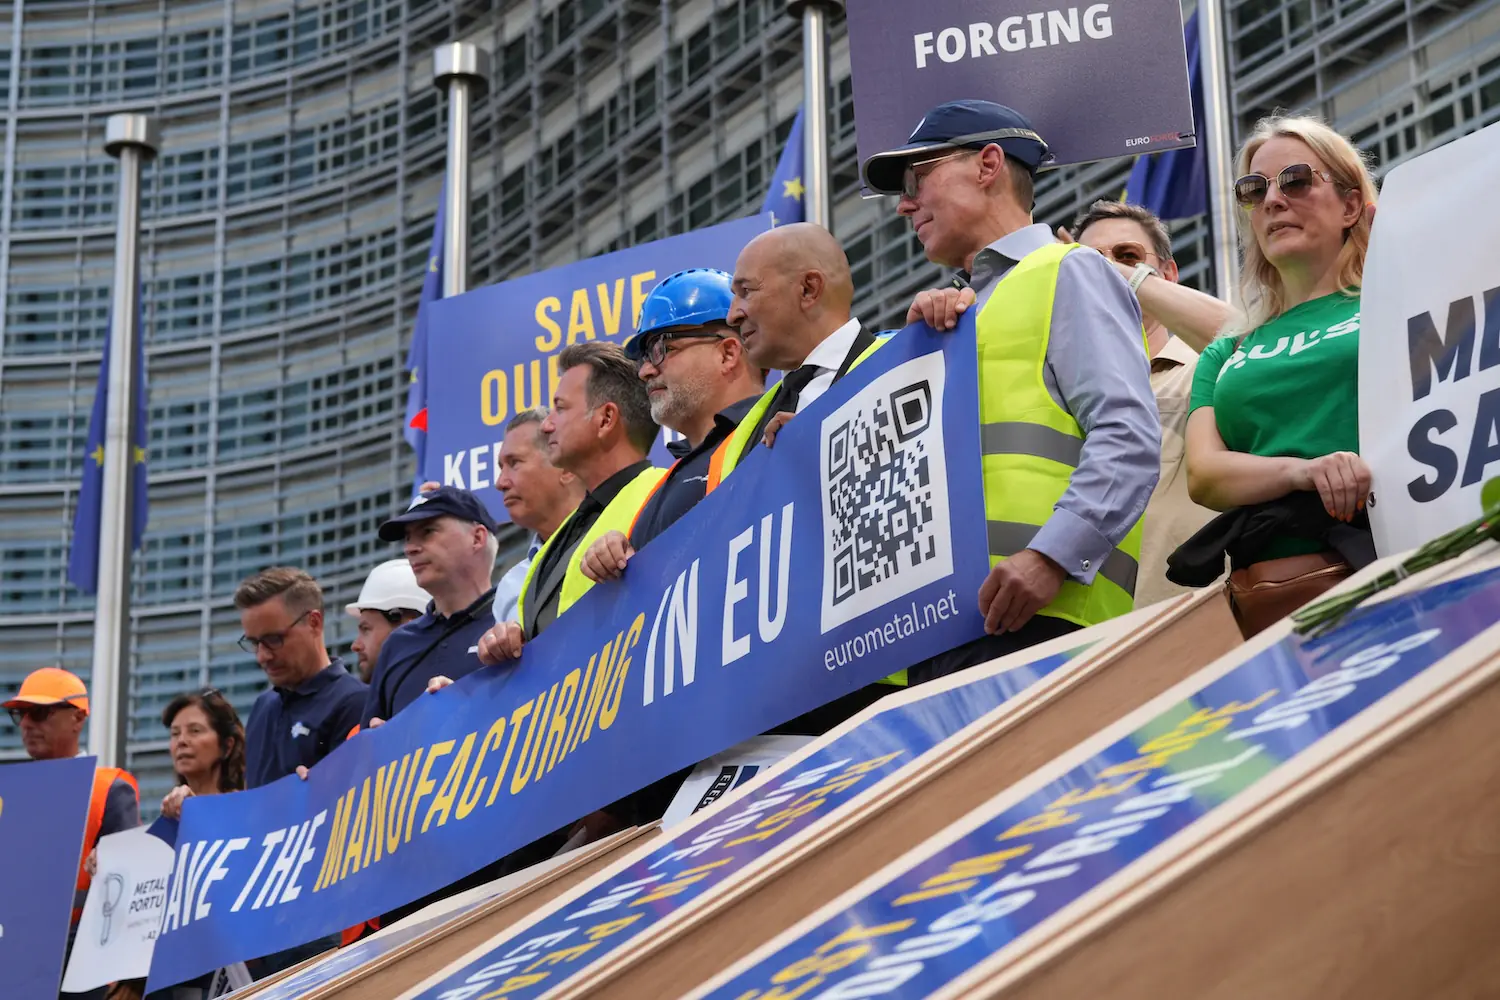
More than 200 representatives of Europe’s steel, metals distribution, processing, logistics and manufacturing industries took part in the European Convoy for Industrial Competitiveness in Brussels on 7 September.
Organised by EUROMETAL, the initiative brought 15 trucks and 10 symbolic industrial coffins to the European Quarter to highlight the growing pressures facing European industry and the urgent need to restore competitiveness throughout Europe’s manufacturing value chains.
Participants travelled from across Europe with one clear message: KEEP MANUFACTURING IN EUROPE.
A symbolic warning for European industry
While the truck convoy travelled through Brussels, a parallel procession carried 10 symbolic industrial coffins to the European Commission’s headquarters at the Berlay Sta. The convoy and procession arrived together, and the coffins were laid down to create a symbolic “graveyard of European industry”.
The installation represented companies, jobs, investments and manufacturing facilities threatened by the competitive imbalance between European producers and imported steel-intensive products. It reflected the industry’s concern that current policies risk accelerating industrial decline, investment leakage and the loss of highly skilled employment across Europe.
No representative of the European Commission met the delegation at the Berlaymont. A member of the Commission’s security staff received EUROMETAL’s position paper and Call to Action on behalf of the institution.
EUROMETAL now calls on the Commission to consider the industry’s proposals and engage in a substantive dialogue with the affected sectors.
Fair competition across the entire value chain
The convoy was neither a protest against Europe nor a rejection of its climate ambitions. It was a constructive appeal for policies that protect competitiveness, encourage investment, safeguard employment and strengthen Europe’s industrial resilience.
Steel produced in Europe—or imported directly into the European Union—is subject to extensive trade-defence measures, carbon costs and regulatory requirements. However, many imported steel-intensive manufactured products are not subject to equivalent obligations.
This imbalance creates a growing risk of downstream carbon leakage, production relocation and job losses throughout Europe’s industrial value chains.
Participants called for:
- Fair competition throughout the European steel and manufacturing value chain.
- Effective measures to prevent downstream carbon leakage.
- Trade and climate instruments that address steel-intensive manufactured goods where appropriate.
- Enhanced traceability and origin requirements.
- Stronger support for “Made in Europe” industrial value chains and strategic projects.
- Reduced unnecessary administrative burdens while maintaining Europe’s environmental ambitions.
“There can be no Green Deal without industry”
Alexander M. Julius, President of EUROMETAL, said: “The message of the convoy was simple: Europe cannot achieve its climate ambitions, strategic autonomy or economic resilience if it allows its industrial base to disappear. European manufacturers support decarbonisation and fair competition, but the regulatory framework must apply consistently across the entire value chain.
Today, too many steel-intensive products enter the European market without being subject to equivalent trade, carbon and regulatory obligations.
The result is investment leaving Europe, production moving abroad and skilled industrial jobs being lost.The trucks and coffins that arrived together at the Berlaymont symbolise a choice for Europe: either preserve and strengthen its manufacturing foundations or watch more factories become part of industrial history. There can be no Green Deal without industry, no strategic autonomy without manufacturing and no resilient Europe without strong European steel and metal value chains.”
Continuing the discussion at the European Parliament
Following the demonstration, participants were welcomed at the European Parliament by Elena Donazzan, Vice-Chair of the Committee on Industry, Research and Energy (ITRE), who supported the initiative and hosted a dedicated discussion on the future of European industrial competitiveness.
The exchange brought together industry representatives, policymakers and stakeholders to consider the legislative and regulatory changes needed to restore the competitiveness of Europe’s steel-using industries, retain investment within the European Union and preserve high-quality manufacturing employment.
EUROMETAL will continue to advocate for an industrial, trade and climate policy framework that supports strong, sustainable and resilient European value chains.
Europe’s industrial future can still be secured—but decisive action is needed to keep investment, innovation, production and employment in Europe.
EUROMETAL Brussels Convoy Press Release – 9 September 2026 EN
EUROMETAL Brussels Convoy Press Release – 9 September 2026 DE

Renew MEP Canfin calls to make ETS an ‘investment tool’
Reform of the EU’s carbon market will be judged a success if it speeds up investment in European decarbonisation, Pascal Canfin, Renew coordinator in the environment committee ENVI, told Contexte.
That would need to be matched by stronger demand for products such as green steel and cement, he said, with flanking measures such as the Commission’s proposed Industrial Accelerator Act helping to create that demand.
Canfin said he was “not completely at ease” with the Commission’s 17 July proposal to use ETS allowances to buy international carbon credits and fund investment outside Europe.
But he said quality could be assured by looking at standards developed by big development banks such as Germany’s KfW.
French readers can see the full interview transcript here.


Parliament rapporteurs seek to tighten ’Made in EU’ rules
According to a near-final version of the Parliament’s report on the Industrial Accelerator Act (IAA), obtained by Contexte, lead rapporteurs are seeking to narrow the conditions under which third countries can benefit from a status equivalent to ‘Made in Europe’ in public support schemes and public procurement.
The Commission proposed in March that all countries with a public procurement or trade agreement with the EU could be granted equivalent status, subject to exclusions for countries that do not offer EU producers the same treatment as domestic ones.
Pierre Jouvet (S&D), Anna Cavazzini (Greens) and Christophe Grudler (Renew) instead want the Commission to draw up a list of countries eligible for ‘Made in Europe’-equivalent status.
These countries would have to meet seven conditions, including equal treatment for EU products and compliance with the Paris climate agreement. In key sectors such as steel and electric cars, public procurement contracts and 90% of public aid would also have to include a minimum share of European content.
European preference could be waived if it increases the cost of a project by more than 40%, compared with 25% under the Commission’s proposal. Their report is due to be finalised on 9 September.
Assofermet Acciai: Prices rise, but demand and manufacturing remain weak
According to the latest monthly market report issued by Assofermet on September 7, activity in the Italian steel market has gradually resumed after the summer break, although demand remains weak and the international backdrop is largely unchanged from late July. Geopolitical tensions and persistently high energy costs continue to weigh on market sentiment and steel consumption.
In the carbon flat steel segment, European producers are seeking to establish a new upward price trend, supported by high energy costs and stronger trade barriers limiting steel imports. However, Assofermet warned that distributors and downstream manufacturers are finding it increasingly difficult to pass higher raw material costs on to customers without further undermining their competitiveness. The association therefore reiterated its call for trade and environmental protection measures, if maintained, to be extended to downstream products as well as primary steel production.
Attention also remains focused on the future of Acciaierie d’Italia. Assofermet expressed concern over the Milan Court of Appeal’s decision requiring the shutdown of hot-end production at the Taranto plant on October 28. The association has asked the Italian government for regular updates on the ongoing negotiations, given the strategic importance of the site for the country’s steel supply chain.
In the stainless flat steel segment, July remained weak in terms of both shipments and prices. During the first half of the year, producers managed to secure significant price increases, helped by tighter import availability, while distributors were only partially able to pass these increases downstream, resulting in margin pressure. Final demand nevertheless remains subdued, keeping overall market conditions fragile.
In the stockholding segment, the July-August period ended with an overall increase in sales value compared with the same period of 2025, despite lower distributed volumes. The improvement was mainly driven by higher average unit prices, also supported by the new EU safeguard measures in force since July 1, while volumes continued to suffer from weak downstream demand. Long products remained the weakest segment in volume terms, whereas hot rolled flats recorded increases in both volume and value. The hollow sections segment remained under pressure.
Stainless steel also continues to face difficulties, particularly in tubular and long products, while stainless flats have shown better resilience in value terms thanks to a recovery in average prices. Alloy surcharges for grades 304 and 316 have also been increased for September. According to Assofermet, the post-summer period will now provide an important test for European mills’ higher-price strategy, as weak consumption and elevated inventories could make it difficult for the market to absorb further increases.
On the regulatory side, from October 1 importers will also be required to document the country where imported steel was melted and poured. Assofermet noted that the outlook for the second half of the year is overall less negative than at the start of 2026, although distribution margins remain under pressure and uncertainty persists over the ability of downstream manufacturing to absorb the announced price increases.
Finally, in the tinplate segment, the tomato processing season has started positively, although supply availability for contracts in the coming months is expected to tighten. As a result, the metal packaging supply chain may increasingly turn to European producers or alternative origins such as Turkey and India as trade barriers continue to restrict other sourcing options.


European steel HRC suppliers seek higher prices, but downstream acceptance lags
Suppliers of steel hot-rolled coil (HRC) from Europe continued to seek higher prices on Monday September 7, amid limited supply from some mills and increased customer caution toward imported material.
Nevertheless, buying was limited on September 7 because strip prices, particularly in Italy, were still lagging.
Offer activity in the Italian market remained sparse. Despite restarting operations after an engine failure, Metinvest’s Ferriera Valsider operation has yet to resume making offers, according to a company source.
At the same time, Acciaierie d’Italia (ADI) is likely to be forced to stop steelmaking by October following a ruling by the Milan Court of Appeal issued on August 27.
This would leave Italy with only one hot-rolled coil supplier, which hoping to achieve price of €750 ($872) per tonne delivered, €730 per tonne ex-works.
Estimates of tradable prices from market sources were heard at €720-730 per tonne ex-works, while black sheet sales prices were heard at €820-830 per tonne delivered, netting back to €800-810 per tonne ex-works.
Nevertheless, considering the limited coil supply, market sources expected the sheet sector to show price increases this week.
“It looks like that upward price trend will further consolidate throughout September and the fourth quarter,” an Italian HRC producer said, “confirming the bullish sentiment justified by a supply-driven market, where the priority for all market participants will be to secure volumes before talking about prices.”
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy, was calculated at €727.50 per tonne on September 7, up by €4.79 from €722.71 per tonne on September 4.
The index was up by €10 per tonne week on week and by €18.75 per tonne month on month.
The Northern European market was relatively quiet during the day.
Suppliers hoped to achieve €760-790 per tonne ex-works for material scheduled for delivery in October-November, with tradeable prices indicated at €740-760 per tonne ex-works.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe, was calculated at €742.50 per tonne on September 7, down by €6.25 per tonne from €748.75 per tonne on September 4.
The index was up by €1.25 per tonne week on week and up by €25.00 per tonne month on month.
Availability in the region was affected by maintenance works at thyssenkrupp’s largest blast furnace (BF), which will continue until about mid-October.
In the import sector, activity was also limited because customers were cautious about safeguard quotas and uncertain about Carbon Border Adjustment Mechanism (CBAM) costs.
Indian material was heard available to customers in the region within the range of $660-670 (€568-577) per tonne CFR, although many buyers raised concerns over how fast the quota for the fourth quarter could be filled once open on October 1.
A cargo of Vietnamese material was heard booked at $670 (€577) per tonne CFR.
On a DDP basis, import material was available within the range of €710-750 per tonne, depending on origin, which led some buyers to opt for locally produced material.

Steel stakeholders stage rally in Brussels
Brussels will see a rally of trucks of steel, workers, business associations and industrial stakeholders from across Europe in the European Convoy for Industrial Competitiveness on Monday, organised by distributors’ association EUROMETAL.
The initiative centres on its goal to keep manufacturing in Europe, EUROMETAL points out. The association has been preparing for the event for many weeks.
The core of the protest is against the omission of steel-intensive manufactured goods and steel derivatives from the Carbon Border Adjustment Mechanism (CBAM), which is confined to immediate mill products.
The convoy of trucks will head to the European Quarter before representatives of European companies and associations. It will carry ten symbolic coffins around the Berlaymont, representing the manufacturing capacity, jobs and industrial know-how that Europe risks losing if current trends continue.
At noon, trucks will sound their horns simultaneously, delivering a symbolic wake-up call for Europe’s manufacturing future. This will be followed by the presentation of the convoy’s common message to a representative of the European Commission.
“We are not asking for subsidies or special treatment. We are asking for fair competition,” says EUROMETAL president Alexander Julius. “Our message is simple: if Europe wants to keep manufacturing, innovation and skilled jobs, it must ensure that the same principles apply across the entire manufacturing value chain. Keeping manufacturing in Europe is about preserving Europe’s prosperity, resilience and strategic autonomy.”
Author: Christian Koehl Germany


Greece based Corinth Pipeworks to produce 120,000 tonnes of steel pipes for Rovuma LNG


German steel association reacts to government over electricity cuts
“With the reintroduction of the subsidy for transmission grid costs, we only managed to bring soaring grid charges back to normal levels at the beginning of this year. Cutting this measure again so soon would send a fatal signal! The goal of permanently reducing electricity costs for industry would once again become a distant prospect, precisely at a time when the Middle East crisis is placing significant pressure on energy markets and pushing already volatile electricity prices even higher.”
“At a time marked by multiple threats and geopolitical uncertainties, the federal government should provide planning security for industry rather than roll back relief that has only just been introduced. Our demand is clear: the €6.5 billion in budgetary support must be maintained in full and on a permanent basis!”