


EPP, S&D propose lowering CBAM application threshold for aluminium to 5 tonnes per year
In an amendment to the proposed extension of the CBAM carbon border levy, the centre-right and centre-left groups suggest modifying the current threshold of 50 tonnes per year.
This current limit was agreed in a 2025 deal to simplify and limit the application of CBAM only to imports exceeding this yearly threshold.
In a separate amendment, some 40 MEPs from groups ranging from The Left to the EPP suggest relaxing the conditions for granting a temporary CBAM derogation to the EU’s outermost regions, which include territories such as the Azores or the Canary Islands.
This provision was included in the environment committee ENVI’s report. The energy committee (ITRE) also proposed an amendment to bring more steel products under CBAM’s scope in order to prevent risks of circumventing the levy.
Parliament is due to adopt its position on the CBAM extension proposal on 15 September.
A parliamentary source told Contexte that MEPs will also vote on whether to exclude methanol from CBAM’s scope on the same date.

Salzgitter AG appoints Christoph Martin as new CFO

Assofermet calls for continued production at Taranto steel plant

EU registers steel mesh imports from Türkiye and China
Alan Lovell appointed Chairman of British Steel

Federrec, A3M sign ‘unprecedented’ Green Steel Pact
French industry associations Federrec and A3M (Alliance of Ores, Minerals and Metals) signed an “unprecedented” cooperation agreement to stimulate French steel decarbonisation on 9 September, aiming to increase the share of recycled steel in national steel production.
Federrec represents France’s recycling sector, and A3M the French mining, metallurgy, steelmaking and metal recycling industries. The objective of the pact is to bring together both ends of France’s electrified steelmaking supply chain.
The press statement describes how France’s steelmaking and recycling sectors will enter a new era of collaboration under the pact, a “shift in perspective” to better appreciate that “recyclers and steelmakers now form two links in the same value chain.”
The partnership aims to “reindustrialise and transform French steelmaking” by bringing France into the top three European steel producers by 2035, increasing national production from 12 to 14 million tonnes annually, primarily via expanded electric-arc furnace (EAF) capacities.
According to the associations, realising this goal will require sufficient availability of affordable low-carbon electricity, additional investment, increased demand for low-carbon steels, regulatory alignments, and upstream development in the recycling sector to ensure French steelmakers can access necessary materials at increasingly mature technical standards.
“Today, we face a turning point rarely seen in history. […] A competitive, sovereign, and decarbonised industry can only be built with a strong and efficient circular economy,” said Raphaël Rey, President of A3M.
Federrec and A3M want the pact to build on the growing “momentum” in Europe to revitalise its industrial sovereignty, citing the European Commission’s efforts in implementing the Carbon Border Adjustment Mechanism (CBAM) and incoming lead market support policies in public procurement.
As such, the associations want to optimise scrap collection, processing, and utilisation for the benefit of its electrified steelmakers, considering France’s industries as well-positioned for the low-carbon transition due to strong national supply of scrap and low-carbon electricity.
Centered around five “strategic pillars” the pact seeks to:
- Support demand for low-carbon steel via the standardisation of green steel definitions and classifications, compatible with existing legislation, and integrated into public procurement mandates;
- Improve the scrap-to-steel supply chain for French steelmakers, working on scrap collection and traceability, trade flow monitoring (including potential export controls), and averting potential dependencies on e.g. direct-reduced iron imports (DRI).
- Improve steel scrap quality via technological upgrades, allowing recyclers to better align to steelmaker specification needs, and facilitate the production of a wider range of specialised or high-value steels (citing flat products).
- Strengthen economic and financing mechanisms within the French electrified steel supply chain, using “tailored financial mechanisms to secure long-term investments.”
- Promote industrial and regulatory “recognition” of recycled processes, via prioritisation in administrative procedures, such as project permitting, and better visibility of the strategic nature of Europe’s circular economy in policymaking.
A3M has a strong membership across France’s steelmakers, particularly electric-arc furnace producers, including national divisions of Aperam, CELSA, Dillinger, Marcegaglia, NLMK, Riva, and Saarstahl.
Author: Benjamin Steven


Czech Nova Hut granted EAF construction approval
Moravian-Silesian Region authorities have granted Czech steelmaker Nova Hut approval to build an electric-arc furnace (EAF), a company spokesperson told McCloskey.
The company plans to replace its currently idled blast furnaces (BFs) with an EAF as part of a decarbonization initiative. To learn more about decarbonization projects in Europe and globally, see McCloskey’s Global Green Steel Profile.
“We are one step closer to producing our own steel again in Ostrava. The construction of an electric arc furnace means full control over quality, self-sufficiency in input materials, and a sustainable future for the entire company,” said Radek Strouhal, CEO of Nova Hut.
The project will require further permits as it progresses. The final decision on whether Nova Hut proceeds with the EAF project is expected in October. The company will disclose the exact construction timeline once the final decision is announced.
The EAF will have a capacity of approximately 200 tonnes of steel per heat, Nova Hut said. Earlier this year, the steelmaker unveiled plans to invest in the decarbonization of the Ostrava steel plant, including the construction of an EAF that will have a capacity of up to 1.5 mt/y.
Nova Hut has no plans to resume BF operations and is currently operating rolling mills on imported slab and billet. In August this year, it reached an agreement under which 7 Steel Nordic, an EAF-based producer in Norway, will supply low-CO2 billets to be used as feedstock.
Nova Hut is equipped with hot strip, medium section, and wire rod rolling mills with a total capacity of around 3 mt/y.
In October 2025, a Czech consortium bought the Ostrava plant and rebranded it Nova Hut after Liberty Ostrava, the previous owner, was declared insolvent.
Author: Maria Tanatar
EU rapporteurs seek expanded green steel demand support
European authorities are moving toward increasing lead market support afforded to steelmakers under the Industrial Accelerator Act, according to a draft report by rapporteurs dated 8 September, re-introducing domestic content requirements in public procurement.
The report comes from the rapporteurs for the European Commission’s proposed Industrial Accelerator Act (IAA), each representing the committees jointly responsible for consulting on the IAA drafting process: the Committee on International Trade; the Committee on Industry, Research and Energy; and the Committee on the Internal Market and Consumer Protection.
The European Commission presented its proposal for the IAA back in March, seeking to deliver on commitments to implement policy stimulus for domestic low-carbon steel demand.
Unfortunately for steelmakers, contrasting industrial priorities between member states resulted in the ‘low-carbon steel label’ being cut from the Commission’s proposal, instead pursued under delegated acts of the Ecodesign for Sustainable Products Regulation (ESPR).
The published IAA proposal still contained requirements that public procurement of steel products source at least 25% of the total volume from low-carbon suppliers, but did not attach a requirement that these producers be based in the EU, as the Commission considered further restrictions on international supply unnecessary in view of July’s intensification to the EU’s steel trade framework.
Parliamentary committees have since been reviewing the IAA document, and on 8 September drafted just under 200 amendments to the proposal.
The committees’ suggestions contain two core developments: the re-introduction of domestic content requirements for the public procurement of steel, and the extension of “melted and poured” provisions to the interpretation of “Union origin.”
Public procurement mandates
The draft report brings a “Union origin” requirement back into the public procurement of steel products from 2029 – covering “steel, and any product the performance of which depends mainly on steel, intended for use in buildings, infrastructure and motor vehicles for civil purposes” – alongside the existing “low-carbon” requirement, both at 25% of the total volume.
This 25% low-carbon and Union origin threshold would then be increased to 35% from 2032, and to 50% from 2036.
Other amendments clarify the boundaries of what qualifies as low-carbon, unfortunately not yet in terms of specific numerical classification thresholds, but instead that material “shall be considered low-carbon where it falls within the two highest performance classes.”
These performance classes are still under review, though the Commission’s Joint Research Centre (JRC) has published its initial recommendations as part of its preparatory study for the ESPR delegated act for steel.
The JRC set these thresholds at a significantly higher level than most in the market expected, intending to ensure there was sufficient supply already contained within the highest classification (30% of availability) for a low-carbon mandate to be effective. However, this could compound in a lack of regulatory ambition across performance classes if drafting rationales are not aligned across the EU’s political institutions, for example if the JRC’s top classification remains inflated, despite the IAA’s acceptance of the runner up.
Union origin
On Union origin, the committees have tabled significant amendments, to the benefit of domestic steelmakers. Not only would Union origin be re-included in the procurement requirements, but the definition of Union origin would include an intensified version of the “melted and poured” clause newly contained in the EU’s July revision of its steel tariff rate quota (TRQ) framework.
To qualify as Union origin, a steel product – including “components and assembled final products containing steel” – must:
- have been originally melted and poured in the EU, referencing the same definition as the EU’s July steel TRQ regulation;
- have been produced using primary iron inputs of at least 75% Union origin, defined as iron ore “processed” via direct reduction or blast furnace within the EU.
Further committee amendments clarify that “processed” means the “solid-state reduction of iron ore into metallic iron through the application of a reducing gas or agent, excluding any subsequent briquetting, handling or transportation operations,” and that steel scrap is explicitly excluded from consideration as a “primary iron input.”
This would effectively mean that only steels within the required low-carbon classification thresholds, melted and poured in the EU from EU-origin DRI or pig iron would quality for the 25-50% procurement requirement. Scrap-based EAF producers could also presumably qualify, due to the percentage-based nature of the primary iron input requirement.
The draft report containing the amendments is scheduled for committee vote on 1 December, with an indicative first reading in the European parliament scheduled for 14 December.
Author: Benjamin Steven

German construction association lowers forecast for 2026
Germany’s construction industry has revised down its forecast for revenue in 2026 from a real increase of 2.5% to 1%, Kallanish hears from industry federation Hauptverband der Deutschen Bauindustrie.
The federation is echoing the scepticism expressed by research institutes regarding developments in the current year. “In view of the sharp slowdown in the construction sector up to and including May, and rising construction costs, our original forecast is no longer tenable. Residential construction, in particular, will take a hit: we now expect only a slight real increase of 0.5%, whereas in January we were still forecasting +2%,” says managing director Tim-Oliver Müller.
“The fact that we have not slipped into negative territory is solely due to the June figures, which showed a significant rise in orders and a slight increase in turnover (see Kallanish 21 August 2026). But it remains to be seen whether this really represents an unexpected turnaround or is merely a one-off monthly flash in the pan.”
The association’s assessment is confirmed by a recent survey among its member companies, according to which only 30% of respondents expected their revenue to rise this year, whilst just as many anticipated a decline. Three quarters of participants reported that they cannot hand down rising costs for materials and energy.
The federation cites recent figures from the federal statistics office, which show higher order intake in June by 11.3% year-on-year and by 6% compared with May. This suggests an improvement in the trend will come in the new year, Bauindustrie notes.
ING Bank recently issued a German construction growth forecast for 2027 of 2%. Although the assumed growth rates are modest, they would mean an end to downturn and stagnation. While European construction output recorded an average annual growth of 1.75% over the past five years, Germany’s sector declined by more than 10% between 2020 and 2025, ING writes.

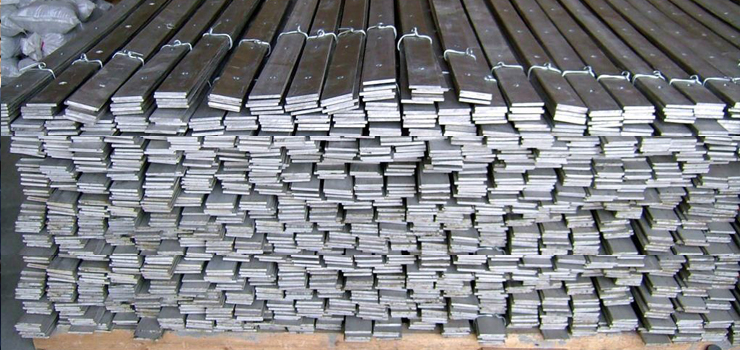
French flats prices rise, longs flat amid uncertainty
French long product prices are remaining mostly stable compared to the pre-holiday levels, though in some contracts and certain products moderate decreases are reported, Kallanish hears.
Since the activity resumption last week, the market has been uneventful with little appetite for material. Large steel processors report some financial difficulties and struggle to afford price increases.
Broadly speaking, with the flats and longs price increases seen in recent months, since the Middle East conflict started, margins have recovered, and volumes downstream are mostly stable year-on-year.
Over the course of the year, however, downstream margins have come under pressure from rising costs.
Looking ahead, pessimism is growing in the downstream sector as the French economy remains subdued and, according to the latest quarterly data, has only narrowly avoided recession. The construction sector, particularly private residential, remains weak, and the new infrastructure projects supported by post-Covid recovery funds are ending this year.
One large buyer, also pessimistic about the outlook, says the upcoming elections will slow activity. “Elections will have a strong impact on our business and this is happening during a period of great uncertainty,” he says.
In flat products, black hot rolled sheet prices are on the rise to €820-840/tonne ($957-980/t) delivered, in line with higher coil prices across Europe. This is up significantly from the level of €800/t seen at the end of July, just before the sector’s August shutdown.
Long product consumption remains limited as companies try to reduce exposure. Domestic merchant bar is at €290-300/t base delivered, excluding size extras of around €410/t, slightly below July levels as many buyers turned to Spanish producers offering competitive prices.
New contracts, however, are seen higher, with domestic merchant bar expected to recover to €310-320/t base delivered. Meanwhile, despite the several increase attempts for sections over the past months, prices for the first category material have remained stable at €800-810/t delivered.
Rebar levels are also flat compared to the pre-holiday levels with an uncertain market and limited volume orders. Values remain between €680-710/t delivered, sources suggest.