

Thyssenkrupp takes BF 2 at Duisburg offline for six-week refurbishment
German steelmaker thyssenkrupp Steel has announced that it will take its blast furnace (BF) 2 at the Duisburg site offline as planned for a partial refurbishment lasting approximately six weeks.
According to the company, the refurbishment is aimed at strengthening the operational stability of pig iron production and ensuring the reliable operation of the blast furnace in the coming years.
Cooling systems and refractory lining to be renewed
The work will focus primarily on the blast furnace’s central cooling systems and the heat-resistant lining in its lower section. Cooling components will be replaced, sections of refractory material will be renewed and additional copper cooling elements, known as mini-staves, will be installed. The mini-staves are intended to improve cooling in this heavily stressed section of the furnace and provide additional protection for the furnace shell.
At the same time, maintenance work will be carried out on auxiliary systems, including gas cleaning and slag granulation systems, with the overall work aimed at optimizing the technical availability of the blast furnace.
Blast furnace 2 was commissioned on October 28, 1993. With a daily pig iron production capacity of approximately 12,000 mt and a hearth diameter of 14.9 meters, it is the largest blast furnace in Europe, according to thyssenkrupp Steel.

WV Stahl and industry groups urge Germany to preserve emissions revenues for decarbonization
A coalition of 16 German industry associations, business initiatives and environmental organizations, including the German Steel Federation (WV Stahl), has called on the German federal government to abandon plans to divert €2.7 billion in emissions trading revenues from the Climate and Transformation Fund (KTF) to the general budget.
The planned diversion was approved by the German cabinet in July as part of the draft 2027 budget, which is currently under discussion in the Bundestag, as SteelOrbis reported previously. According to the coalition, the revenues are legally allocated to the KTF and should continue to finance the climate-neutral transformation of German industry.
WV Stahl among 16 organizations backing initiative
The initiative was launched by science-based industrial climate protection organization Bellona Deutschland and Stiftung KlimaWirtschaft. In addition to WV Stahl, the signatories include the German Chemical Industry Association (VCI), the German Foundry Industry Association (BDG), the German Cement Works Association (VDZ), the Association of Industrial Energy and Power Industry (VIK), the Nature and Biodiversity Conservation Union (NABU) and WWF Germany, among others.
The signatories stated that revenues generated through emissions allowance payments by industry and the energy sector should be returned in full to the companies concerned and used for climate-related purposes, particularly industrial decarbonization investments and reductions in energy costs. They also called for the subsidy for electricity transmission grid fees to be maintained in full.
Coalition warns of impact on investment planning
According to the coalition, reducing the amount of emissions trading revenues channeled back into industrial decarbonization would weaken the planning certainty required for long-term investments and negatively affect the international competitiveness of German industry.
WV Stahl CEO Kerstin Maria Rippel stated that the transition toward climate-neutral steel production requires reliable political framework conditions and that withdrawing billions of euros from the KTF would send the wrong signal. She added that the current Middle East crisis is putting additional pressure on energy markets and driving already volatile electricity prices higher. Rippel stressed that emissions trading revenues should consistently be used for decarbonization and reducing energy prices, adding that the German steel industry cannot withstand further burdens.
The coalition also argued that Germany needs broader fiscal reforms to consolidate its budget and create additional investment capacity, but stated that these measures should not come at the expense of climate-related investments or funding for industrial modernization.
Steel hot-rolled coil prices keep rising in Northern Europe amid tighter supply, costlier imports
Hot-rolled coil prices in Northern Europe continued climbing on Tuesday September 1, amid expectations of lower material availability in coming weeks due to maintenance work at Europe’s largest blast furnace, operated by thyssenkrupp, as well as rising import costs that have limited transactions.
Thyssenkrupp will take offline its blast furnace No. 2, which is capable of producing approximately 12,000 tonnes of hot metal, for around 60 days, the company said in a press release shared with Fastmarkets.
“This measure will enhance the operational stability of pig iron production, safeguarding a core element of steel production at the Duisburg site,” the company said, adding that the partial refurbishment focuses on work on central cooling systems and the refractory lining in the lower section of the blast furnace.
Cooling components will be replaced, parts of the refractory material renewed, and additional copper cooling elements installed.
At the same time, additional maintenance work will be carried out on auxiliary facilities, including the gas cleaning and slag granulation systems. The work is intended to improve the blast furnace’s technical availability and ensure reliable operation for years to come.
In such conditions, market participants expect reduced availability of the material from the supplier until the end of the year.
Combined with higher import prices, this has supported the upward price trend.
“DDP pricing of imports is now not too different to domestic pricing hence giving local mills a lot more pricing power,” one local buyer said, reporting indications in Antwerp at €720-740 per tonne DDP.
Although trading activity was modest in recent days, sources reported transactions within €740-760 per tonne ex-works, versus €730-760 per tonne last week.
Offers were at €750-780 per tonne ex-works, depending on supplier.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €748.33 ($868.21) per tonne on September 1, up by €7.08 per tonne from €741.25 per tonne on August 28.
The index was up by €18.33 per tonne week on week and by €37.08 per tonne month on month.
The Italian market was comparatively quiet. Metinvest remained out of the market, continuing to work on its engine issue.
Meanwhile, Acciaierie d’Italia (ADI) might be forced to stop steelmaking by October, following the recent court ruling.
Arvedi remained officially out of the market, with unofficial offers heard at €750 per tonne delivered or €735 per tonne ex-works.
At the same time, indications of tradeable levels were heard at €710 per tonne ex-works.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €712.5 per tonne on September 1, down by €5 per tonne day on day.
The index was down by €6.88 per tonne week on week and up by €6.25 per tonne month on month.


Parliament set to tighten ‘Made in Europe’ rules on social protection and climate grounds, S&D MEP says
The Commission’s proposal would allow companies from non-EU countries with a free trade agreement (FTA) or public procurement deal with the bloc to qualify for ‘Made in Europe’ status — but it does not go far enough, MEP Kathleen Van Brempt, vice-chair of the INTA trade committee and an S&D shadow rapporteur for the Industrial Accelerator Act (IAA), told Contexte on 1 September.
“The approach of the Commission is well intended, but it’s a bad compromise between DG GROW and DG TRADE,” said Van Brempt.
Disagreements between EU Industry Commissioner Stéphane Séjourné and the Commission’s powerful trade arm delayed the IAA’s proposal multiple times.
Eventually, the Commission presented the IAA, which contains ‘Made in Europe’ requirements for subsidies and public procurement in specific sectors such as wind turbines and solar panels.
Parliament will instead start with the 27 EU member states, with the possibility of an opt-in for EU partners “based on very clear criteria” of social protection and climate policy, while taking FTAs and public procurement deals into account, the Belgian MEP said.
The upcoming joint IMCO–ITRE–INTA committee report on 10 September and subsequent amendments will detail the reciprocity terms for the opt-in, she said.


Blastr Green Steel ceo to depart
The chief executive officer of Blastr Green Steel (BGS), Mark Bula, is to leave the company, Kallanish learns.
A published statement by the company says that Bula and Blastr “have reached an agreement regarding his departure” from the company. Bula was appointed as ceo in April 2024.
“Mark has played a key role in bringing Blastr to where it is today, and the board would like to thank him for his contribution,” says Olaf Wigstol, chairman.
A Blastr Green Steel spokesperson tells Kallanish: “We can confirm that BGS ceo Mark Bula is stepping down from his role, allowing for an orderly transition period. [The] current cfo, David Morant, will become ceo of BGS UK.”
They add that Morant is an experienced executive with more than 20 years in capital markets and has held senior leadership roles in companies involved in the industrial economy in the UK and worldwide.
The statement adds that the board and management team remain fully committed to the continued development of the Blastr companies and to maintaining strong relationships with its partners, suppliers and employees.
“All existing business operations and commitments continue as normal,” it concludes.
The low-carbon emissions project has not yet reached a final investment decision (FID) but was moving towards permitting in a March 2025 update.
Blastr is understood to still be in the running to acquire Speciality Steel UK (SSUK), with talks with the Insolvency Service still ongoing as the preferred bidder.
Sources familiar with the matter say Morant has been heavily involved with the negotiations for the potential takeover of SSUK.

ArcelorMittal increases longs prices: sources
ArcelorMittal is raising its long product prices by a further €20/tonne ($23.3/t) for commodity grade sections, rebar and wire rod, market sources tell Kallanish.
This follows the previous increase implemented in July of €25/t, bringing the total increase to €45/t.
The market environment remains challenging for producers, with the instability of the Middle East conflict pushing up gas and electricity costs, which are critical for electric arc furnace steelmakers.
One source warns that electricity costs have soared beyond affordable levels, leaving producers with two options: pass on the increases or implement heavy production cuts across Europe in the coming months.
Several sources describe the European long product market as extremely quiet, with the holiday period and heatwaves keeping activity at a standstill. “The main issue is that in terms of costs there is no stability. Scrap is the only cost that is stable, but energy continues to soar, both gas and electricity, compared to before the summer. This conflict seems to have no conclusion, and it’s having a huge impact on all EAF producers,” a source says.
Another says that increases implemented before the summer are not enough to cover all costs and believes several long producers will implement further hikes in the coming weeks hoping that sales activity will pick up in September.
Wire rod sales remain slow and the market challenging in both south and northern Europe as well as rebar, a segment plagued by uncertainty.
European scrap prices have remained mostly stable in August, Kallanish notes.
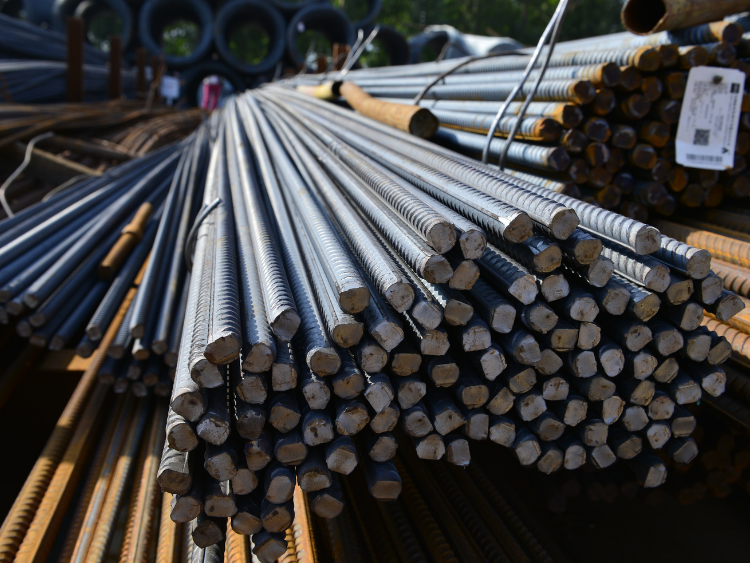
German rebar price resurge not yet materialising
Rebar prices in Germany have stabilised from the dip that occurred a month ago, but a notable uptick has not come about.
Base prices softened from mid-July into August, undercutting the mark of €400/tonne ($466/t), with quotes as low as €380/t heard from large rebar benders, and even lower than that heard from southern Germany.
Several buyers tell of enhanced purchasing activity during that period. They also note signals from mills to announce more solid prices, at least keeping the €400/t level, but ideally heading for €10-20/t more, according to one central German buyer.
But a clear word has not been heard from the mills, a manager of a relatively small northern German bender tells Kallanish, and says he can still place orders for €400/t.
In southern Germany, one commentator claims that €380/t is still possible, with equal prices from German and Italian mills, and attributable to the competition from both sides in the south. He also denies that the earlier buying spree was very big at all.
He concedes that the mills are dealing with higher transport costs, and have a point to ask for higher prices, but adds that “the market speaks a different language”.
Only one mill that is particularly impaired from the low water level of the Rhine River had asked for €10/t extra as compensation for additional logistics costs, he says.
All base prices need to add a size extra customarily of €265/t.

European coil and green steel round-up: EU coil price rise to resume in September
European domestic hot-rolled coil (HRC) prices increased in the week to 28 August as both buyers and sellers returned to the market after the holidays.
Apart from seasonal demand recovery, the price rise was driven by limited availability – European buyers had to seek larger volumes in the domestic market following the introduction of tougher new tariff-rated import quotas in July and the Carbon Border Adjustment Mechanism (CBAM). Both policies, combined with the effects of traditional trade measures, made imports riskier and more costly, cutting access to overseas steel.
“Prices for imported steel are higher than those for European products. And prices that seem lower on a CIF basis turn out to be very risky if you account for CBAM and other duties,” a Benelux service center said.
Logistics and technical issues at European plants have further supported bullish sentiment in the market.
Market participants estimated achievable prices for HRC in Northwest Europe at EUR730–760/t ex-works; a few transactions have been reported within the range. Some market sources, however, believe that prices of EUR730/t ex-works are not available to average buyers and that realistic prices are at EUR740/t ex-works at a minimum.
Import offers in the region have been limited, with HRC prices heard at EUR 740/t DDP Antwerp.
Activity has not fully recovered after the holiday lull, but trading activity is expected to pick up at the beginning of September. Market participants expect prices to reach EUR750–760/t ex-works by the end of next month, and some believe prices will reach EUR800/t ex-works by the end of the year.
The region’s steelmakers have been offering November–December production HRC, and some have already sold out 2026 downstream products, notably cold-rolled coil (CRC).
Several sources reported delivery delays from German mills due to logistics disruptions and production cuts caused by low water levels on the River Rhine.
Concerns are growing among buyers that the European production increase resulting from the restart of blast furnaces (BFs) will not be enough to substitute for cut import volumes caused by regulatory changes.
This year, ArcelorMittal resumed operations at three of its BFs, and Germany’s Hüttenwerke Krupp Mannesmann (HKM) is preparing to restart a furnace.
However, in southern Europe, a region traditionally more dependent on imports, domestic supply could be reduced further, and some volumes from resumed capacities may be redirected there. On 27 July, the Milan Court of Appeal ordered Acciaierie d’Italia (ADI) to shut down operations in the hot section of its Taranto steel plant within 90 days. The extraordinary administration of the plant disclosed plans to appeal to the Cassation Court, but the order remains in place at the end of August.
New potential buyers of ADI emerged in the middle of the month: the Italian steelmakers’ association, Federacciai, submitted a letter of interest for the Taranto steelworks on behalf of a new consortium of 14 companies: Acciaierie Bertoli Safau (ABS), Arvedi, Acciaierie Venete, Advanced Steel Solutions (Asonext group), Beltrame, Alfa Acciai, Compagnia Siderurgica Italiana, Duferco Travi e Profilati, Feralpi, Valsabbia, Lucchini RS, Marcegaglia, ORI Martin, and Rubiera Special Steel.
While the steelmaker has been operating only one furnace and has not been active in the spot market, the absence of its material would hit major buyers – re-rollers and pipe makers – who use ADI’s HRC as feedstock.
Italian producers have not returned to the market with new HRC offers yet, but market participants estimated that prices below EUR720/t ex-works would be rejected by sellers.
Import offers for material from Asia have been heard at EUR720–740/t DDP Italian ports.
Green Steel Market
Activity in the European green steel segment has remained muted, with buyers more focused on rising prices for traditional steel.
Workable premiums for green HRC have been reported at EUR100–150/t. But spot buyers have shown interest in low-CO2 steel mainly as part of back-to-back deals with end consumers.
Sales directly to end users, such as in the automotive and construction sectors, remain the main drivers of green steel demand.
| Weekly European steel coil | |||||
| EUR/t | Term | 28-Aug-26 | Change | ||
| Weekly Northwest Europe steel coil | |||||
| Northwest Europe ex-works HRC | EX-WORKS | 740.00 | 15.00 | ||
| Northwest Europe ex-works CRC | EX-WORKS | 835.00 | 0.00 | ||
| Northwest Europe ex-works HDG | EX-WORKS | 830.00 | 0.00 | ||
| Northwest Europe CIF HRC | CIF | 585.00 | 0.00 | ||
| Northwest Europe DDP port HRC | DDP Port | 740.00 | 40.00 | ||
| Weekly South Europe steel coil | |||||
| Italy ex-works HRC | EX-WORKS | 720.00 | 15.00 | ||
| South Europe CIF HRC | CIF | 580.00 | 0.00 | ||
| South Europe DDP port HRC | DDP Port | 720.00 | 20.00 | ||
| South Europe CIF CRC | CIF | 680.00 | 0.00 | ||
| South Europe DDP port CRC | DDP Port | 765.00 | 0.00 | ||
| Show less… | |||||
| Source: McCloskey by OPIS. | © 2026 Dow Jones Energy Limited. | ||||
| Weekly green steel | |||
| EUR/t | Term | 28-Aug-26 | Change |
| Green Northwest Europe HRC premium (scopes 1-3 CO2 under 0.8t) | 100.00 | 0.00 | |
| Green Northwest Europe ex-works HRC (scopes 1-3) | EX-WORKS | 840.00 | 15.00 |
| Green HRC premium (scopes 1-2 CO2 under 0.5t) | 100.00 | 0.00 | |
| Green Northwest Europe ex-works HRC (scopes 1-2) | EX-WORKS | 840.00 | 15.00 |
| Green HRC reduced carbon price (scopes 1-3) | 72.25 | 7.26 | |
| Source: McCloskey by OPIS. | © 2026 Dow Jones Energy Limited. | ||
Author: Benjamin Steven & Maria Tanatar


European heavy plate round-up: Italian plate prices gain as sellers return from holidays with firmer offers
Italian plate prices jumped in the week to 28 August, as market participants began to return from summer holidays to higher price ambitions from domestic steelmakers.
While market activity is still very limited – expected to recover next week once in the September trading period – initial indications from the Italian heavy plate market were at higher levels, with deals settled at EUR720-730/t ex-works.
The continued availability of these deals was doubted, with sellers reporting new price ideas of EUR740-750/t ex-works for fresh orders. Buy-side sources in fact reported higher indications, expecting offers of EUR750-760/t ex-works Italy once the market fully returns in September.
Italian re-rollers were more sceptical of near-term bullishness in the heavy plate segment than in other steel products – such as hot-rolled coil – due to the visibility of declining slab prices through the summer.
Foreign steelmakers have shifted export strategies toward semi-finished, rather than finished steel goods, due to the relatively unshielded nature of the EU’s semi-finished steel demand in the wake of the EU’s revision to its tariff-rate quota protections, in July. However, recent hikes in raw materials costs mean re-rollers now anticipate higher slab costs in September’s contract negotiations – above most recent offers at $560/t CIF – potentially giving Italian heavy plate sellers better ammunition to convince buyers to pay more.
In Northwest Europe, German mills are well booked from project demand, and so have little allocation available for spot buyers. As such, indications for fresh production, ex-Germany, were commonly reported above the EUR800/t ex-works level on week, with offers to Germany also reported from Italy at EUR780-820/t delivered for s235jr grade, and from Central Europe at EUR830-850/t delivered for s355jr grade.
| Weekly European heavy plate, slab and green steel | |||||
| Unit | Term | 28-Aug-26 | Change | ||
| Weekly heavy plate | |||||
| Northwest Europe ex-works heavy plate | EUR/t | EX-WORKS | 830.00 | 0.00 | |
| Germany delivered heavy plate (Northwest Europe) | EUR/t | DEL | 830.00 | 20.00 | |
| Italy ex-works heavy plate | EUR/t | EX-WORKS | 730.00 | 30.00 | |
| Weekly steel slab | |||||
| Italy CFR slab | $/t | CFR | 560.00 | 10.00 | |
| Weekly green steel | |||||
| Green heavy plate premium (scopes 1-3 CO2 under 1t) | EUR/t | 25.00 | 0.00 | ||
Author: Benjamin Steven & Maria Tanatar

Blastr announces departure of CEO Mark Bula
Blastr Green Steel, a low-carbon steelmaker developing new greenfield assets in Finland, has announced the departure of its current CEO, Mark Bula.
“Mark has played a key role in bringing Blastr to where it is today, and the Board would like to thank him for his contribution,” Blastr said in its press release.
Blastr said that “all existing business operations and commitments continue as normal,” with the company “fully committed to the continued development of the Blastr companies and to maintaining strong relationships with our partners, suppliers and employees.”
In a separate social media post, Bula clarified that he will stay on in a limited capacity to support Blastr with an “orderly handover” of his responsibilities. Bula held the CEO role at Blastr for just over two years, previously working on steel transformation projects at Big River Steel in the US, before moving to serve as CCO at rival greenfield steelmaker H2 Green Steel – now Stegra.
Bula went on to highlight Europe’s steel industries as an example of how the domestic policy environment remains insufficiently supportive of actually realising industrial decarbonisation, describing “an uncomfortable tension between wanting cleaner, more secure domestic supply chains and opposing the mines, power generation, transmission, ports, railways and industrial facilities required to create them.
“If we aren’t prepared to build them in G7-aligned economies, we should not be surprised when more of the world’s industrial capacity is built somewhere else.”
As described in McCloskey’s Global Green Steel Profile, Blastr is constructing new low-carbon electric-arc furnace-based (EAF) steelmaking capacity in Inkoo, Finland; consisting of a hydrogen electrolyser, a 2 mt/y direct-reduced iron (DRI) plant, and a 2.5 mt EAF, with slab casting and rolling line facilities.