

European long steel market quiet as summer holidays curb trading activity
European domestic long steel prices remained stable in the week to Wednesday August 19 amid thin liquidity, seasonal mill closures and subdued demand.
“Market is on holiday at the moment,” a seller source told Fastmarkets.
Market participants said activity remained limited during the assessment week, with ongoing production stoppages across Europe restricting both buying and selling activity.
No new transactions were heard during the assessment week.
In Italy, tradable levels for rebar were heard at €690-730 ($799-845) per tonne ex-works.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, exw Italy, remained unchanged at €690-730 per tonne on Wednesday August 19.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, delivered Spain, was unchanged at €750 per tonne on the same day.
Tradable levels for rebar in Northern Europe were heard at €710-730 per tonne delivered.
Meanwhile, Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, delivered Northern Europe, was unchanged at €710-730 per tonne on August 19.
Wire rod prices followed a similar trend, with weak demand and limited trading activity supporting stable prices during the assessment week.
In Southern Europe, tradable levels for mesh-quality wire rod were heard at €660-680 per tonne delivered.
Fastmarkets’ weekly price assessment for steel wire rod (mesh quality), domestic, delivered Southern Europe, was unchanged at €660-680 per tonne on August 19.
In Northern Europe, tradable levels for mesh-quality wire rod were heard at €705-715 per tonne delivered.
Fastmarkets’ weekly price assessment for steel wire rod (mesh quality), domestic, delivered Northern Europe, was unchanged at €705-715 per tonne on the same day.


Italy’s Ferriera Valsider declares force majeure at north Italian steel plant
Italian steel reroller Ferriera Valsider declared force majeure at its plant located in Vallese di Oppeano on Aug. 17, owner Metinvest confirmed to Platts, part of S&P Global Energy.
“Ferriera Valsider has experienced a force majeure event that has resulted in the suspension of production,” Metinvest said in a statement shared via email. “The company has informed its customers, suppliers and other relevant stakeholders accordingly.”
Metinvest said technical teams are working to “define and implement the shortest possible action plan for the necessary repairs,” with the aim of restoring production as soon as possible, it added.
However, Metinvest said that assessment of the incident is still underway and that it cannot yet provide a timeframe for the restart of operations.
In a letter dated August 2026, sent to its buyers and seen by Platts, Ferriera Valsider said the event had triggered clause 8, the force majeure provision in its general terms and conditions of sale governing customer contracts. The letter described the incident as an “extraordinary, sudden and unforeseeable breakdown” that was beyond the company’s reasonable control.
The incident resulted in the “immediate and complete shutdown” of Ferriera Valsider’s production lines, according to the letter.
“At this time, we are unable to determine the duration of the force majeure event, which is expected to be significant,” the company said in the letter.
Ferriera Valsider said it had taken “all necessary and appropriate actions to manage the emergency,” and told customers it would provide an update on the situation by the end of August.
The company also said sales representatives would contact buyers individually to discuss current orders.
Ferriera Valsider did not disclose the nature of the issue, the equipment affected or the expected volume impact.
Ferriera Valsider is based in Vallese di Oppeano, in the province of Verona, northern Italy, and operates as one of Metinvest’s European steel rerolling facilities, producing steel plate and hot-rolled coil. The company supplies steel plate for shipbuilding, energy, construction and infrastructure applications in the EU, according to Metinvest’s Ferriera Valsider website.
Along with Metinvest Trametal in San Giorgio di Nogaro, Ferriera Valsider is part of Metinvest’s Italian plate rerolling platform, with the two units having about 1.2 million metric tons/year of flat-product capacity across plate and hot-rolled coil, according to the company’s website.
Platts assessed heavy plate in Italy at €710/mt ex-works on Aug. 14, stable week over week but down €60 from the 2026 high in April. Platts assessed imported slab in Italy at $550/mt CIF on Aug. 14, unchanged week over week and down $50/mt from the 2026 high in June.
Salzgitter reshuffles HKM management after acquisition
Salzgitter is appointing a new management team for its Duisburg slab mill after the acquisition of Hüttenwerke Krupp Mannesmann (HKM).
As part of the reorganisation, Andreas Betzler has assumed the role of chief financial officer and spokesperson for the management board, Kallanish learns.
As head of post-merger integration, La-Toya Müller will support and drive the organisational and cultural integration of HKM into the Salzgitter group.
Heiko von Hagen has been appointed as the new managing director of production. He was most recently responsible for the allocation of HKM slabs within the group and draws on extensive experience from his collaboration between HKM and Salzgitter.
Martin Zappe, programme director of decarbonisation campaign SALCOS, will shape the next crucial steps in the construction of Germany’s largest electric arc furnace in Duisburg, Salzgitter says,
At the same time, Peter Biele, who has served as HKM’s chief technology officer, will be leaving the company. “Peter Biele led HKM with great dedication and a high level of professional expertise during challenging times, providing important impetus for the company’s further development,” says Salzgitter ceo Gunnar Groebler.
Carsten Laakmann, will remain as managing director of human resources, with the executive team alongside Andreas Betzler, Heiko von Hagen, and Martin Zappe.


Local European HRC prices edge up slightly in slow market; import levels into Southern Europe narrow downward
Domestic prices for steel hot-rolled coil edged up on August 19 in both Northern Europe and Italy, but market activity was still mostly slow in the region due to the summer holiday period, sources told Fastmarkets on Wednesday.
In Northern Europe, latest transactions were reported within the range of €710-730 ($822-845) per tonne ex-works, but a buyer said “these levels were unlikely to be repeated,” while indications were heard at the same range.
Offers were heard at €730 per tonne ex-works in Germany. Higher levels from mills were reported at €760-790 per tonne ex-works, but the first buyer said that “the new offer levels have yet to be tested, as many buyers are either away for the summer holidays or maintaining a wait-and-see approach.”
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €723.33 per tonne on August 19, up by €0.83 per tonne from €722.50 per tonne on August 18.
The index was up by €6.33 per tonne week on week and up by €13.33 per tonne month on month.
In Italy, the market was still mostly quiet because of the traditional slowdown in trading activity during August.
An offer was reported at €715 per tonne ex-works on Wednesday, while an indication was heard at €700-720 per tonne ex-works.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €712.50 per tonne on August 19, up by €1.25 per tonne day on day from €711.25 per tonne on August 18.
The index was down by €1.25 per tonne week on week but up by €7.50 per tonne month on month.
Meanwhile, latest HRC import activity included offers from Turkey at €575 per tonne CFR with added anti-dumping duties of €35 per tonne, and some Italian buyers were keen to pay this price, according to sources.
Offers from Indonesia were reported at $620-625 per tonne CFR, but in order to accelerate delivery time, extra freight costs of $30 per tonne were applied, so the final price was around $650-655 per tonne CFR.
However, there was no buying interest for material with this origin because of higher costs under the Carbon Border Adjustment Mechanism (CBAM).
And offers from India were within the same range as Indonesia, at $650 per tonne CFR, or around €560 per tonne CFR, sources told Fastmarkets on Wednesday, but no bookings were done.
Fastmarkets’ weekly price assessment for steel hot rolled coil import, cfr main port Southern Europe was at €560-575 per tonne on August 19, narrowing downward from €565-600 per tonne a week earlier.
–Vlada Novokreschenova in Dnipro contributed to this article.

EC relaxes funding conditions for thyssenkrupp’s transition
The European Commission has eased the conditions for the public funding of the technical transition undertaken by thyssenkrupp Steel to convert its oxygen mills into hydrogen-fuelled DRI plants.
“The EU has approved the legal grounds for the newly adjusted logic of subsidisation of our direction reduction plant,” tk Steel confirms to Kallanish in a statement.
It is believed that the Commission’s concession is linked to the postponement of hydrogen usage in the converted process.
According to EUToday, the original public-funding conditions assumed that sufficient renewable hydrogen would be available at an affordable price. That assumption has not been met on the expected timetable, and it is more likely that the converted mill will have to run on natural gas during an extended transition period.
The Commission has allowed the project to proceed under altered assumptions.
The project in its entirety has an investment budget of €3 billion ($ 3.5 billion), of which two thirds will be publicly funded.
Following the Commission’s nod, the German government must now adjust the formal funding decisions, tk Steel says in its statement.
Çolakoğlu Metalurji: EU quota decision will impose greatest cost on its own steel consumers
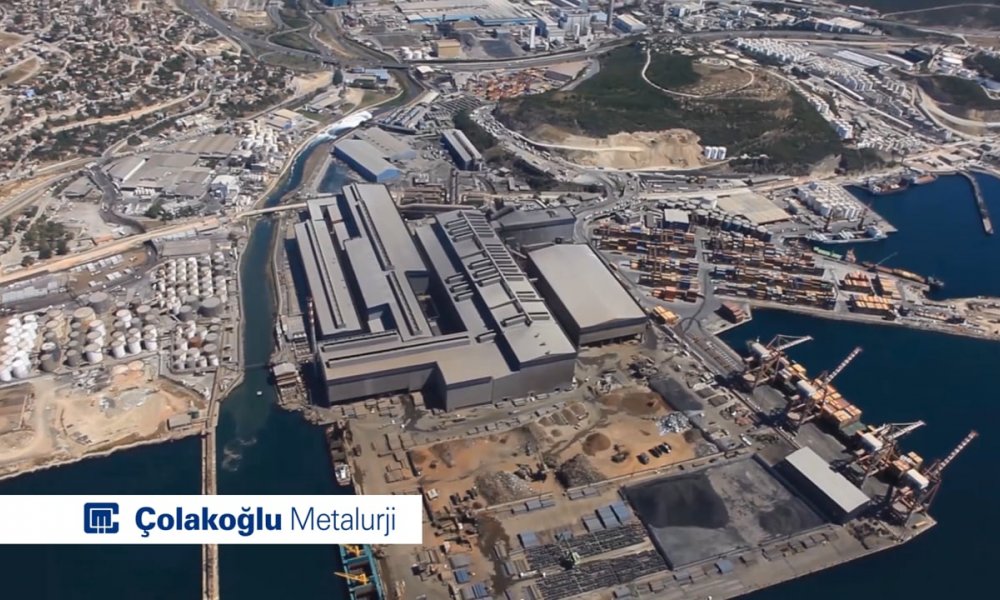
We spoke with Gökhan Erdem, sales and marketing director at Çolakoğlu Metalurji, about the potential impact of the EU’s new steel import quotas on Turkey’s exports and European steel consumers.
As is known, the EU has revised its steel import regime, reducing the steel import quota allocated to Türkiye in the HRC 1A category by 60 percent. Ultimately, the greatest cost and risk arising from this measure will be borne by steel consumers within the EU. European consumers will have to assess the additional costs they will need to bear in order to continue their operations in the future and assume increasing risks to maintain their activities under these conditions.
As domestic steel prices in the EU continue to rise, the resulting cost burden on steel consumers may also lead to uneven cost impacts among EU member states depending on their respective steel production capacities. Turkey’s steel exports to the EU will continue, albeit at lower levels, but the majority of the additional costs will ultimately be borne by steel consumers based in the EU.
Another factor is that, as the impact of CBAM becomes increasingly pronounced over time, the advantages offered by Turkish production in terms of carbon footprint, geographical proximity, quality, clean steel and reliable imports will create additional pressure on EU steel consumers.
Following these developments, the Turkish steel industry has the ability to adapt in steel export markets thanks to its experience with such measures and its capacity to respond rapidly and flexibly under changing conditions. As the impact of the new measures becomes increasingly apparent over time, higher costs in the EU will continue to put pressure on EU labor markets. In addition, more significant structural shifts, such as EU-based steel consumers relocating their operations outside the region, could also be among the potential consequences of this process.


EC publishes sector-specific CBAM guidance for iron and steel to help non-EU operators
The European Commission (EC) has published its sector-specific guidance for iron and steel under the Carbon Border Adjustment Mechanism (CBAM) to help non-EU operators, providing detailed rules on calculating and monitoring embedded emissions during the definitive period beginning in 2026.
According to the guidance, iron and steel imports are divided into six main aggregated goods categories: sintered ore, ferro-alloys, pig iron, direct reduced iron (DRI), crude steel and iron or steel products. The latter category covers a wide range of products, including flat steel, bars, rods, wire, sections, tubes, pipes, structural products, tanks, containers and fasteners.
Direct emissions generally apply to steel products
For iron and steel products, only direct emissions are generally included in embedded emissions during the definitive period. The main exception is sintered ore classified under CN 2601 12 00, for which electricity-related indirect emissions must also be calculated. When sintered ore is subsequently used as a precursor for another steel product, these indirect emissions are carried forward into the embedded emissions of the downstream product.
The Commission also clarified that complex steel goods must incorporate emissions embedded in their relevant precursors, including sintered ore, pig iron, DRI, ferro-alloys and crude steel. Post-consumer scrap is assigned zero embedded emissions, as are relevant precursors produced in the EU or CBAM-exempt countries and territories.
EAF electricity emissions excluded from crude steel calculations
For electric arc furnace-based steelmaking, electricity-related emissions are not included in the definitive-period embedded emissions of crude steel despite electricity being the route’s principal energy input. However, direct emissions arising from fuels, electrodes, carbon-containing materials and other relevant sources must be calculated.
According to the guidance, operators are allowed to combine several production stages into a single production process, or “bubble,” under certain circumstances. For example, an integrated steel producer may combine sinter, pig iron and crude steel production with downstream operations when internally produced precursors are entirely consumed within the installation and are not sold or transferred separately.
Weighted averages apply to different production routes
Where the same goods are produced through different routes at one installation, their specific embedded emissions must generally be calculated using a weighted average. A similar principle applies to precursors sourced from different installations or production periods unless sufficient evidence allows particular batches to be attributed to a specific production process.
The document also establishes additional reporting requirements for steel producers. For pig iron and DRI, required information includes the main reducing agent and certain alloying-element contents. For crude steel and finished steel products, operators must report information including scrap consumption per ton of product and the proportion of pre-consumer scrap.
Actual emissions require monitoring and verification
Operators seeking to use actual emissions values must maintain an English-language monitoring plan and retain supporting documentation for at least six years.
Actual emissions data for externally sourced precursors may be used only when supported by a verification report from an appropriately accredited verifier. Otherwise, the relevant default values must be applied.
CBAM calculation examples for steel products
In a worked example for an integrated blast furnace-basic oxygen furnace steelworks, the Commission calculates specific embedded emissions of 1.567 mt of CO₂ per mt of finished steel, including indirect emissions associated with sinter production. For a hypothetical 2027 import of 10,000 mt of rails, this results in 15,670 mt of embedded emissions and, following the applicable free-allocation adjustment, an obligation to surrender 3,690 CBAM certificates, before accounting for any eligible carbon price paid in the country of origin.
In another example covering stainless steel produced through the EAF/AOD route, finished products have calculated embedded emissions of 1.783 mt of CO₂ per mt. A hypothetical 100 mt import of stainless steel pipes in 2027 results in an obligation to surrender 95.9 CBAM certificates following the free-allocation adjustment and before any deduction for an eligible foreign carbon price.
Material losses can increase embedded emissions
The guidance also addresses downstream products such as screws and nuts. Since material lost during cutting and machining does not carry over into the final product, these losses can increase embedded emissions per ton of finished goods. In the Commission’s example, specific embedded emissions reach 2.039 mt of CO₂ per mt for carbon steel screws and nuts and 2.371 mt per mt for stainless steel screws and nuts.
Lastly, the EU emphasized that the sector-specific guidance is explanatory rather than legally binding, with applicable EU legislation taking precedence.

European hot-rolled coil trading remains subdued in summer slowdown
Trading activity remained subdued across the European domestic hot-rolled coil market on August 18 as summer holidays continued to keep many buyers and sellers away from business.
Sources contacted by Fastmarkets said they would start returning to work the following week, with business activity expected to recover by September.
As of August 18, the most recent deals for October-delivery material heard in Northern Europe were from the end of the previous week, with prices in the range of €715-730 per tonne ex-works.
Market participants confirmed this range remained workable, with offers at €740-750 per tonne ex-works.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €722.50 per tonne on August 18, up by €2.50 per tonne from €720.00 on August 17.
The index was up by €5.62 per tonne week on week and up by €36 per tonne month on month.
The Italian market was similarly quiet, with market participants indicating a tradable level of €705-710 per tonne ex-works, versus offers at €720 per tonne ex-works.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €711.25 per tonne on August 18, up by €0.25 per tonne day on day from €711.00 per tonne on August 17.
The index was down by €2.50 per tonne week on week but up by €6.25 per tonne month on month.
Flats surge lifts Ukraine July steel imports: MCI
Ukraine imported 199,706 tonnes of steel products in July, up 20% on-year. This lifted January-July imports by 7.1% on-year to 1.14 million tonnes, according to Metals Consulting International (MCI) data monitored by Kallanish.
The strongest July growth came from flat products, where imports surged 50% on-year to 140,624t, accounting for more than 70% of total steel imports during the month. Metallic coated sheet imports jumped 87% to 48,731t, an increase of almost 22,700t, while organic coated sheet rose 55% to 29,007t, adding more than 10,300t. Imports of non-alloy hot-rolled sheets and plates increased 81% to 21,246t, while cold-rolled sheet rose 79% to 13,381t.
Despite the strong July performance, January-July flat products imports were virtually unchanged on-year at 728,181t, up just 0.3%.
Long products were the main driver of cumulative import growth. July imports increased 54% on-year to 44,651t, taking January-July volumes 25% higher to 280,341t. The most striking development was with wire rod, with July imports reaching 15,851t versus virtually zero a year earlier. January-July wire rod imports consequently more than tripled, rising 214% to 52,105t. Rebar also recorded an exceptional cumulative increase to 30,342t from just 4,170t, although July itself was negligible at only 35t.
Imports of angles, shapes and sections more than doubled to 10,366t from 4,508t. However, January-July imports of this category remained 21.2% lower at 45,119t.
Railway material imports fell 61% in July to 3,045t, although cumulative imports remained 10.2% higher at 31,954t.
The most significant negative monthly movement was in semis. Imports collapsed 95% on-year to only 1,588t in July from 31,016t. This contrasts sharply with the cumulative trend: January-July semis imports were still 46.8% higher on-year at 68,738t.
Tubes and pipes were comparatively stable, rising only 4% in July to 12,843t, while January-July imports fell 7.6% to 57,861t. Hollow sections were at 5,041t in July, virtually unchanged on-year for the month but remained 12% lower cumulatively.
Overall, the 7.1% increase in January-July steel imports was driven primarily by long products and semis, which rose 56,200t and 21,900t respectively, while total flat imports were essentially unchanged.
| Products | Jul-26 | Jul-25 | Jul 26/25 % | Jan-Jun 2026 |
Jan-Jul 2025 |
Jan-Jul 2026/2025 % |
||
| Flat products | 140,624 | 93,713 | +50 | 728,181 | 726,251 | +0 | ||
|---|---|---|---|---|---|---|---|---|
| Non alloy HR coils | 7,595 | 7,237 | +5 | 46,767 | 53,247 | -12 | ||
| Non alloy HR sheets, plate | 21,246 | 11,715 | +81 | 99,469 | 98,084 | +1 | ||
| Non alloy HR narrow strip | 317 | 145 | +119 | 2,510 | 2,559 | -2 | ||
| Alloy HR flat products | 392 | 236 | +66 | 1,658 | 3,830 | -57 | ||
| CR sheets | 13,381 | 7,480 | +79 | 83,566 | 73,169 | +14 | ||
| Electrical sheets (other than GOES) | 243 | 0 | – | 657 | 227 | +189 | ||
| Metallic coated sheets | 48,731 | 26,054 | +87 | 216,738 | 205,573 | +5 | ||
| Organic coated sheets | 29,007 | 18,656 | +55 | 132,278 | 120,520 | +10 | ||
| Tin mill products | 4,872 | 6,931 | -30 | 29,325 | 38,086 | -23 | ||
| Quarto plates | 11,297 | 11,016 | + | 3 | 92 | ,062 | 105,863 | -13 |
| Wide flats | 0 | 10 | -100 | 1 | 91 | -99 | ||
| Stainless HR coils | 0 | 13 | -100 | 0 | 33 | -100 | ||
| Stainless cut to length | 388 | 419 | – | 7 | 2 | ,881 | 3,326 | -13 |
| Stainless HR narrow strip | 23 | 35 | -34 | 113 | 48 | +137 | ||
| Stainless CR | 2,545 | 3,149 | -19 | 15,271 | 15,780 | -3 | ||
| Stainless CR narrow strip | 73 | 167 | -57 | 1,015 | 1,268 | -20 | ||
| Stainless quarto plate | 98 | 82 | +19 | 741 | 906 | -18 | ||
| Flat of alloy steel >600 mm, of high speed steel | 0 | 0 | -100 | 0 | 0 | -79 | ||
| Grain-oriented electrical sheet | 415 | 366 | +13 | 3,131 | 3,640 | -14 | ||
| Long products | 44,651 | 28,993 | +54 | 280,341 | 224,184 | +25 | ||
| Non alloy merchant bars, light sections | 5,797 | 6,496 | -11 | 62,989 | 51,279 | +23 | ||
| Alloy merchant bars, light sections | 1,792 | 917 | +95 | 6,561 | 8,926 | -26 | ||
| Other bars/rods; tool steel | 10 | 15 | -37 | 124 | 190 | -35 | ||
| Rebars | 35 | 8 | +339 | 30,342 | 4,170 | +628 | ||
| Stainless bars, light Shapes | 1,323 | 1,140 | + | 16 | 7 | ,609 | 7,257 | +5 |
| Stainless wire rod | 0 | 0 | – | 72 | 199 | -64 | ||
| Stainless steel wire | 103 | 91 | +13 | 496 | 608 | -18 | ||
| Wire rod | 15,851 | 1 | +1,585,040 | 52,105 | 16,608 | +214 | ||
| Angles shapes, sections of iron, non alloy steel | 10,366 | 4,508 | +130 | 45,119 | 57,237 | -21 | ||
| Stainless angles, shapes, sections | 0 | 0 | – | 1 | 1 | -44 | ||
| Bars, rods | 0 | 15 | -100 | 899 | 300 | +200 | ||
| Sheet piling | 0 | 95 | -100 | 561 | 331 | +70 | ||
| Non alloy cold finished bars | 241 | 228 | +5 | 1,926 | 2,741 | -30 | ||
| Alloy cold finished bars | 5 | 73 | -94 | 124 | 188 | -34 | ||
| Non alloy cold finished profiles | 144 | 549 | -74 | 2,360 | 3,013 | -22 | ||
| Non alloy forged bars | 3 | 15 | -84 | 365 | 315 | +16 | ||
| Alloy forged bars | 145 | 131 | +10 | 536 | 911 | -41 | ||
| Non alloy wire | 612 | 624 | – | 2 | 3 | ,362 | 4,432 | -24 |
| Railway material | 3,045 | 7,884 | -61 | 31,954 | 28,990 | +10 | ||
| Special products | 15 | 768 | -98 | 151 | 1,450 | -90 | ||
| Alloy wire | 524 | 504 | +4 | 2,869 | 3,093 | -7 | ||
| Fasteners | 4,642 | 4,928 | -6 | 29,815 | 31,945 | -7 | ||
| Tubes & pipes products | 12,843 | 12,360 | +4 | 57,861 | 62,621 | -8 | ||
| Gas pipes | 1,759 | 1,229 | +43 | 4,192 | 5,731 | -27 | ||
| Hollow sections | 5,041 | 5,018 | 0 | 22,414 | 25,481 | -12 | ||
| Seamless stainless tubes, pipes | 54 | 64 | -16 | 221 | 213 | +4 | ||
| Bearing tubes, pipes | 2,180 | 2,599 | -16 | 15,772 | 14,134 | +12 | ||
| Other seamless tubes | 0 | 0 | – | 6 | 1 | +688 | ||
| Other welded pipes | 2,150 | 2,104 | +2 | 8,994 | 10,035 | -10 | ||
| Large welded tubes | 45 | 70 | -35 | 385 | 402 | -4 | ||
| Large welded tubes | 792 | 688 | +15 | 2,220 | 2,742 | -19 | ||
| Tubes, pipes, hollow profiles, of cast iron | 438 | 173 | +153 | 1,139 | 562 | +103 | ||
| Flanges (stainless steel) | 59 | 35 | +67 | 382 | 345 | +10 | ||
| Flanges (other than stainless steel) | 325 | 379 | -14 | 2,137 | 2,975 | -28 | ||
| Semis products | 1,588 | 31,016 | -95 | 68,738 | 46,829 | +47 | ||
| Total | 199,706 | 166,081 | +20 | 1,135,121 | 1,059,885 | +7 |
Source: MCI
Ferriera Valsider declares force majeure after ‘unforeseeable breakdown’
Metinvest’s Italian hot-rolled coil and heavy plate producer Ferriera Valsider has reportedly declared force majeure after an unexpected breakdown caused the complete shutdown of its production lines, according to a customer notification seen by Kallanish.
The company says the incident occurred in recent days and has impacted its ability to fulfil existing supply contracts.
“In the past days, our production facility was affected by an extraordinary, sudden, and unforeseeable breakdown. This event, entirely beyond our reasonable control and not due to our fault or negligence, resulted in the immediate and complete shutdown of our production lines,” the notification says.
The producer says the incident falls under the force majeure provisions contained in Article 8 of its general terms and conditions of sale and has therefore suspended contractual performance terms while the disruption continues.
“At this time, we are unable to determine the duration of the force majeure event, which is expected to be significant,” the company says.
Ferriera Valsider adds that it has “already taken all necessary and appropriate actions to manage the emergency” and plans to provide customers with an update on the situation by the end of August. Sales representatives will meanwhile contact customers individually to discuss existing orders.
The notification provides no details on the nature of the breakdown, or the equipment affected. However, Kallanish understands the suspension follows a major incident at the rolling mill, although this remains unconfirmed at the time of publication.
Metinvest has separately confirmed to Kallanish that production has been suspended and technical teams are working to establish the necessary repair programme.
“Our technical teams are working to define and implement the shortest possible action plan for the necessary repairs, with the objective of restoring production as soon as possible,” it says.
“At this stage, the assessment is still ongoing and we are therefore not in a position to provide a reliable timeframe for the resumption of operations. We will keep our stakeholders informed as the situation develops,” it adds.
Ferriera Valsider, located in Vallese di Oppeano near Verona, is part of Ukrainian steelmaker Metinvest’s Italian operations. The company is a large importer of slab from Asia, including China, Vietnam and Indonesia, according to market participants.
That the disruption comes shortly after Metinvest halted operations at its Zaporizhstal steelworks in Ukraine following a Russian ballistic missile strike on the company’s Zaporizhzhia industrial site overnight on 10-11 August. The attack, which killed seven Zaporizhstal employees and injured 21, damaged energy infrastructure and equipment serving coke and blast furnace operations.