


Buyers have mixed outlook for EU HRC prices as demand weak
Some European steelmakers introduced offer increases of Eur5/mt to Eur20/mt in the week started Oct. 16 to prevent further price declines and due to high production costs. The move saw a mixed response from buyers. Some said that demand would remain low, and a price rise would be impossible without additional production cuts. Some others said restocking, the need to cover costs and a lack of competitive imports would drive prices higher.
Demand was a concern due to weak steel consumption from end-users and distributors avoiding restocking because of sufficient stocks.
“Demand remains the biggest issue, prices have been declining despite big production cuts,” a trader said. “Every steelmaker did something to reduce production. And some mills discussing further stoppages. But in the current economic situation demand is unlikely to improve soon.”
Germany’s ArcelorMittal temporarily idled blast furnaces No. 2 and No. 3 at its Bremen site Oct. 1. ArcelorMittal has also shut blast furnace A at its steel plant in Ghent, Belgium, and was planning to close a furnace at its Fos-sur-Mer site in France. Blast furnaces at the Salzgitter plant in Germany and Tata Steel in the Netherlands have also remained idled for maintenance.
“I do not see any possibility to move prices up, as stocks [of distributors] are still high and end-user demand low,” a German service center said. “Mills offer late November-December rolling coil, so they do not have full order books.”
Market participants said while distributor stocks were high, buyers would need to restock for the first quarter.
“It seems that stocks are not as high as buyers claim,” a distributor said. “They need to buy, and they will return to the market soon looking for some volumes. It is clear that coil prices are already at the bottom. The mills stopped giving discounts, so the lowest prices are gone.”
In the first half of October, European mills were offering discounts to fill production lines for the fourth quarter. But in the middle of the month steelmakers shunned low prices and pushed offers higher.
Production cuts have been sufficient to support domestic prices, some market sources said.
A lack of competitive import offers and long lead times for overseas material made buyers to turn to domestic suppliers.
“Mills’ order books are not good, but they are also not tragic,” an Italian market source said. “Mills will no longer accept lower prices; they need to cover costs. And they will see buyers booking domestic coil instead of import.”
Platts assessed domestic HRC prices in Northwest Europe down Eur5/mt on the day at Eur610/mt ex-works Ruhr on Oct. 18.
Tradable values were heard in the Eur610-620/mt ex-works Ruhr range.
A limited number of deals not attainable from all mills were settled at Eur600/mt ex-works Ruhr. Offers were reported in the Eur610-640/mt ex-works NWE range.
Platts assessed domestic HRC prices in South Europe up Eur10/mt on the day at Eur600/mt ex-works Italy on Oct. 18.
Offers were heard at Eur620/mt ex-works Italy and tradable values at Eur600/mt ex-works Italy.
Import HRC offers from Vietnam were heard at Eur580/mt CIF Italy.
Author Maria Tanatar
Platts is part of S&P Global Commodity Insights.


EUROMETAL calls for EU-US deal that addresses excess steel capacity, supports decarbonization
- New EU-US agreement on sustainable steel, aluminum to be announced Oct 20
- Seeking agreement that respects fair trade and free competition
- EUROMETAL called for amendments to the CBAM
European steel distributors association Eurometal has called on the European Commission to ensure free competition and a level playing field ahead of an EU-US summit on Oct. 20 when a new bilateral agreement on sustainable steel and aluminum is expected to be announced.
According to industry stakeholders surveyed by S&P Global Commodity Insights, the EU and the US are expected to announce the Global Arrangement on Sustainable Steel and Aluminum, which will seek to re-establish normal and undistorted trans-Atlantic trade in the metals and contribute to decarbonizing the steel and aluminum sectors.
In a letter addressed to EC executive vice-president Valdis Dombrovskis published on Oct. 18, EUROMETAL president Fernando Espada called for an EU-US agreement that addresses “global excess capacity” while supporting the industry’s plans for decarbonization.
“Europe can become a top producer of low CO2 steel products globally and our industry is now actively working towards this end goal,” he said.
“The Commission should support and facilitate these initiatives whilst of course ensuring that fair trade and free competition is respected.”
Espada also called for amendments to the Carbon Border Adjustment Mechanism, which he claimed had introduced an additional layer of uncertainty into the industry and reduced the competitiveness of European steel producers.
Espada said that not all national entities were able to provide the necessary details required for implementation, adding that it was “extremely challenging” to apply it to all products containing steel components.
“We are already witnessing an increase in imports of closer to consumer products in certain market areas,” he said.
“This is detrimental to our customer base, the processors, and we expect the Commission to provide assistance and prioritize the interests of steel users and industries that consume steel.”
Espada added that “serious improvements” in the design of CBAM were required, particularly with respect to exports and downstream steel products.
Author: Euan Sadden


US, EU metals unions call for global steel, aluminum deal that prioritizes workers
The US-based United Steelworkers union and European metals trade union IndustriAll asked US and EU trade representatives Oct. 18 for a Global Arrangement on Sustainable Steel and Aluminum that ensures workers rights in addition to addressing nonmarket excess capacity and carbon intensity.
In an letter addressed to US trade Representative Katherine Tai and European Commission Executive Vice-President Valdis Dombrovskis, comes ahead of an EU-US summit on Oct. 20 when a new bilateral agreement on sustainable steel and aluminum is expected to be announced.
The US and EU, which have set a deadline of Oct. 31 to reach an agreement, have previously said like-minded economies would be invited to participate in the arrangement.
“Trade unions insist that interested partners should only be able to join the GASSA if they respect international workers’ rights; lowering working standards and conditions to try and remain ‘competitive’ is inexcusable,” the unions said in their letter. “Furthermore, unfair state aid must end, and trade unions insist that aid linked to decarbonization efforts must have social conditionalities and cannot exacerbate global excess capacity.”
The US and EU have the potential to be global leaders in decarbonization efforts in the steel and nonferrous sectors, the unions said.
“However, a successful pathway for the GASSA will require strong and reactive trade defense measures,” they states. “It should encourage global producers to meet or exceed our shared values for a cleaner environment to help fight climate change, as well as respect internationally recognized and democratic labor rights.”
The groups noted a September report by the Organization for Economic Cooperation and Development Steel Committee that found global steel production is projected to reach 2.5 billion mt in 2023, with an increase of 56 million mt this year alone, marking the largest annual expansion in a decade.
“The time of cheap steel and nonferrous metals, produced in unfair market conditions, flooding open markets, must end,” the unions said.
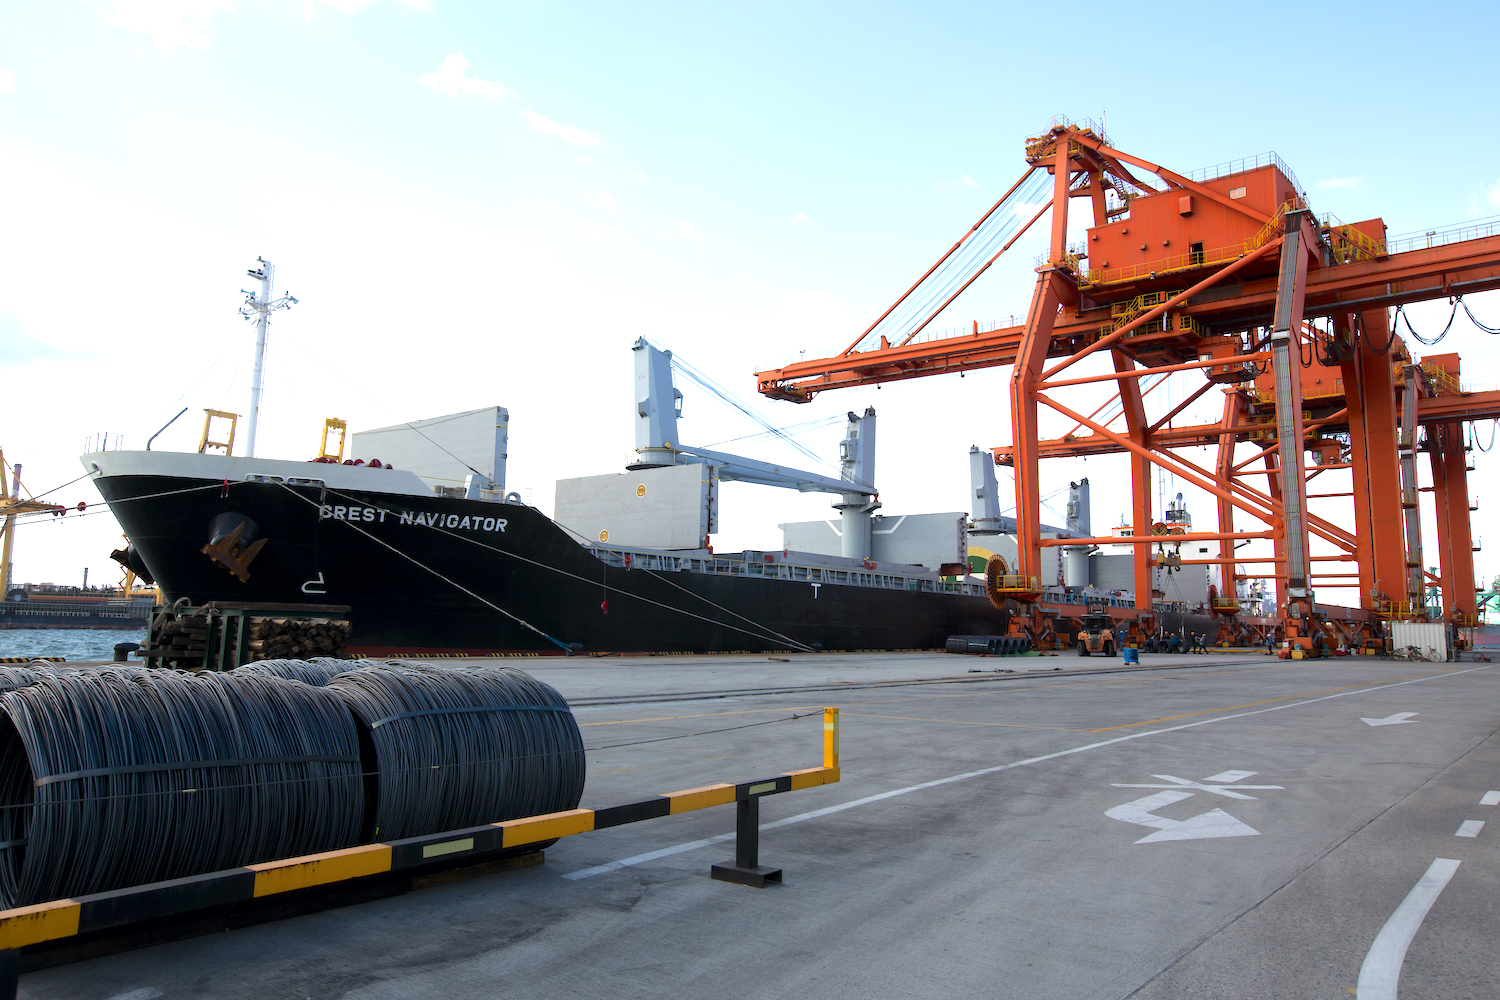
Worldsteel slashes demand forecast amid inflation, geopolitical conflict
Worldsteel has revised down its 2023 global steel demand forecast to 1.8% on-year growth, compared to the 2.3% growth projected in April. High interest rates continue to stifle investment and consumption, while manufacturing continues to slow despite supply chain issues easing. Uncertainty stems from China’s structural transition phase and rising geopolitical conflicts.
Steel demand is seen reaching 1.81 billion tonnes in 2023. In 2024, it is projected to rise a further 1.9% to 1.85 billion t. “Considering the delayed effect of the tightening monetary policy, we expect steel demand recovery in 2024 to be slow in the advanced economies,” worldsteel economics committee chairman Máximo Vedoya says in a note seen by Kallanish. “The performance of emerging economies continues to diverge, with emerging Asia maintaining resilience.”
China’s property market should stabilise in the latter part of the year and China’s steel demand will record slight positive growth thanks to government measures. “The 2024 outlook for China remains uncertain depending on the policy directions to tackle the current economic difficulties,” Vedoya adds.
Besides Chinese uncertainty, increasing regional conflicts contributing to rising oil prices and further geo-economic fragmentation are downside risks.
Despite construction activity faltering, “infrastructure investment is showing positive momentum in many regions, even in the advanced economies, reflecting the effect of decarbonisation efforts”, Vedoya says.
Chinese steel demand in 2023 should record 2% growth, supported by infrastructure investments and stabilisation in the property sector. For 2024, worldsteel forecasts flat on-year steel demand, if government stimulus provides support. However, the real estate market and exports will continue to exert negative pressure on steel demand, which could contract without stimulus.
In the EU, monetary policy is expected to remain tight, meaning a rebound in real demand is not foreseen for 2024. However, as destocking cycles end, a technical rebound will enable positive growth in demand next year. EU plus UK demand is seen dropping 5.1% this year, compared to the April forecast of a 0.4% decline. It should rebound 5.8% next year.
The region’s growth engine, Germany, is in particular trouble, with both a manufacturing recession and a housing crisis. Demand is seen plummeting 10% this year and rebounding 10.6% in 2024.
Despite the resilience of the US economy, residential construction is expected to contract in 2023 and 2024. The 2022 Infrastructure Law and Inflation Reduction Act (IRA) is supporting infrastructure growth, while the automotive sector is expected to continue its post-pandemic recovery. The lagged effect of tight monetary policy points to downside risk for 2024. Demand is seen falling 1.1% this year and rebounding 1.6% next year.
Adam Smith Poland

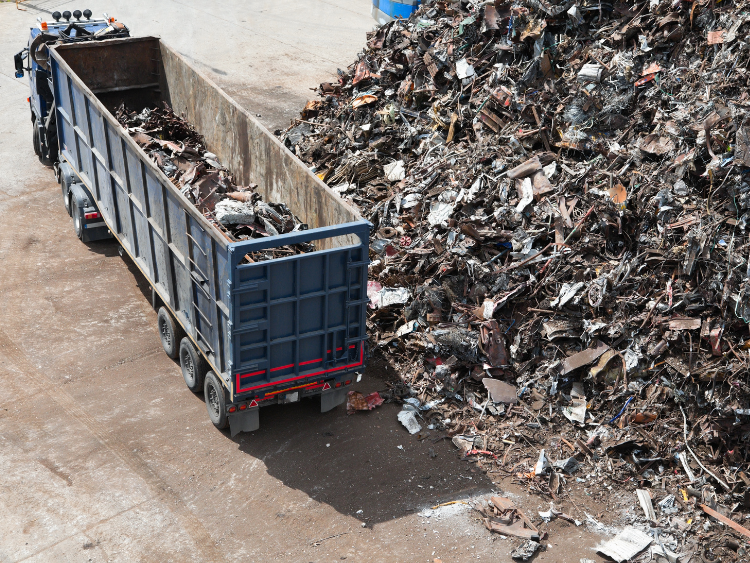
Austrian institutions investigate scrap analysis
Austrian steelmakers and research bodies have launched a research project on the improvement of scrap selection by means of artificial intelligence and spectral analysis.
The project is titled InSpecScrap, and involves voestalpine, rebar maker Marienhütte, along with research institutes TU (Technical University) Graz, Joanneum Research, Know Center and competence centre K1-MET.
It was launched by the Austrian Society for Metallurgy and Materials (ASMET) and the state government of Styria, home of voestalpine’s Donawitz site, as one of ten projects in a competition named “Green Tech X”. InSpecScrap is therefore profiting from and complementing the trend for “green” steel.
At the launch event of the project, participants explained that they aim to detect all characteristics of the composition and quality of scrap already at the scrap yard, news agency APA reports. Researchers have started testing a combination of spectral cameras and artificial intelligence to achieve better accuracy when analysing scrap ingredients and qualities, Kallanish notes.
Marienhütte managing director Markus Ritter is quoted as saying he prefers sourcing scrap from domestic sources, rather than long and border-crossing transportation. The mill needs some 470,000 tonnes/year of scrap for its rebar production, which is shipped nearly exclusively by train.
Christian Koehl Germany

Port of Liverpool expands steel terminal amid demand
Peel Ports Group says it will extend its steel and metals terminal in response to strong growth in customer demand at the Port of Liverpool.
The UK’s second-largest port operator began construction of the 20,000-square foot extended warehouse at its North 3 Canada Dock in 2023. Its investment comes as the Port of Liverpool enjoyed one of its busiest months for steel volumes in September, with more than 75,000 tonnes handled across the port and Birkenhead Docks.
This was the port’s busiest month for steel in more than two years, when 93,000t were handled at the site in July 2021.
An initial 8,000 square feet of the newly created warehouse space is already in use. A second phase of construction work to build an extra 12,000 square feet of the terminal is ongoing and scheduled to be completed in December.
“We’re really pleased to have seen such an increase in demand for steel handling at our port in recent months,” Peel Ports Group Mersey Ports Director Phil Hall says in a note seen by Kallanish. “This positive news led to us choosing to increase the size of our facility, which offers customers the chance to expand their capacity, as well as improving our handling facilities at the port.”
Adam Smith Poland
Duferco inaugurates new mill
Italian sections producer Duferco Travi e Profilati has inaugurated the new Smart Beam Manufacturing (SMB) rolling mill at its San Zeno Naviglio site near Brescia, boosting capacity and sustainability, Kallanish learns from the company.
The new SMB mill supplied by SMS meets the company’s objective of enlarging its product range, improving quality and boosting capacity. It says it plans to become the “best cost producer” for sections at an international level. The new mill has a capacity of 700,000 tonnes/year at an overall investment of €250 million ($264m).
The San Zeno Naviglio site will use mostly clean energy. Duferco has signed a long-term power purchase agreement with a wind energy producer which, coupled with the photovoltaic capacity installed at the facility, will allow the mill to fully function with renewable energy. This will reduce carbon footprint and cut 28,000 tonnes/year of CO2. The site is digitalised and will use artificial intelligence to optimise the production process and energy consumption in the pursuit of a “zero waste” policy.
“The mill uses the most modern digital technologies and data analysis to save energy, and water, and guarantee safety as well as product quality. Innovation and sustainability in the steel industry are one and the same. AI has brought about an epochal paradigm shift, even if the human factor, focus, empathy, competence, determination are indispensable ingredients that the machine cannot replace,” Duferco president Antonio Gozzi says in a note.
Duferco Travi e Profilati has four facilities in San Zeno Naviglio, Giammoro, Pallanzeno and San Giovanni Valdarno, with a combined yearly output of 1 million tonnes of long products.
Natalia Capra France

European steel HRC producers seek higher prices on mounting costs
Major steelmakers have gradually started pushing for higher prices, seeking a €15-20 ($16-21) per tonne increase, claiming that the increases were necessary to cover input costs.
“Current prices [for HRC] are unsustainable,” a steelmaker source told Fastmarkets.
In general, HRC offers were reported to be around €645-650 ($680-685) per tonne ex-works from three integrated steelmakers in Northern Europe, compared with €630 per tonne heard last week.
Lead times from local mills varied between four and six weeks, sources said.
Buyers were cautious about the attempt to raise prices, claiming that mills’ order books were too weak and demand too slow to support even a small rise.
“Spot market activity in Northern and Southern Europe is still not significant,” a second steelmaker in Northern Europe said.
“Mills have low order books, and on a firm bid they still would negotiate a discount,” a steel service center in Northern Europe said. “It looks like [the steelmakers] want to stop the downtrend with this increase and signal to the market that the bottom has been reached.”
Buyers’ estimates of tradeable values were heard at €600-620 per tonne ex-works on Tuesday. Mills, however, claimed that the lower end of that range was “below costs” for them.
Even though inventory levels were trending lower at steel service centers and distributors, they continued to postpone restocking, market sources said.
“Buyers will come back for volumes when they have the understanding that, if they don’t book today, tomorrow [HRC] will be more expensive,” a third mill source said.
“More and more customers are out of stock. But they are still buying carefully,” a trading source said.
Fastmarkets calculated its daily steel hot-rolled coil index domestic, exw Northern Europe at €618.57 per tonne on October 17, up by €3.82 per tonne from €614.75 per tonne on October 16.
The index was down by €1.43 per tonne week on week, and down by €16.31 per tonne month on month.
In Southern Europe, meanwhile, Fastmarkets calculated its corresponding daily steel hot-rolled coil index domestic, exw Italy at €592.71 per tonne on October 17, down by €2.29 per tonne from €595.00 per tonne on October 16.
The index was also down by €7.29 per tonne week on week and by €33.29 per tonne month on month.
In Italy, tradable values for HRC were reported by buyers at €580-590 per tonne ex-works, while producers tried to keep offers at a minimum of €600 per tonne-ex-works.
But after other European steelmakers attempted to increase their prices, market sources suggested that Italian mills would follow suit and try to push offers higher as well.
Trading in the spot market remained very quiet, however, with steel service centers and distributors “aggressively destocking,” according to market sources.
For imports, two sources reported HRC offers at $600 per tonne CFR from Japan for end-December shipment, noting that some Japanese producers were starting to become aggressive with their offers.
Another trader said that Japanese producers were offering HRC to Europe at prices no lower than $620 per tonne CFR.
In general, most HRC offers from Asia were in the range of €580-600 per tonne CFR for December shipment.
Published by: Julia Bolotova


HRC market in Europe remains quiet amid lack of trading; mills reportedly mull rises amid rising costs
Distributors and steel service centers (SSCs) in Northern Europe have adopted a “hand-to-mouth” procurement plan and continue to avoid restocking in a volatile market, sources added.
“In fact, destocking is still taking place; in the downstream market, SCCs are competing for volumes. We expect no restocking in October and November,” a source at a SSC in Germany said.
Despite pressure on prices and slow end-user demand, European producers are said to be resisting further price cuts due to high costs.
“The prices for iron ore and coking coal are rising worldwide, while [the HRC market] remains under pressure, and mills have started losing money,” a source in Northern Europe said.
Some integrated producers in Northern Europe reported offers for November-December delivery coil at €630-640 ($662-673) per tonne ex-works, saying this was the “bare minimum due to costs.”
At the same time, buyers’ price ideas were no higher than €600-620 per tonne ex-works.
Lead times were said to be quite short, with one mill able to HRC “within four to six weeks.”
Several sources told Fastmarkets that some European mills were mulling price increases, but pointed out that it would be “a completely cost-driven increase with no support from demand.”
“We heard that [a market leader] plans to announce a price increase for HRC this week [from October 16],” a trading source said.
That, however, was not widely confirmed by other sources by the time of publication.
Fastmarkets calculated its daily steel hot-rolled coil index domestic, exw Northern Europe at €614.75 per tonne on October 16, down by just €2.33 per tonne from the previous calculation of €617.08 per tonne on October 13.
The index was also down by €5.25 per tonne week on week, and down by €20.13 per tonne month on month.
In Southern Europe, meanwhile, Fastmarkets calculated its corresponding daily steel hot-rolled coil index domestic, exw Italy at €595.00 per tonne on October 16, up by just €1.98 per tonne from €593.02 per tonne on October 13.
The index was also down by €10 per tonne week on week and by €31 per tonne month on month.
Italian mills have reportedly been rejecting bids from buyers coming in at €600 per tonne delivered (€585 per tonne ex-works), several sources told Fastmarkets.
November-delivery coil was still available from some local suppliers, sources said.
Producers were trying to maintain offers at €600 per tonne ex-works and above due to costs, while buyers’ price ideas were largely below €600 per tonne ex-works.
Distributors and SSCs in the country were also largely focused on destocking, and therefore were not really interested in new HRC bookings.
“[Hot-rolled] sheets are being sold at around €680 per tonne CPT in the secondary market, and sometimes even below that. There is oversupply and some companies [SSCs, distributors] have lead times of just a couple of days,” a trading source in Italy said.
Imports from Asia for end-January/February delivery were on offer to Italy at around €580-600 per tonne CFR — a price level deemed totally unworkable by Italian buyers.
Published by: Julia Bolotova

Hybrit hydrogen storage facility reduces costs 40%: Vattenfall
Following commercial testing on the electricity market, Hybrit’s hydrogen storage facility has shown the variable cost of fossil-free hydrogen production can be reduced by 25-40%, says Hybrit joint venture partner Vattenfall.
The facility was used specifically on the electricity market for about a month. The mission was to produce hydrogen using fossil-free electricity at a variable electricity price with the lowest possible cost, for example during certain parts of the day or for longer periods when weather-dependent electricity generation was in good supply. The hydrogen was delivered in a steady flow to SSAB.
“Despite the fact that Vattenfall optimised trading and operations against real electricity prices during a period with low price variations, the results were very good. The tests were conducted in a close collaboration between Hybrit Development and Vattenfall. By applying it in actual circumstances, we were able to follow in real time how much money was saved by using what was stored,” Hybrit senior project manager Marie Anheden says in a note seen by Kallanish.
The design itself has proven to be well suited for rapid emptying and filling, interspersed by periods of less activity, Vattenfall observes. The latest effort to lower the price of hydrogen production used a simulation tool, a new optimisation model and the 100 cubic meter pilot hydrogen storage in Luleå.
“These are exciting and important results because hydrogen from fossil-free electricity is one of the keys to transitioning the industry. Large-scale hydrogen storage makes it possible to adapt electricity consumption in a system of varying availability and prices and at the same time can supply the industry with hydrogen more stably and cost effectively. Used on a large scale, hydrogen storage can have a dampening effect on electricity price variations, which would favour investments in new electricity generation from all forms of fossil-free power,” says Vattenfall industry decarbonisation head Mikael Nordlander.
“LKAB will change the entire production of iron ore products to fossil-free iron sponge produced with hydrogen gas, so these are very important results for us,” says LKAB senior vice-president for energy and climate Stefan Savonen. “We will need to produce over one million tonnes of hydrogen and consume over 70 TWh of fossil-free electricity per year when we have restructured the entire operation by 2050. Reducing costs is therefore absolutely necessary.”
Adam Smith Poland