

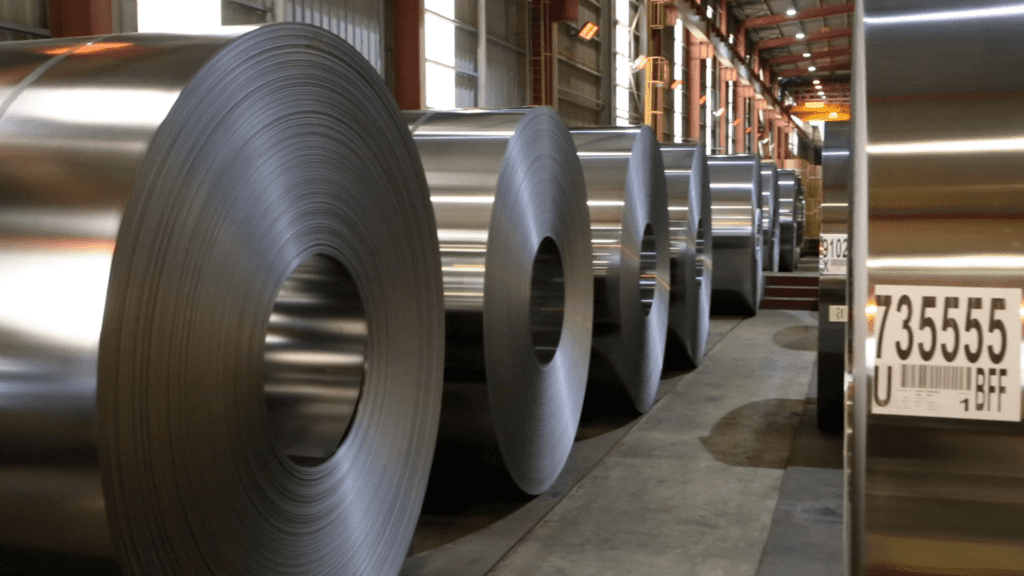
Northwest European HRC offers limited, buyers show higher interest in imports
The current exchange rate between the euro and the US dollar has supported buyer interest in imported HRC, sources said.
A transaction for HRC originating from Taiwan has been heard at Eur605-610/mt CIF Antwerp, and offers and tradable values for Asian material have been reported at Eur600-610/mt CIF Antwerp.
Platts assessed prices for imported HRC in Northwest Europe at Eur605/mt CIF Antwerp July 19, down Eur5.
“Import will remain competitive even with longer lead times, the first attempt of the European mills to increase offers would attract more overseas coil,” a trader said.
In the meantime, only a couple of NWE steelmakers have been active in the market, as others have reported full order books and some were planning summer maintenance, including the relining of blast furnaces.
The range of offers in Germany has also been wide—a re-roller has been offering HRC at Eur620/mt delivered Germany, some NWE integrated mills have been aiming for prices of Eur680-700/mt, delivered Germany, and offers from Central Europe have been reported at the equivalent of Eur650-660/mt, delivered Germany.
And market participants estimated tradable values at Eur650-680/mt EXW Ruhr.
Platts assessed prices for HRC produced in Northwest Europe at Eur660/mt ex-works Ruhr July 19, stable on the day.
“German mills are not really active, and they do not give official offers,” a German service center said. “So, prices should be stable, at least that is the sentiment, but in reality, they keep slowly sliding. And there are some steelmakers ready to give discounts.”
Platts assessed prices for HRC produced in Southern Europe at Eur655/mt EXW Italy July 19, unchanged.
Demand has been gradually decreasing as the European market enters a traditionally slow period in the second half of summer. In addition, distributors have been avoiding the booking of bigger lots due to an uncertain outlook for September. The blurry consumption expectations were caused by low demand from the majority of end-user sectors, with the exception of the automotive industry.
Author Maria Tanatar

US to continue AD, CVD duty orders on steel wire rod from 10 countries
The US International Trade Commission issued an affirmative determination July 19 to continue the existing antidumping and countervailing duty orders on imports of wire rod from 10 countries.
The decision follows a five-year sunset review of the existing antidumping orders covering these imports from Belarus, Italy, Russia, South Africa, South Korea, Spain, Turkey, Ukraine, the UAE and the UK and the countervailing duty order on wire rod imports from Italy and Turkey.
The Commerce Department in March determined that removing the existing duties would likely lead to the continuation or recurrence of dumping and subsidies.
Commerce listed the following likely dumping margins that would occur or recur if the duties were to be revoked: up to 280.02% for Belarus, 18.89% for Italy, 41.1% for South Korea, 756.93% for Russia, 142.26% for South Africa, 32.64% for Spain, 4.44% for Turkey, 44.03% for Ukraine, 84.1% for the UAE, and 147.63% for the UK.
In the countervailing duty review, Commerce said revoking the existing order would likely continuation or recurrence of countervailable subsidies at up to 44.18% for Italy and up to 6.09% for Turkey.
US duties on these imports were first put in place in 2018.
Author Justine Coyne

Italian first-half crude steel output declines
Italian crude steel output declined slightly, by 0.7% year-on-year in June to 1.9 million tonnes, according to data issued by local steelmakers association Federacciai. In the first six months of the year, production fell by 6.6% on-year to 11.4mt.
Flat steel production decreased by 8.7% to 861,000t last month and by 8.4% to 4.9mt in January-June. Longs output fell by 2.3% to 1mt and by 5.7% to 6.4mt respectively, Kallanish notes.
The Italian market, particularly long mills, is preparing for longer-than-typical maintenance stoppages this August. Some longs facilities are already idled until the end of August in an effort to address the issue of overcapacity. Both flats and longs markets are suffering from a steep decline in end-use consumption.
Italian crude steel output declined by 11.5% y-o-y in 2022 to 21.6mt. Flats production tumbled 13.8% to 9.5mt, while longs output fell by 12% to 12mt.
Natalia Capra France


ArcelorMittal begins XCarb heavy plate production in Spain
ArcelorMittal tells Kallanish it has started producing low-carbon-emission steel plate of up to 18 tonnes at its Spanish heavy plate mill in Asturias.
The steelmaker says it is the first producer in Europe with the ability to manufacture such products in these dimensions. 18-tonne heavy plate is used in major infrastructure projects, such as in the welded section and box girders for road and rail bridges.
The XCarb recycled and renewably produced heavy plates are manufactured using slab supplied by ArcelorMittal Industeel in France. This is an electric arc furnace-based steelmaking facility using almost 100% of steel scrap and 100% of electricity coming from renewable sources. This combination results in a nearly 60% reduction of CO2 emissions, compared with plate made by conventional blast-furnace steelmaking.
“We are immensely proud to now be able to offer heavy plates to our customers, with a reduced CO2 footprint. Our teams have worked very hard to bring this product to market, which we know meets a growing customer need for low-carbon-emissions steel in complex civil engineering projects,” comments Denis Parein, ArcelorMittal Europe heavy plate unit commercial director.
ArcelorMittal’s XCarb heavy plate will receive the Environmental Product Declaration, according to the EN 15804 European standard, by the end of this year, the executive confirms.
XCarb is a global programme by ArcelorMittal, launched in 2021, which aims to bring together all the group’s efforts and investments with the mission of reducing greenhouse gas emissions in the steelmaking chain. ArcelorMittal has a target of reducing CO2 emissions within Europe by 35% since 2030 and reaching net-zero by 2050.
Todor Kirkov Bulgaria

French rebar sales stagnate
The French rebar market remains subdued in July with continued low orders and uncertainty. Distributors say some customers have a better visibility thanks to orders coming from the infrastructure sector, but the weak performance of private residential construction is weighing on rebar sales volumes, Kallanish notes.
In June and July so far, distributors have continued to work with very low order books. Deals are being agreed for single days only, while visibility is zero. Customers are keeping their stocks low.
Some sales improvement is hoped for in the coming days as customers will need to buy some volumes for September, but no forecasts are possible considering the current low consumption and activity downstream remaining quiet. This is being exacerbated by the holiday period, which in France starts with the 14 July bank holiday.
Rebar prices remain stable on-month, after sentiment in the construction industry deteriorated. Apart from some orders for infrastructure projects, the majority of weekly rebar contracts are being carried out only back-to-back. Distributors say sales volumes can be as low as 25-50 tonnes.
Incursion of lower-priced Italian and Spanish material is being reported in the south, while German material is competing with domestic rebar in the north. Domestic rebar prices are hovering at €590-640/tonne ($661-717) delivered including size extras, depending on tonnage, sources suggest.
Natalia Capra France

Decarbonisation spurs new entrants, supply chain shifts: ING
Steel decarbonisation might be driven by “Tesla-style” new entrants rather than established steel majors. The supply chain could meanwhile evolve towards global production hubs of green iron and local sites that specialise in turning this into different qualities of steel. So says ING Bank.
Many steel majors have already embarked on decarbonisation. They have billions of dollars’ worth of coal-based steel assets on their balance sheets. “On a positive note, that provides them the capital to develop CCS [carbon capture and storage] and hydrogen. On a more negative note, it could limit real change as current assets may become stranded once hydrogen technology takes over,” the bank says in a report sent to Kallanish.
Disruptive change may however come from new entrants such as Vulcan Green Steel, Blastr, GravitHy and H2 Green Steel, the report continues.
Ukraine could be a country driving the change in the sector. “As the ongoing war persists, the financial focus of politicians and financiers is on short-term funding issues. But slowly, they’re beginning to look at long-term reconstruction efforts too,” ING Bank comments.
The World Bank estimates Ukraine’s reconstruction will cost more than $400 billion. Ukraine is seeking up to $40 billion to fund the first part of a Green Marshall Plan to rebuild its economy. The main priority will be on the iron and steel industry, with a vision to build a green steel industry of 50 million tonnes/year, the bank adds.
Ironmaking could in future be relocated from regions with high energy and hydrogen costs towards those with lower costs. Australia, the Middle East and the US, for example, are likely to have a competitive advantage in hydrogen production. Ironmaking may be concentrated in these regions and then shipped to higher-cost areas such as Europe as hot-briquetted iron. Alternatively, it may be relocated within Europe to regions with low renewable electricity prices, such as Sweden or Norway.
Developed countries might prefer to invest in the hydrogen route more quickly, while developing and coal-heavy countries like India and China may choose to rely more heavily on CCS technology. “The climate benefits from both and the discussion should focus on the speed of change rather than a battle between technology. Finally, such debates shouldn’t distract us from tempering the demand for steel, as the climate benefits most from steel that isn’t produced,” the bank says.
CCS costs in steel production range from €60-100/tonne ($67-112) of carbon. This is much cheaper than technology such as electric vehicles, home renovations and hydrogen-based solutions, which cost hundreds of euros per tonne of carbon that is reduced.
“Even so, CCS has not been applied a lot in steelmaking yet as it is not mandatory, and carbon is often not priced sufficiently across the globe. The European carbon price of around €85/t CO2 starts to bite – but steel producers still enjoy a number of free allowances, and prices have seen a recent increase, while investments in CCS take years to materialise,” ING concludes.
Adam Smith Poland
Demand improves for Italian HDG
Sellers are reporting some demand improvement for Italian hot-dipped galvanised coil but quiet activity for cold rolled coil which is competing with lower import offers.
While domestic producers are managing to sell at relatively good prices in Eastern Europe and France, other countries such as Germany and Spain are bidding at unsustainably low values for HDG, sources tell Kallanish.
Domestic transaction prices are flat compared to the beginning of July as the increases implemented for coil this month did not stick. Sellers are nevertheless not complaining about sales this month and the entire value chain seems to be enjoying the current price stability after the steep fluctuations of the past. The market will start going quiet from next week, in preparation for the August stoppages.
Transactions indicate HDG levels are at €760-780/tonne ($852-874) base ex-works depending on volumes and CRC at some €10-20/t less.
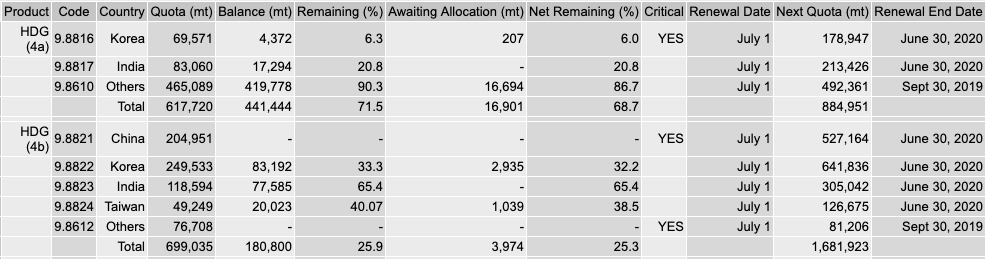
Some mild restocking is expected for both products in September for year-end delivery. Today’s main issue for HDG and CRC producers is that certain EU hot rolled coil safeguard quotas are being quickly exhausted, meaning importers will have to wait until the next quota term before they can clear material through customs.
Demand for HDG is stable and the domestic market seen as “positive”, but low volumes are reported for CRC. Buyers prefer imported CRC at €680-690/t cfr Italy and domestic volumes are thin.
HRC prices, meanwhile, also remain stable, with demand flimsy, at €650-660/t base ex-works, sources suggest.
Natalia Capra France

Trading slows, prices flatten in European heavy steel plate market ahead of summer holidays
Italy
Apparent demand for steel plate in Italy was slow over the past week, with stockholders seen to be largely holding back from trading.
“Trading has slowed down significantly since last week [the week to July 14]. We’ve been getting very few inquiries for small volumes [of steel plate] recently, it is a seasonally quiet period,” a trading source said.
Tradeable values for larger tonnages for September delivery were reported at €750-760 ($843-854) per tonne EXW during the week, while €770-780 per tonne EXW was achievable for smaller lots, which is largely unchanged from the previous week.
Offer prices from local re-rollers were still heard at around €800 per tonne EXW, but even sellers admitted that those levels were not achievable, given the slow market activity.
As a result, Fastmarkets’ weekly price assessment for steel domestic plate, 8-40mm, exw Southern Europe, was €750-780 per tonne on Wednesday, unchanged since July 5.
Sources expected those levels to be sustained until the end of August.
“During August the steel market in Europe is totally dead, so we expect prices to rollover. Starting in September some pick up [in prices] is likely due to expected restocking,” a mill source said.
Some lower overseas plate offers were reported during the week, mainly due to the strengthening of the euro against the US dollar, sources said.
Notably heavy plate from Indonesia with September shipment was offered to Italy at around €670 per tonne CFR in the assessment week, compared to around €690 per tonne CFR in the week prior.
Northern Europe
Trading activity was also seasonally quiet in Northern Europe, with big buyers also seen to be largely out of the market after restocking earlier this month.
Integrated producers in Northern Europe were mostly concentrating on long-term project business, and were therefore not very active in spot sales.
One mill in Germany reportedly had limited allocation of September-delivery plate at around €830-850 per tonne EXW, but sources said the lower end of the range was only available for the mill’s regular customers.
Another German mill was maintaining its offers for heavy plate for September-October delivery at more than €900 per tonne EXW.
Estimations of tradeable values from buyers were reported at around €850-870 per tonne EXW.
Fastmarkets’ weekly price assessment for steel domestic plate, 8-40mm, exw Northern Europe, was €850-870 per tonne on Wednesday, unchanged since July 12.
A re-roller in Denmark was offering S355-grade plate to Germany at €920 per tonne CPT, sources said.
In Central Europe, sources said a Czech mill was offering limited tonnages of plate around €800 per tonne EXW. An integrated mill from Poland was reportedly not active during the assessment week.
Buyers’ estimations for tradeable values for commodity-grade plates in Central Europe were reported at €800-840 per tonne CPT during the week.
And a producer from Romania was offering S355-grade plate quite aggressively in Central Europe, at around €800 per tonne CPT.
Published by: Julia Bolotova


Carbon Border Adjustment Mechanism (CBAM): Questions and Answers
Why is the EU putting in place a Carbon Border Adjustment Mechanism?
The EU is at the forefront of international efforts to fight climate change. The European Green Deal set out a clear path towards achieving the EU’s ambitious target of a 55% reduction in greenhouse gas emissions compared to 1990 levels by 2030, and to become climate-neutral by 2050. In July 2021, the Commission made its Fit for 55 policy proposals to turn this ambition into reality, further establishing the EU as a global climate leader. Since then, those policies have taken shape through negotiations with co-legislators, the European Parliament and the Council, and many have now been signed into EU law. This includes the EU’s plan for a Carbon Border Adjustment Mechanism (CBAM).
As the EU raises its climate ambition and less stringent environmental and climate policies prevail in some non-EU countries, there is a strong risk of so-called ‘carbon leakage’ – i.e. companies based in the EU could move carbon-intensive production abroad to take advantage of lax standards, or EU products could be replaced by more carbon-intensive imports. Such carbon leakage can shift emissions outside of Europe and therefore seriously undermine EU as well as global climate efforts. The CBAM will assess the emission released in producing goods and equalise the price of carbon between domestic products and imports of a selected number of products. Hence it will ensure that the EU’s climate objectives are not undermined by production relocating to countries with less ambitious policies. The CBAM is therefore a climate measure to prevent the risk of carbon leakage and support the EU’s increased ambition on climate mitigation, while ensuring WTO compatibility. Over a period of eight years, CBAM will also gradually replace the free allowances given under the EU Emission Trading System (ETS). In this way, CBAM will be an important incentive for EU producers to reduce emissions.
The European Parliament and the Council of the European Union, as co-legislators, signed the final CBAM Regulation on 10 May 2023. The provisions underpinning the CBAM, and its operational features will now progressively enter into force and application.
How will the CBAM work?
In accordance with EU’s international policies and commitments, CBAM has been designed to comply with EU’s international obligations including World Trade Organization (WTO) rules.
The CBAM system will mirror the EU ETS and will work as follows:
• CBAM will be applied on the actual declared carbon content embedded in the goods imported in the EU, according to a formula that will reflect the effects of the EU ETS on the production of similar goods in the EU.
• As from the entry into force of the final regime of CBAM in 2026, EU importers will buy CBAM certificates corresponding to the carbon price that would have been paid, had the goods been produced under the EU’s carbon pricing rules.
• Conversely, if a non-EU producer has already paid a carbon price in a third country on the embedded emissions for the production of the imported goods, the corresponding cost can be fully deducted from the CBAM obligation.
• The CBAM will therefore help reduce the risk of carbon leakage while encouraging producers in non-EU countries to green their production processes and countries to introduce carbon pricing measures.
To provide businesses and other countries with legal certainty and stability, the CBAM will be phased in gradually and will initially apply only to a selected number of goods at high risk of carbon leakage: iron/steel, cement, fertilisers, aluminium, hydrogen and electricity generation. In a transitional period, a reporting system will apply as from 1 October 2023 for those goods with the objective of facilitating a smooth roll out and to facilitate dialogue with third countries. Importers will start paying the CBAM financial adjustment in 2026.
How does CBAM interact with the Emissions Trading System (ETS)?
The EU’s Emissions Trading System (ETS) is the world’s first international emissions trading scheme and the EU’s flagship policy to combat climate change. It sets a cap on the amount of greenhouse gas emissions that can be released from power production and large industrial installations. Allowances must be bought on the ETS trading market, though a certain number of free allowances is distributed to industry to prevent carbon leakage. In order to step up the incentive to decarbonise, the CBAM will progressively become an alternative to this. Under the EU’s ETS, the number of free allowances for all sectors declines over time so that the ETS can have maximum impact in fulfilling the EU’s ambitious climate goals. For the CBAM covered sectors, free allowances will be phased out as from 2026, as the CBAM financial adjustment is phased in according to a gradual schedule.
To complement the ETS, the CBAM will be based on a system of certificates to cover the embedded emissions in products being imported into the EU. The CBAM departs from the ETS in some limited areas where it was needed for a border adjustment instrument, as it is not a ‘cap and trade’ system. Nevertheless, the CBAM certificates mirror the ETS price.
Once the full CBAM regime becomes operational in 2026, the system will adjust to reflect the revised EU ETS, in particular when it comes to the reduction of available free allowances in the sectors covered by the CBAM. This means that the CBAM will only begin to apply to the products covered and in direct proportion to the reduction of free allowances allocated under the ETS for those sectors. Put simply, until they are completely phased out in 2034, the CBAM will apply only to the proportion of emissions that does not benefit from free allowances under the EU ETS, thus ensuring that importers are treated in an even-handed way compared to EU producers.
Which sectors will the new mechanism cover and why were they chosen?
The CBAM will initially apply to imports of the following goods:
• Cement
• Iron and Steel
• Aluminium
• Fertilisers
• Hydrogen
• Electricity
These sectors have been selected following specific criteria, in particular their high risk of carbon leakage and high emission intensity which will eventually – once fully phased in –represent more than 50% of the emissions of the industry sectors covered by the ETS.
The CBAM will apply to direct emissions of greenhouse gases emitted during the production process of the products covered, as well as to indirect emissions for a subset of those products (i.e. cement and fertilisers). The CBAM Regulation provides that an analysis will need to be carried out before including indirect emissions in further products in the future. A review of the CBAM’s overall functioning during its transitional period will also be concluded before the entry into force of the definitive system.
At the same time, the product scope will be reviewed by the end of the transitional period to assess the feasibility of including other goods already covered by the EU ETS and susceptible to carbon leakage, such as certain downstream products and those identified as suitable candidates during negotiations (i.e. chemicals and polymers).
The report will include a timetable setting out their inclusion by 2030.
Will the CBAM apply to EEA countries?
The CBAM has EEA relevance and is designed to take full account of the carbon price paid in third countries, whether through market-based instruments like the ETS, or through carbon taxation. Goods originating in countries that fully apply the EU ETS – such as EEA countries – or that have concluded an agreement fully linking their ETS with the EU ETS – such as Switzerland – are entirely excluded from the mechanism.
By ensuring importers pay the same carbon price as domestic producers under the EU ETS, CBAM will ensure equal treatment for products made in the EU and imports from elsewhere and avoid carbon leakage.
How is the CBAM compatible with other ETS systems outside the EU?
The CBAM will ensure that imported products will get “no less favourable treatment” than EU products, thanks in particular to 3 CBAM design features:
– the CBAM takes into consideration “actual values” of embedded emissions, meaning that decarbonising efforts of companies exporting to the EU will lead to a lower CBAM payment,
– the price of the CBAM certificates to be purchased for the importation of the CBAM goods will be the same as for EU producers under the EU emissions trading system (EU ETS), and
– the effective carbon prices paid outside the EU will be deducted from the adjustment to avoid a double price.
This carbon price paid in a third country could for example be due to an established Emissions Trading System. The Commission will develop secondary legislation before the end of the transitional period to design the rules and processes to take in to account the effective carbon price paid abroad. During the transitional period, the reports will need to include the carbon price due in a country of origin for the embedded emissions in the imported goods, taking into account any rebate or other form of compensation available, for information purposes.
Transitional Period
What will happen in the transitional period?
During the transitional period starting on 1 October 2023 and finishing at the end of 2025, importers will have to report at the end of each quarter emissions embedded in their goods subject to CBAM without paying a financial adjustment, giving time for the final system to be put in place.
This transitional period, combined with the gradual phasing-in of CBAM between 2026 and 2034, will allow for a careful, predictable and proportionate transition for EU and non-EU businesses as well as authorities.
What specific information needs to be reported by each CBAM covered sector?
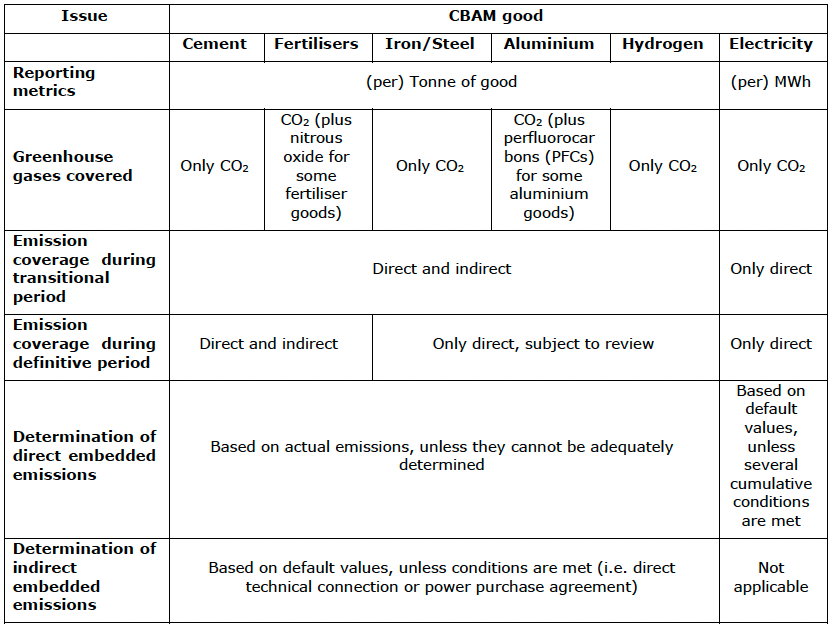
The following table provides an overview of the specific emissions and greenhouse gases covered and how direct and indirect emissions will be determined for each sector under the CBAM scope. Each sector’s particularities have been taken into account when designing the methods for reporting and calculating embedded emissions in these goods while mirroring the EU Emissions Trading System:
CBAM reporting obligation
Who is responsible for the reporting?
Customs authorities will inform customs declarants of their obligation to report information during the transitional period. The customs declarant will either be the importer or the indirect customs representative depending on who lodges the customs declaration.
The person responsible for the reporting obligation can be one of the following:
1. the importer when (i) the importer lodges a customs declaration for release for free circulation of goods in its own name and on its own behalf; and when (ii) is also the declarant holding an 5ertificate5n to lodge a customs and declares the importation of goods;
2. the indirect customs representative, where the customs declaration is lodged by the indirect customs representative appointed in accordance with Article 18 of Regulation (EU) No 952/2013, when the importer is established outside of the Union; or when an indirect customs representative has agreed to the reporting obligations in accordance with Article 32 of Regulation 2023/956.
What are the reporting obligations?
During the transitional period of the CBAM, from 1 October 2023 until 31 December 2025, the importer shall submit a CBAM report on a quarterly basis. This report will include the information on the goods imported during that quarter of year and should not be submitted later than one month after the end of that quarter.
More concretely, the report shall include the information referred in Article 35 of the Regulation:
• the total quantity of each type of goods;
• the actual total embedded emissions;
• the total indirect emissions;
• the carbon price due in a country of origin for the embedded emissions in the imported goods, taking into account any rebate or other form of compensation available.
How is a CBAM report submitted during the transitional period?
A CBAM report is submitted using the CBAM Transitional Registry which will be deployed for the use of Economic Operators in the EU as from the 1st of October 2023 together with a set of webinars and trainings which will facilitate the use of the registry and the submission of data during the transitional period.
Do importers of CBAM goods need to be authorised to import CBAM products during the transitional period?
Importers of CBAM goods will not need to be authorised during the transitional period in order to import these goods into the EU. Customs will inform importers of CBAM goods of their reporting obligations at the moment of import.
Are there verification obligations during the transitional period?
No, verification by an external independent body will only be mandatory from 2026.
Role of the European Commission
What is the role of the European Commission during the transitional period?
The Commission will have the following tasks during the transitional period:
• Manage the CBAM Transitional Registry.
• Analyse the impact of CBAM on: Exports, downstream products, trade flows and LDCs.
• Prepare secondary legislation in the form of implementing acts:
o In Q3 2023 on the transitional period (art.35), reporting obligations and reporting infrastructure.
o In Q3 2024 on authorisation of declarants (art.5 and 17), the CBAM registry (art.14) and accreditation of verifiers (art.18).
o In Q2 2025 implementing acts on indirect emissions (annex IV), verification (art.8), carbon price paid (art.9), information for customs (art.25), continental shell (art.2), average ETS price (art.21), CBAM declaration (art.6), methodology (art.7) and free allocations (art.31).
• Prepare secondary legislation in the form of delegated acts during Q3 2024 for the accreditation of verifiers (art.18) and selling and repurchasing of certificates (art.20). If necessary, the Commission will also prepare delegated acts on exempted countries, rules on electricity and anti-circumvention.
• Prepare the methods for calculating and reporting embedded emissions during the definitive period.
• Set up the Common Central Platform where the sale, repurchase of certificates will take place in the definitive period.
Competent Authorities
What is a competent authority?
Each Member State has designated a competent authority, which will carry out the functions and duties as defined in Regulation (EU) 2023/956. The list of authorities will soon be published by the Commission.
What is the role of the competent authorities during the transitional period?
The tasks attributed to the competent authority will increase over time, where initially, during the transitional period, they will have to provide guidance to the importers and customs representatives, they will assist the Commission in the control of the CBAM reports during the transitional period.
CBAM Transitional Registry
What is the CBAM Transitional Registry?
In order to ensure an efficient implementation of reporting obligations, the Commission has developed an electronic database, which will collect the information reported during the transitional period. The CBAM Transitional Registry is a standardised and secured electronic database containing common data elements for reporting in the transitional period, and to provide for access, case handling and confidentiality. The CBAM Transitional Registry is the basis for the development and establishment of the CBAM Registry pursuant to Article 14 of Regulation (EU) 2023/956.
What will the CBAM Transitional Registry be used for?
The CBAM Transitional Registry shall enable communication between the Commission, the competent authorities, customs authorities of the Member States and reporting declarants.
The CBAM Transitional Registry will not be used for enforcement, as the information collected will solely serve to feed onto the data analysis and collection during the transitional period.
Customs
What obligations will customs representatives have?
During the transitional period, as indicated in article 32 Regulation (EU) 2023/956, the reporting obligation applies:
• if the importer is not established in a Member State: the indirect customs representative;
• if the importer is established in a Member State: the importer, or, subject to agreement, the indirect customs representative.
Definitive period
How will the CBAM work in practice during the definitive period?
The CBAM will mirror the ETS in the sense that the system is based on the purchase of certificates by importers. The price of the certificates will be calculated depending on the weekly average auction price of EU ETS allowances expressed in € / tonne of CO2 equivalents emitted. Importers of the goods will have to, either individually or through a representative, register to take part in the CBAM and buy CBAM certificates.
The certificatees surrendered by the CBAM declarant shall correspond to the amount of embedded emissions of the relevant goods expressed in tonnes of CO2. In any case, the authorised CBAM declarant shall ensure that the number of CBAM certificates on its account in the CBAM registry at the end of each quarter corresponds to at least 80 % of the embedded emissions. In addition, there is a possibility to purchase certificates along the year.
CBAM certificates will be sold by Member States through a common central platform to authorised CBAM declarants established in that Member State. Only authorised CBAM declarants are allowed to purchase certificates. These certificates shall be surrendered via the CBAM registry by 31 May each year being 2027 the first time, for the year 2026.
What will be the role of the European Commission during the definitive period?
The CBAM Regulation stipulates that the new mechanism should be run by the European Commission in coordination with relevant Member States’ competent authorities. Therefore, the Commission will be in charge of reviewing and verifying declarations as well as managing a central platform for the selling of CBAM certificates to importers. From 2026, importers of CBAM goods into the EU will have to declare by 31 May each year the quantity of goods and the embedded emissions in those goods imported into the EU in the preceding year. At the same time, they must surrender the CBAM certificates they have purchased in advance from the Commission.
How is a CBAM declarant authorised and what is the timeline for its authorisation during the definitive period?
The competent authority in the Member State in which the applicant is established shall grant the status of authorised CBAM declarant, when the applicant meets the following criteria:
– has not been involved in a serious infringement or in repeated infringements of customs legislation, taxation rules, market abuse rules or the CBAM Regulation;
– demonstrates its financial and operational capacity;
– is established in the Member State where the application has been submitted;
– has been assigned an EORI number.
A consultation procedure is required before granting the authorisation, and it should not exceed 15 working days.
How can EU importers ensure that they get the information they need from their non-EU exporters to be able to use the new system correctly?
Non-EU producers should provide the information on embedded emissions for goods subject to CBAM to the EU-registered importers of their goods. In cases where this information is not available at the time when the goods are being imported, EU importers will be able to use default values (even once the definitive system has kicked in) on CO2 emissions for each product to determine the number of certificates they need to purchase.
In addition, production sites outside the EU will have the possibility to register in the EU central database to communicate their emissions reports. This should facilitate compliance for any importer of CBAM goods produced in these sites.
Imports of goods from which countries will fall under the scope of the CBAM?
In principle, imports of goods from all non-EU countries will be covered by the CBAM. That said, certain third countries who participate in the ETS or have an emission trading system linked to the Union’s will be excluded from the mechanism. This is the case for members of the European Economic Area and Switzerland.
CBAM will be applied to electricity generated in and imported from third countries including those that wish to integrate their electricity markets with the EU. If those electricity markets are fully integrated and provided that certain strict obligations and commitments are implemented, these countries could be exempted from the mechanism. If that is the case, the EU will review any exemptions in 2030, at which point those partners should have put in place the decarbonisation measures they have committed to, and an emissions trading system equivalent to the EU’s.
How is the reliability of the reported information ensured (e.g. on embedded CO2 emissions)?
The Commission, in collaboration with Member States authorities, will continuously monitor reported emissions and corresponding trade, to identify practices of circumvention and non-compliance with the CBAM Regulation and its implementing acts. In addition, verifications will be carried out during the definitive period, and the report derived from them shall include information on the quantification of direct emissions and how these emissions are attributed to the different types of goods.
Declared embedded emissions should be verified by a verifier, accredited in accordance with Implementing Regulation (EU) 2018/2067, who will prepare a verification report. In line with this, CBAM declarations will be accompanied by copies of emissions verification reports.
Penalties shall be imposed when a CBAM declarant introduces goods into the customs territory of the Union without complying with the obligations established in the Regulation.
Is there any criteria to measure if the carbon price system applied in a third country is genuine, in order to be considered in a CBAM application?
Verifications will be carried out in order to ensure that CBAM declarants fulfil the obligations set up in the Regulation (EU) 2023/956 and its implementing act during the transitional period. From the definitive period onwards, as laid out in Article 9 of the CBAM Regulation, the information on a paid carbon price shall be certified by a person independent from the CBAM declarant and the authorities of the country of origin.
What is a carbon price?
As indicated in Regulation (EU) 2023/956, a carbon price is the monetary amount paid in a third country, under a carbon emissions reduction scheme, which can adopt various forms i.e. tax, levy, fee or in the form of emission allowances under a greenhouse gas emissions trading system, calculated on greenhouse gases covered by such a measure, and released during the production of goods.
Under the EU ETS, the cap determines the supply of emission allowances and provides certainty about maximum emissions of greenhouse gases. The carbon price is determined by the balance of that supply against the market demand. In contrast, CBAM Regulation (EU) 2023/956 does not impose a cap on the number of CBAM certificates available to importers.
How do importers report a carbon price or rebate?
CBAM declarants may claim a reduction in the number of certificates to be surrendered when a carbon price has been effectively paid in the country of origin. To proceed with any rebate or other form of compensation, the carbon price has to have been effectively paid, and records of documentation shall be required to demonstrate such payment. The Commission shall lay out the rules for the deduction of a carbon price paid abroad in a future implementing act in accordance with Article 9 of the Regulation.
CBAM Registry
How will I get access to the CBAM Registry in the definitive period?
Once an importer’s application has been authorised by the competent authority, it will be considered an authorised CBAM declarant. Each CBAM declarant will be assigned a CBAM account number by the Commission, which allows access to the CBAM registry.
How can the CBAM report be submitted?
The CBAM report shall be submitted through the CBAM registry by the authorised CBAM declarant.
When a customs declaration has been lodged, the competent authority of the Member State shall register the person in the CBAM registry. The competent authority shall also review the CBAM declaration, and therefore, check that the information from the applicant is complete and in line with Regulation (EU) 2023/956 to grant the authorisation.
Competent authorities are encouraged to exchange information, between themselves and with the European Commission, essential or relevant to the exercise of their duties. In addition, they shall be assisted by the Commission in carrying out their functions under the Regulation (EU) 2023/956.
Customs representatives
What obligations will customs representatives have?
During the definitive period, the CBAM obligations apply to the authorised CBAM declarant (Article 5):
• if the importer is not established in a Member State: the indirect customs representative;
• if the importer is established in a Member State: the importer, or, subject to agreement, the indirect customs representative.
Only authorised CBAM declarants may import goods into the Union (Article 4). It follows that if the importer is not established in a Member State and the indirect customs representative does not have the status of authorised CBAM declarant, the concerned CBAM goods cannot be imported in the Union.
The application to become an authorised CBAM declarant needs to contain information on the names and contact information of the persons on behalf of whom the applicant is acting, if applicable (Article 5(5)(h). This information will be stored in the CBAM Registry.
Next steps
The CBAM will enter into application in its transitional period on 1 October 2023, with the first reporting period for traders ending 31 January 2024. The set of rules and requirements for the reporting of emissions under CBAM will be further specified in an implementing act to be adopted by the Commission after consulting the CBAM Committee, made up of representatives from EU Member States. The Commission will continue setting up the transitional CBAM registry as well as preparing further secondary legislation and carrying out the planned analysis.
The European Commission is preparing detailed guidance for the application of CBAM during the transitional period and is developing training through webinars and e-learning etc. These will include training courses for reporting declarants, third-country operators and EU national authorities. A dedicated website with all information supporting implementation will soon be launched.
EUROPEAN COMMISSION Memo
Brussels, 14 July 2023

Slow demand pressures Turkish rebar prices even as lira depreciates
One of Turkey’s large long-steel producers, Bastug Metalurji opened its lira-denominated rebar sales in the domestic market at lower prices July 18
Bastug’s new price list shared with S&P Global Commodity Insights showed that the company began offering 12-32 mm rebar at Lira 18,800/mt ex-works, down Lira 300/mt week on week, including 18% value-added tax, equating to $580/mt EXW, excluding VAT.
The company also reduced the list prices of its 10 mm rebar to Lira 19,200/mt EXW and 8 mm rebar to Lira 19,400/mt EXW as of July 18. Both the prices were down Lira 300/mt from a week earlier.
Bastug closed its rebar order book July 13 in a bearish market, S&P Global Commodity Insights reported earlier.
Some other Turkish producers said they have also started offering rebar at lower prices in the domestic market July 18, with some of them mulling production cuts.
Koc Metalurji, based in Southeastern Turkey, said it has reduced its capacity usage to 50%. It said more capacity reductions were on the agenda if the market slowdown persisted and sales continued to decline.
Noting that producers in Southeastern Turkey were offering 12-32 mm rebar in the domestic market at Lira 18,600-18,800/mt EXW July 18, a manager at a trading company said stockist have started offering the same rebar grade at of lower price of Lira 18,400-18,500 mt to deplete stocks.
Some producers in our region could start production cuts soon, he said, adding that prices could continue to drop on a dollar basis in the wake of tepid demand.
Imported scrap prices have also weakened because of a lackluster finished product market.
Platts, part of S&P Global, assessed Turkish imports of premium heavy melting scrap 1/2 (80:20) at $365/mt CFR on July 17, down $2 on the day, while the assessment for Turkish exported rebar was stable day on day at $580/mt FOB.